Automated Machine Learning Market Size & Share Analysis - Growth Trends and Forecast (2026 - 2031)
Automated Machine Learning Market Size & Share Analysis - Growth Trends and Forecast (2026 - 2031)
Industry: Artificial Intelligence & ML (Technology, Media & Telecom (TMT))
Source: https://www.mordorintelligence.com/industry-reports/automated-machine-learning-market
Scraped Date: 2026-09-17
Key Market Estimates
| Variable | Value | Unit |
|---|
| Market Size (2026) | 3.68 | USD Billion |
|---|
| Market Size (2031) | 21.19 | USD Billion |
|---|
| Growth Rate (2026 - 2031) | 41.96 | PERCENT |
|---|
| Fastest Growing Market | Asia Pacific |
|---|
| Largest Market | North America |
|---|
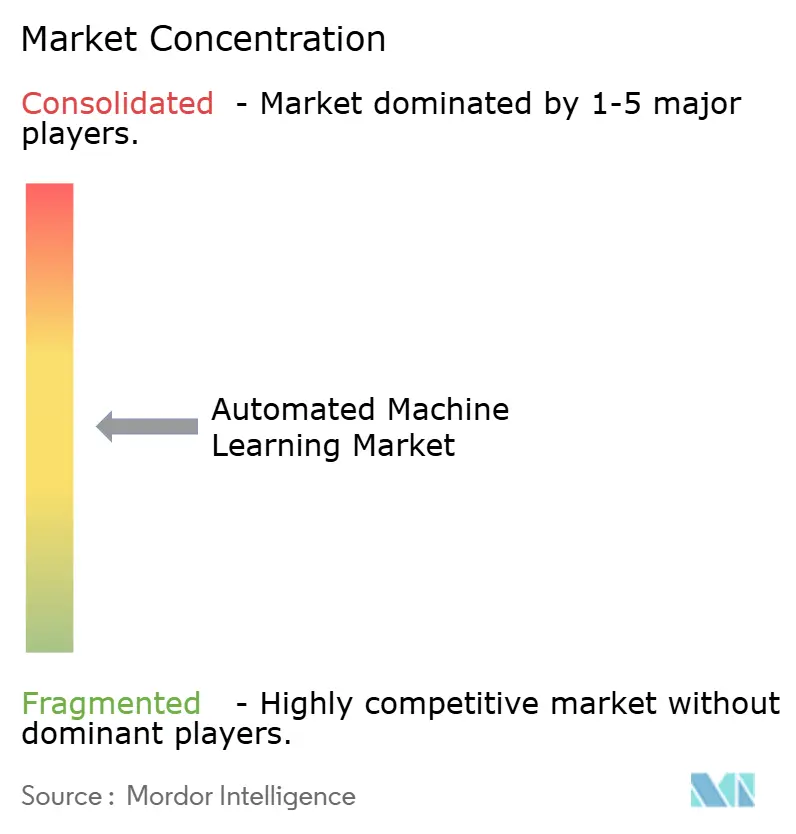
| Market Concentration | Medium |
|---|
Section 1
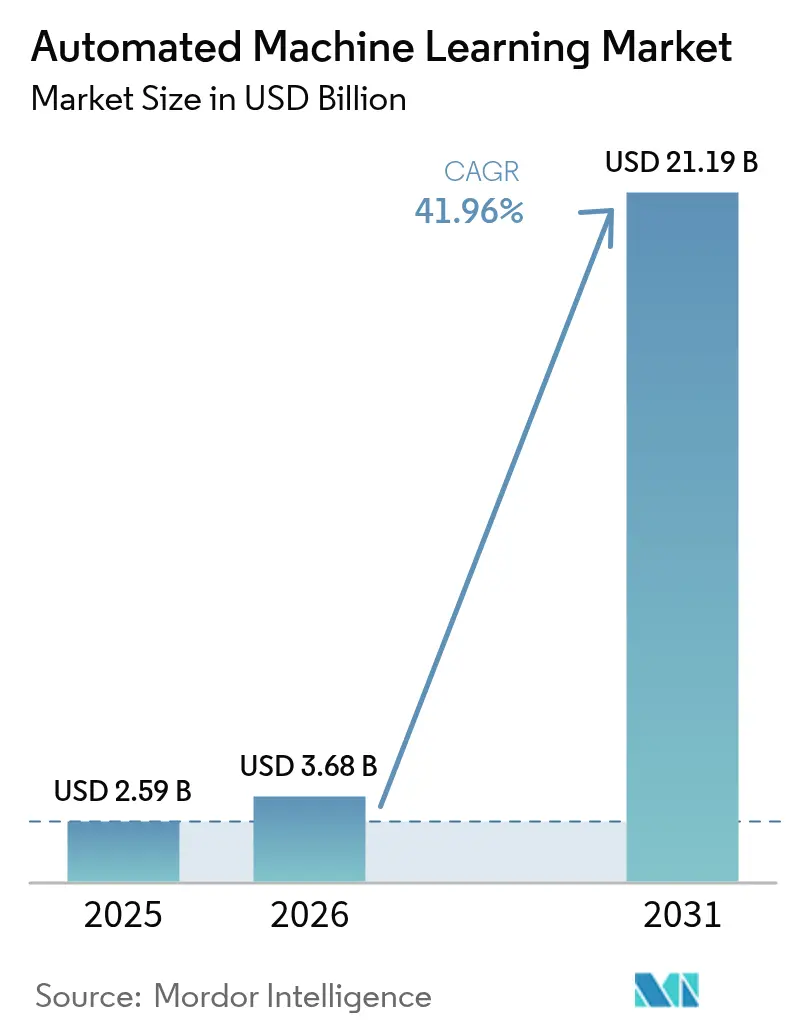
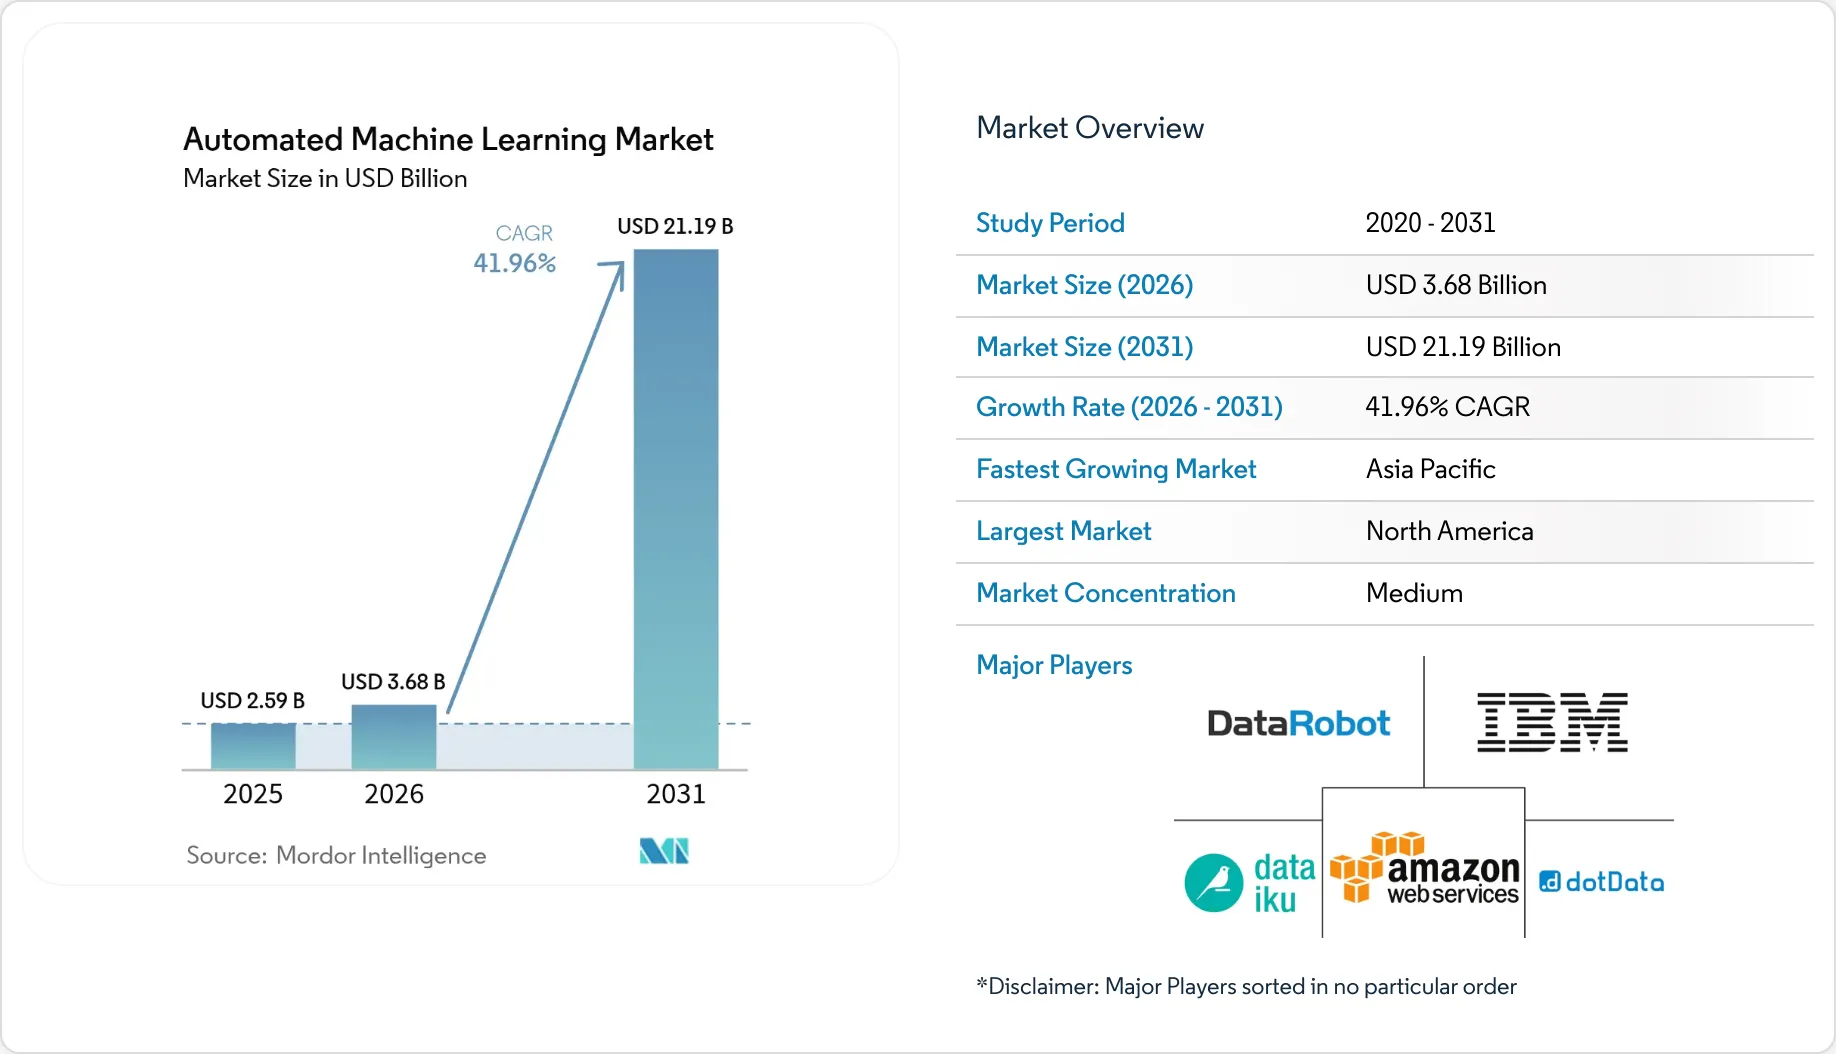
Automated Machine Learning Market Size and ShareMarket OverviewStudy Period | 2020 - 2031 |
Market Size (2026) | USD 3.68 Billion |
Market Size (2031) | USD 21.19 Billion |
Growth Rate (2026 - 2031) | 41.96 % |
Fastest Growing Market | Asia Pacific |
Largest Market | North America |
Market Concentration | Medium |
Major Players*Disclaimer: Major Players sorted in no particular order
Image © Vijeron Intelligence. Reuse requires attribution under CC BY 4.0.
Image © Vijeron Intelligence. Reuse requires attribution under CC BY 4.0.
Section 2
Automated Machine Learning Market Analysis by Vijeron IntelligenceThe Automated Machine Learning Market size was valued at USD 2.59 billion in 2025 and estimated to grow from USD 3.68 billion in 2026 to reach USD 21.19 billion by 2031, at a CAGR of 41.96% during the forecast period (2026-2031).
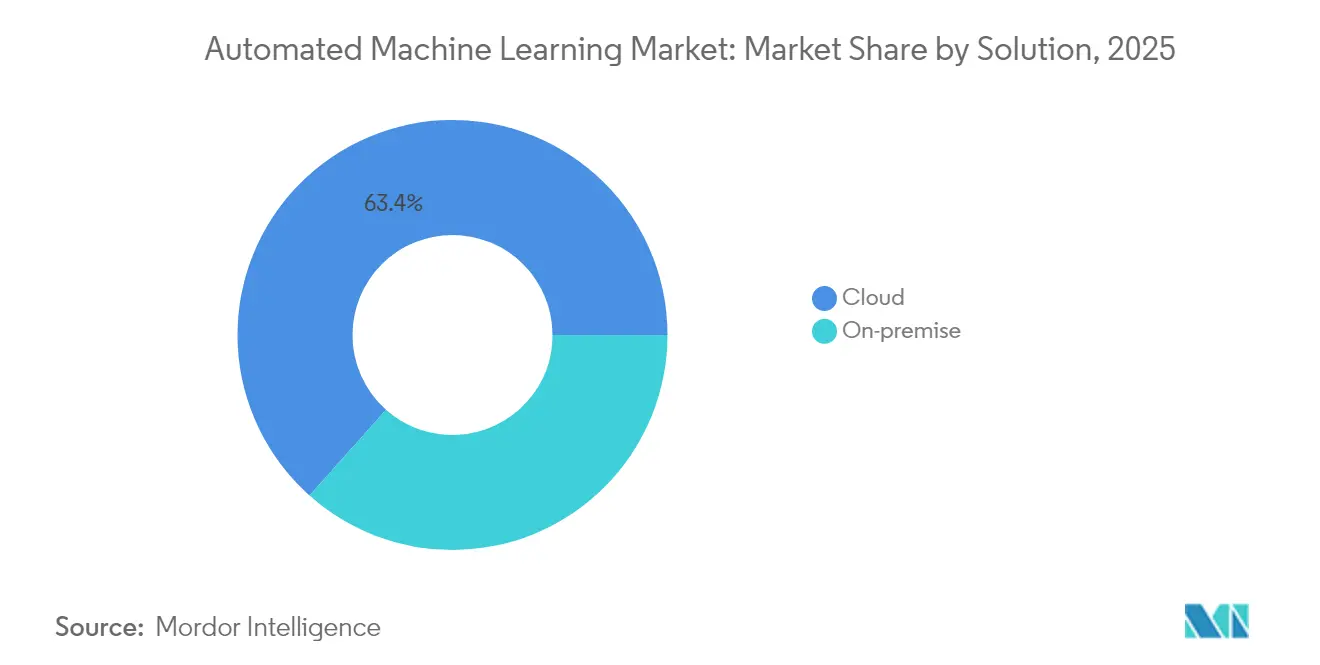
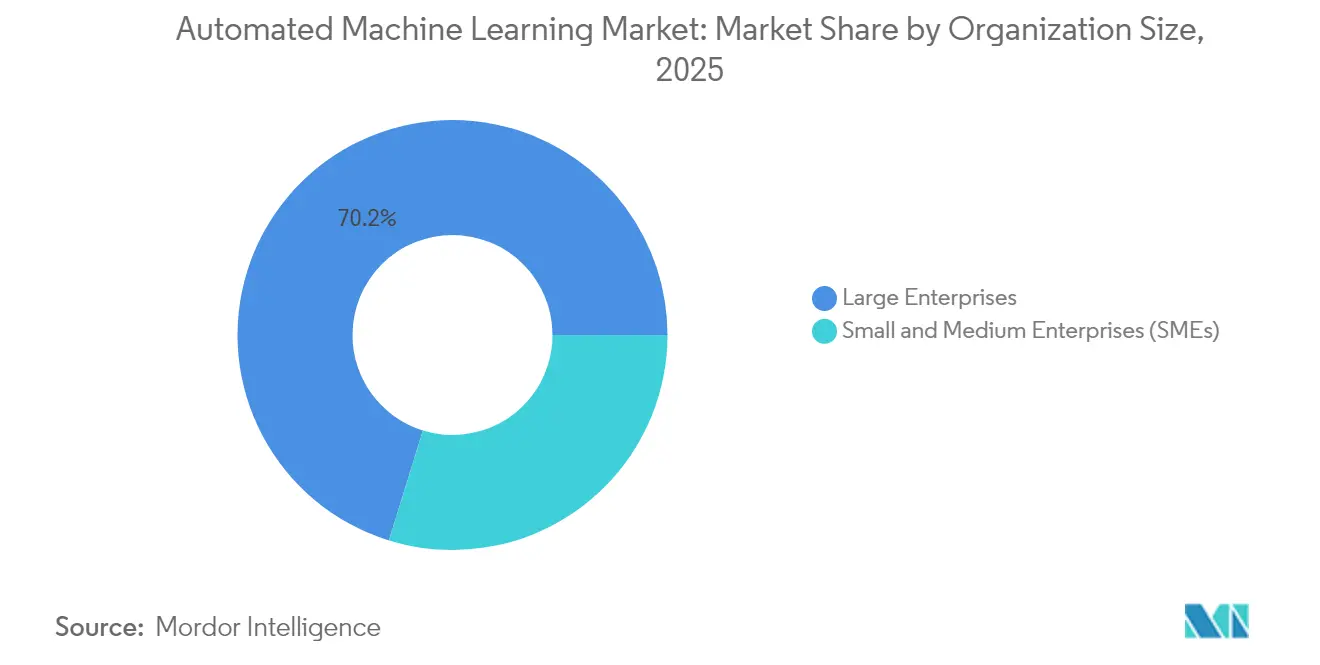
Commercial demand is reinforced by rapid cloud adoption, the need to scale artificial-intelligence initiatives without large data-science teams, and regulatory expectations for model transparency. Cloud-native offerings already account for 64% of global revenue and are expanding at 45.01% CAGR, underscoring the preference for managed infrastructure that shortens deployment cycles while lowering capital costs. Modeling automation holds the largest functional share, yet feature-engineering tools are growing faster as companies realise that data quality drives predictive accuracy more than algorithm selection. Large enterprises still dominate spending, but growth momentum is shifting to small and medium enterprises thanks to no-code interfaces and public-sector funding that offsets talent shortages. Regionally, North America leads in installed base, whereas Asia Pacific shows the strongest trajectory as governments embed AI goals into manufacturing and smart-city programs.
Key Report Takeaways* By solution, cloud deployments led with 63.42% of the automated machine learning market share in 2025, while the segment is projected to increase at 43.72% CAGR through 2031.
- By automation type, modeling automation held 40.35% revenue share in 2025; feature engineering is forecast to expand at 43.11% CAGR to 2031.
- By organization size, large enterprises captured 70.22% share of the automated machine learning market size in 2025, yet small and medium enterprises are advancing at 42.85% CAGR through 2031.
- By end-user, banking, financial services, and insurance commanded 30.44% of 2025 revenue, whereas healthcare is growing at 43.26% CAGR through 2031.
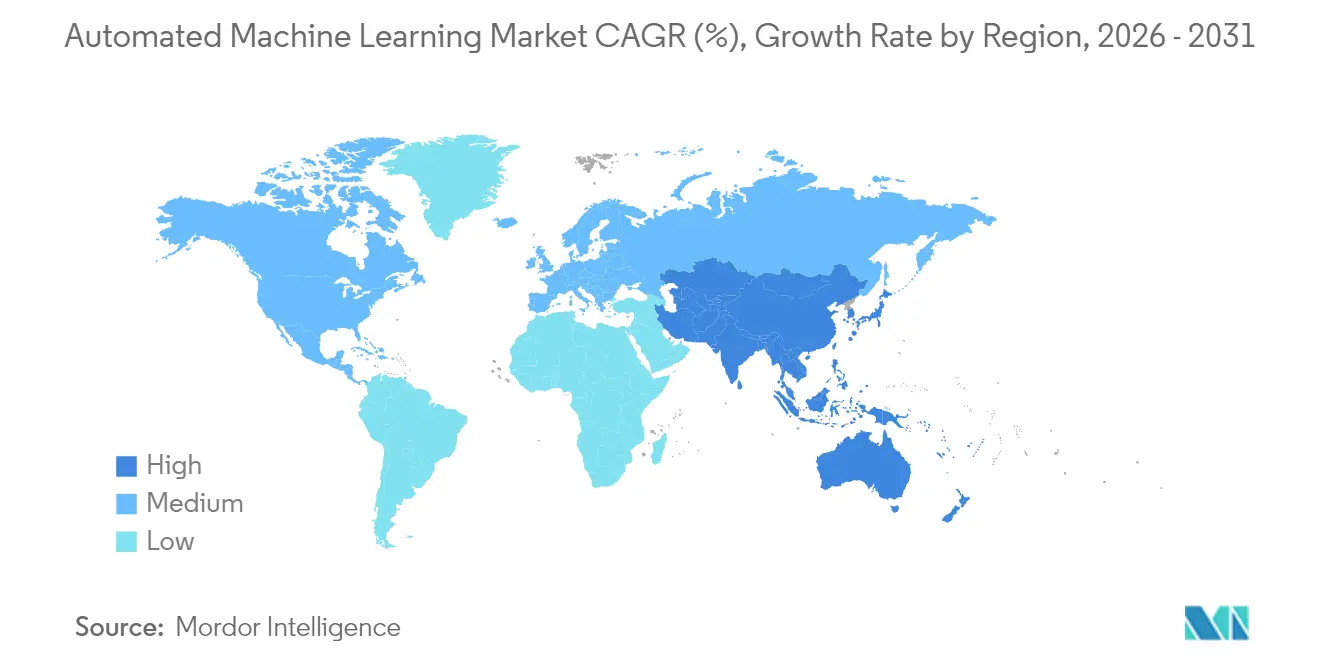
- By geography, North America accounted for 45.38% of 2025 revenue, while Asia Pacific is projected to register a 44.63% CAGR between 2026-2031.
Note: Market size and forecast figures in this report are generated using Vijeron Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Section 3
Market Trends and InsightsDrivers Impact Analysis of Automated Machine Learning Market*Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
Rising demand for efficient fraud-detection models | +8.2% | Global, concentrated in North America & Europe | Short term (≤ 2 years) |
Increasing need for intelligent business processes | +7.1% | Global, with early adoption in developed markets | Medium term (2-4 years) |
Cloud-first ML strategy of enterprises | +9.4% | Global, led by North America and Asia Pacific | Medium term (2-4 years) |
Shortage of skilled data-science labour | +6.8% | Global, acute in North America and Europe | Long term (≥ 4 years) |
Edge-native AutoML for on-device inference | +4.3% | Asia Pacific core, spill-over to North America | Long term (≥ 4 years) |
Regulatory push for model explainability | +5.7% | Europe & North America, expanding to Asia Pacific | Medium term (2-4 years) |
Source: Vijeron Intelligence |
Rising Demand for Efficient Fraud-Detection ModelsFinancial institutions are moving from static rule sets to AutoML-based fraud systems that learn from real-time transaction flows, cutting false positives and improving recovery rates. Insurers expect savings of USD 80–160 billion by 2032 as automated models mine structured and unstructured data for suspicious claims. Built-in natural-language processing allows platforms to digest call-centre transcripts and social-media signals, giving underwriters granular context for risk decisions. Vendors that deliver dashboards linking explanatory metrics to each prediction command price premiums because finance regulators are tightening disclosure standards. The net effect sustains an 8.2% uplift on forecast CAGR through 2026.
Increasing Need for Intelligent Business ProcessesEnterprises are embedding AutoML inside manufacturing, retail, and healthcare workflows to move beyond rule-based robotics toward adaptive optimisation. Sensor-driven predictive maintenance trims unplanned downtime by up to 30% and improves overall equipment effectiveness across semiconductor fabrication lines[1]Tracey Countryman, “Predictive Maintenance in Industry 4.0,” McKinsey, mckinsey.com. Retailers apply AutoML to demand planning and dynamic pricing, with pilots showing 22.7% revenue lifts when AI-generated insights feed merchandising engines. Oracle’s Clinical Digital Assistant illustrates healthcare gains, reducing physician documentation time by as much as 40% and freeing capacity for patient care. The convergence of analytics, workflow orchestration, and low-code modelling tools propels a 7.1% contribution to growth through mid-decade.
Cloud-First ML Strategy of EnterprisesEnterprises are shedding on-premises hardware in favour of elastic GPU clusters delivered as a service, which adds 9.4% to the forecast CAGR. Microsoft’s FY-2025 results highlight multibillion-dollar Azure AI bookings tied to AutoML model training and governance add-ons. AWS is scaling Project Rainier, a Trainium-2 super-cluster that multiplies available compute by fivefold to support large AutoML workloads. Oracle’s backlog of AI infrastructure contracts exceeds USD 12 billion, signalling durable demand for cloud capacity that aligns with data-sovereignty rules through region-specific availability zones. Multi-cloud procurement reduces lock-in while accelerating proof-of-concept timelines from months to weeks.
Shortage of Skilled Data-Science LabourGlobal demand for data-science roles outstrips supply, adding 6.8% to market growth as AutoML bridges capability gaps. Brazil reports a deficit of 500,000 AI professionals and relies on no-code AutoML to extend advanced analytics into business functions. The European Union’s adoption rate for AI nearly doubled to 13% between 2021 and 2024, yet many firms outsource model development because internal teams lack deep statistical expertise. Platforms such as Google AutoML popularise drag-and-drop interfaces, empowering marketing managers and operations analysts to build predictive models without Python or R coding.
Restraints Impact Analysis of Automated Machine Learning Market*Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
Slow enterprise adoption & culture gap | -4.8% | Global, pronounced in traditional industries | Short term (≤ 2 years) |
Data-security & privacy concerns in cloud workflows | -3.2% | Europe & North America, expanding globally | Medium term (2-4 years) |
Algorithmic bias compliance costs | -2.1% | Europe & North America, regulatory spillover | Medium term (2-4 years) |
Limited AutoML accuracy on long-horizon time-series | -1.9% | Global, sector-specific impact | Long term (≥ 4 years) |
Source: Vijeron Intelligence |
Slow Enterprise Adoption and Culture GapLegacy processes, risk-averse leadership, and workforce apprehension about job displacement slow AutoML rollouts, reducing market momentum by 4.8%. Many Asian banks still rely on manual anti-money-laundering reviews because their aged core systems complicate data integration. Small manufacturing firms in South Africa cite unclear frameworks and limited managerial sponsorship as primary impediments to AI projects, pushing deployment cycles beyond initial forecasts. Successful transformations combine training, change-management programs, and targeted incentives that align AI outcomes with employee performance metrics.
Data-Security and Privacy Concerns in Cloud WorkflowsGlobal privacy legislation mandates granular control over personal data, slicing 3.2% from forecast growth as firms weigh compliance versus agility. The EU’s General Data Protection Regulation obliges companies to explain automated decisions and to honour user rights to opt out of profiling, prompting demand for local hosting or hybrid architectures. Apple’s decision to postpone certain AI features in the EU underscores how rule-making can delay product launches. Financial services providers conduct extensive validation before uploading sensitive datasets, lengthening procurement cycles. Vendors now offer encryption-in-use and audit logging to reassure risk officers without reverting to costly on-premises stacks.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Section 4
Automated Machine Learning Market Segment AnalysisBy Solution:Cloud Dominance Accelerates Infrastructure ShiftCloud platforms generated 63.42% of revenue in 2025, and the segment is on track for 43.72% CAGR through 2031, a trajectory that validates the cost advantages of shared infrastructure. The automated machine learning market size for cloud deployments is projected to widen as hyperscalers integrate dedicated accelerators and serverless training pipelines. Continuous feature releases, enterprise-grade security certifications, and usage-based billing appeal to organisations seeking agility over hardware control. Bedrock, AWS’s model marketplace, lists more than 100 foundational and task-specific models, letting clients evaluate algorithms without owning GPUs, which compresses experimentation cycles.
On-premises deployments persist in finance, defence, and public sectors where data-residency mandates prohibit external hosting. Their share, however, is eroding as confidential-computing techniques allow secure processing in public-cloud environments. Hybrid patterns have emerged in which training occurs in the cloud while inference runs on edge devices to meet latency targets. Edge-native offerings enable offline operation for factories and retail outlets, ensuring business continuity when connectivity drops.
Image © Vijeron Intelligence. Reuse requires attribution under CC BY 4.0. By Automation Type:Feature Engineering Emerges as Growth LeaderModeling automation retained 40.35% of 2025 revenue yet feature engineering’s 43.11% CAGR signals a shift toward data-centric AI. The automated machine learning market share for feature automation is expanding because structured-data projects often fail without robust variable construction. Large language models now assist in mapping raw fields to domain-ready features, automating semantic joins and text embeddings that previously demanded specialist knowledge.
Visualization and data-processing automation support wider adoption by translating plain-language questions into SQL queries and interactive charts. Research combining evolutionary algorithms with LLM prompts has cut computation time while improving predictive lift on benchmark datasets. Healthcare and finance users benefit most, as domain-specific ontologies are embedded into feature pipelines, satisfying auditing requirements without manual intervention.
By Organization Size:SME Acceleration Drives Market DemocratizationLarge enterprises held 70.22% of spending in 2025, yet SMEs register a 42.85% CAGR that outpaces the wider market. Government grants and cloud credits lower entry barriers, allowing mid-market firms to test AutoML before committing large budgets. The automated machine learning market size for SMEs is forecast to double every 18 months in Latin America, following Brazil’s BRL 23 billion AI fund that subsidises tooling and talent programs.
No-code interfaces reduce reliance on scarce data scientists, and templated solutions target common use cases such as churn prediction, inventory planning, and invoice fraud. Research shows medium-sized firms gain more from perceived relative advantage than smaller peers, pointing to organisational maturity as a success factor. Return-on-investment studies reveal payback in under 14 months when AutoML enhances export documentation and trade financing processes.
Image © Vijeron Intelligence. Reuse requires attribution under CC BY 4.0. By End-User:Healthcare Acceleration Outpaces Financial-Services LeadershipFinancial services institutions captured 30.44% of the 2025 demand thanks to early fraud-detection and risk-modelling use cases. Healthcare grows faster at 43.26% CAGR as clinical-decision support, imaging triage, and patient-flow optimisation mature. The automated machine learning market size for healthcare is underpinned by explainability modules that satisfy medical-device regulators and hospital ethics boards.
Retail and e-commerce deploy AutoML for personalisation engines that lift conversion by double-digit percentages. Manufacturing applies real-time quality control on production lines, while energy utilities model load patterns to stabilise smart grids. Government agencies increasingly automate benefits adjudication; Brazil’s social-security institute aims to process 55% of welfare claims via AI by 2025.
Section 5
Geography AnalysisNorth America Automated Machine Learning MarketNorth America generated 45.38% of global revenue in 2025 on the back of dense cloud-infrastructure footprints, a mature venture-capital ecosystem, and high adoption in banking and technology sectors. Oracle’s cloud-infrastructure revenue rose 52% in fiscal 2025 as regulated industries moved core workloads to its FedRAMP-compliant regions. Venture investors closed more than 200 AutoML-related funding rounds in 2024, feeding a vibrant start-up pipeline that accelerates product innovation.
APAC Automated Machine Learning MarketAsia Pacific records the strongest trajectory with 44.63% CAGR through 2031 as governments deploy national AI strategies. Japan’s AI economy is projected to expand from USD 4.5 billion to USD 7.3 billion by 2027, driven by smart-city pilots, predictive maintenance programs in heavy industry, and local-language conversational agents. China leads in patent publications for 37 of 44 critical technologies, affirming its status as a powerhouse for both research and commercial implementation. Southeast Asian manufacturers adopt AutoML for yield optimisation to offset rising labour costs and supply-chain volatility.
Europe Automated Machine Learning MarketEurope presents a mixed environment. The GDPR and forthcoming AI Act introduce strict governance that elongates sales cycles but ultimately favours platforms with embedded transparency controls. The region’s AI adoption doubled to 13% by 2024, yet many firms outsource technical builds, creating fertile ground for managed AutoML services. National recovery funds earmark billions of euros for digital-transformation projects, including health-data spaces that require automated modelling engines.
MEA and South America Automated Machine Learning MarketThe Middle East pursues headline investments to diversify economies. Saudi Arabia has earmarked USD 100 billion for AI and digital infrastructure under Vision 2030, with further capital allocated to a planned 6-gigawatt data-centre corridor. The United Arab Emirates expects its AI Strategy 2031 to cut federal-service costs by 50%, driving procurement of AutoML platforms that automate citizen services. South America benefits from Brazil’s national AI strategy, which funds Portuguese-language models and HPC upgrades. Africa is an emerging frontier; 40% of surveyed institutions are piloting AI, and cloud-hosted AutoML lowers the barrier where local compute resources remain scarce.
Image © Vijeron Intelligence. Reuse requires attribution under CC BY 4.0.
Section 6
Regulatory LandscapeRegulation affecting AutoML is tightening around automated decision-making, documentation, and governance, with different requirements across major markets. In the European Union, the EU AI Act (Regulation (EU) 2024/1689) sets a prescriptive, risk-based framework; its governance and general-purpose AI provisions started applying from August 2025, with broader requirements moving into full application from August 2026. This raises the compliance bar for AutoML used in high-risk domains, with obligations covering risk management, technical documentation, and human oversight.
In the United States, policy direction emphasizes sector-led oversight and standards, anchored by NIST AI RMF 1.0 and follow-on profiles. This includes NIST work in April 2026 on a Trustworthy AI profile for critical infrastructure. Separately, the Algorithmic Accountability Act of 2025 (S.2164), introduced in June 2025, frames potential FTC-led impact assessment requirements for automated decision systems. In the United Kingdom, the Data Protection Act 2018 (Code of Practice on Artificial Intelligence and Automated Decision-Making) Regulations 2026 formalize a code-of-practice pathway via the Information Commissioner, reinforcing privacy, transparency, and explainability expectations that shape how AutoML platforms package audit trails and decision explanations.
Section 7
Value Chain AnalysisThe AutoML value chain spans compute and infrastructure, data and model tooling, and implementation: (1) hardware accelerators and servers; (2) cloud and platform infrastructure (hyperscalers and managed Kubernetes/AI stacks); (3) data sourcing, labeling, governance, and privacy controls; (4) foundation and task models plus AutoML automation layers (feature engineering, modeling, and monitoring); and (5) application delivery, integration, and managed services that embed AutoML into line-of-business workflows. Supplier power concentrates in compute and IaaS layers, which influences platform economics and drives buyer mitigation strategies such as multi-cloud, hybrid, and confidential-computing patterns.
Downstream, systems integrators, ISVs, and vertical specialists operationalize AutoML through MLOps, security, and domain templates. A notable shift is deploying models closer to operations at the edge. Telecom-oriented deployments show how the platform-to-operations chain is being executed: Mavenir and Red Hat announced an on-premise OpenShift AI collaboration (February 2026), Nokia expanded work with AWS to host Nokia Autonomous Network Fabric on AWS for higher autonomy levels (June 2026), and AT&T deployed H2O.ai Super Agent to orchestrate agentic workflows across network operations and fraud prevention (July 2026). These examples underline how data residency, latency, and governance needs push hybrid delivery models and raise the importance of runtime monitoring and controls within the AutoML stack.
Section 8
Competitive Landscape
The market remains moderately fragmented. Hyperscale cloud providers such as Microsoft, AWS, and Oracle leverage integrated infrastructure, global data-centre grids, and large engineering teams to bundle AutoML into platform subscriptions. AWS’s Bedrock service adopts an open-model catalogue, while Microsoft aligns closely with proprietary LLM distributors. Oracle’s planned USD 40 billion procurement of Nvidia hardware for its Texas facility under the Stargate project illustrates capital intensity that new entrants struggle to match.
Specialist vendors differentiate through domain expertise and governance. DataRobot introduced an enterprise suite with pre-built compliance workflows aligned to the EU AI Act, targeting financial services and healthcare buyers. H2O.ai focuses on transparent algorithms and open-source lineage, appealing to regulated industries requiring auditability[3]Sri Ambati, “Explainable AI at Scale,” H2O.ai, h2o.ai . Alteryx embeds generative AI across its analytics platform, bridging data preparation, model building, and decision automation for business users.
Edge-native innovations create white-space opportunities. Start-ups file patents for distributed model-training approaches that handle intermittent connectivity on factory floors and in autonomous vehicles. Vendors able to offer one-click deployment from cloud training to edge inference stand to capture the spend allocated to latency-sensitive applications. As regulatory scrutiny deepens, platforms that combine automation with explainability and monitoring are likely to consolidate share.
Automated Machine Learning Industry Leaders* Datarobot Inc.
- Amazon web services Inc.
- dotData Inc.
- IBM Corporation
- Dataiku
- *Disclaimer: Major Players sorted in no particular order
Image © Vijeron Intelligence. Reuse requires attribution under CC BY 4.0.Automated Machine Learning Market Companies Covered in this Report* Amazon Web Services, Inc.
- Alphabet Inc.
- Microsoft Corporation
- International Business Machines Corporation
- DataRobot, Inc.
- H2O.ai, Inc.
- Dataiku, Inc.
- SAS Institute Inc.
- dotData, Inc.
- Aible, Inc.
- Oracle Corporation
- SAP SE
- Alteryx, Inc.
- RapidMiner, Inc.
- KNIME AG
- BigML, Inc.
- TIBCO Software Inc.
- Databricks, Inc.
- Hewlett Packard Enterprise Company
Section 9
Market Opportunities and Future Outlook
White space is widening for governed, production-grade AutoML that supports regulated, distributed environments, particularly as buyers move from model-building automation toward end-to-end lifecycle controls such as lineage, monitoring, and audit-ready documentation. This demand aligns with regulatory milestones including the EU AI Act timeline (governance and GPAI provisions active since August 2025, broader application from August 2026) and U.S. standards activity like NIST AI RMF profiles for critical infrastructure (April 2026 concept note). Platforms that package impact assessment artifacts, human oversight workflows, and explainability at scale have a more direct procurement path in BFSI, healthcare, and public sector workloads, where on-premises, edge, and air-gapped deployments still matter.
Another opportunity sits in automation that is hardware-aware and agent-centric, where AutoML converts business intent into deployed workflows while accounting for data gravity across modern cloud data estates. Vendor moves reinforce this direction: Dataiku launched Cobuild on Snowflake and later moved Cobuild into general availability (May and June 2026), and DataRobot expanded governance beyond the cloud for on-premises, edge, and air-gapped environments (July 2026). On the innovation side, Google Cloud made AlphaEvolve generally available on its Gemini Enterprise Agent Platform (July 2026), reflecting interest in automated code and pipeline optimization that can shorten model experimentation and deployment cycles. Taken together, these changes point to near-term commercialization paths in governed agents, secure integrations, and hybrid runtime operations, rather than standalone model selection tools.
Section 10
Recent Industry Developments in Automated Machine Learning Market* July 2026: DataRobot announced expanded AI governance capabilities designed to operate across on-premises, edge, and air-gapped environments. The update extends governance controls beyond cloud-only deployments, aligning AutoML adoption with data residency and restricted-network requirements. It strengthens DataRobot positioning in regulated and mission-critical use cases that prioritize auditability and controlled runtime operations.
- June 2026: Nokia expanded work with AWS to host Nokia Autonomous Network Fabric on AWS for higher autonomy levels. The collaboration enables deployment of autonomous networking functions on AWS, reducing latency and increasing governance visibility across multi-cloud environments.
- November 2024: DataRobot released its Enterprise AI Suite with enhanced observability and pre-configured compliance templates aligned to the EU AI Act. The suite packaged monitoring and governance functions into a unified offering, lowering implementation friction for risk and compliance teams. This helped accelerate adoption in regulated industries where explainability and continuous oversight are procurement prerequisites.
Section 11
Table of Contents for Automated Machine Learning Industry Report1. INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
- RESEARCH METHODOLOGY
- EXECUTIVE SUMMARY
- MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers* 4.2.1 Rising demand for efficient fraud-detection models
- 4.2.2 Increasing need for intelligent business processes
- 4.2.3 Cloud-first ML strategy of enterprises
- 4.2.4 Shortage of skilled data-science labour
- 4.2.5 Edge-native AutoML for on-device inference (under-reported)
- 4.2.6 Regulatory push for model explainability (under-reported)
- 4.3 Market Restraints* 4.3.1 Slow enterprise adoption and culture gap
- 4.3.2 Data-security and privacy concerns in cloud workflows
- 4.3.3 Algorithmic bias compliance costs (under-reported)
- 4.3.4 Limited AutoML accuracy on long-horizon time-series (under-reported)
- 4.4 Value/Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis* 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Key Macroeconomic Trends
- MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Solution* 5.1.1 On-premise
- 5.1.2 Cloud
- 5.2 By Automation Type* 5.2.1 Data Processing
- 5.2.2 Feature Engineering
- 5.2.3 Modeling
- 5.2.4 Visualization
- 5.3 By Organization Size* 5.3.1 Large Enterprises
- 5.3.2 Small and Medium Enterprises (SMEs)
- 5.4 By End-user* 5.4.1 BFSI
- 5.4.2 Retail and E-commerce
- 5.4.3 Healthcare
- 5.4.4 Manufacturing
- 5.4.5 Other End-users
- 5.5 By Geography* 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 United Kingdom
- 5.5.2.2 Germany
- 5.5.2.3 France
- 5.5.2.4 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 South Korea
- 5.5.3.4 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 United Arab Emirates
- 5.5.4.2 Saudi Arabia
- 5.5.4.3 South Africa
- 5.5.4.4 Rest of Middle East and Africa
- 5.5.5 South America
- 5.5.5.1 Argentina
- 5.5.5.2 Brazil
- 5.5.5.3 Rest of South America
- COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)* 6.4.1 Amazon Web Services, Inc.
- 6.4.2 Alphabet Inc.
- 6.4.3 Microsoft Corporation
- 6.4.4 International Business Machines Corporation
- 6.4.5 DataRobot, Inc.
- 6.4.6 H2O.ai, Inc.
- 6.4.7 Dataiku, Inc.
- 6.4.8 SAS Institute Inc.
- 6.4.9 dotData, Inc.
- 6.4.10 Aible, Inc.
- 6.4.11 Oracle Corporation
- 6.4.12 SAP SE
- 6.4.13 Alteryx, Inc.
- 6.4.14 RapidMiner, Inc.
- 6.4.15 KNIME AG
- 6.4.16 BigML, Inc.
- 6.4.17 TIBCO Software Inc.
- 6.4.18 Databricks, Inc.
- 6.4.19 Hewlett Packard Enterprise Company
- MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment
Section 12
Automated Machine Learning Market Report Scope and Research MethodologyMarket Definition and CoverageFor this study, the automated machine learning market covers software and related services that automate key machine learning steps, such as data preparation, feature engineering, model selection, and tuning, delivered through cloud or on-premise deployments for business use.
Scope exclusions: This sizing excludes general purpose AI infrastructure, non-AutoML analytics tools, and custom in-house ML development work that is not sold as an AutoML product or service.
Segments Covered in This Report By Solution On-premise
- Cloud
- By Automation Type* Data Processing
- Feature Engineering
- Modeling
- Visualization
- By Organization Size* Large Enterprises
- Small and Medium Enterprises (SMEs)
- By End-user* BFSI
- Retail and E-commerce
- Healthcare
- Manufacturing
- Other End-users
- By Geography North America United States
- Canada
- Mexico
- Europe* United Kingdom
- Germany
- France
- Rest of Europe
- Asia-Pacific* China
- Japan
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa* United Arab Emirates
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- South America* Argentina
- Brazil
- Rest of South America
Data Sources, Market Sizing, and ValidationDesk Research
Desk work starts with building a clear map of what counts as AutoML revenue and what does not, then collecting public signals that explain demand and spending patterns. We referenced materials such as US National Institute of Standards and Technology (NIST) publications on AI risk management, OECD AI policy resources, World Bank and IMF macro indicators for IT spending context, US Bureau of Economic Analysis series for digital economy signals, and WIPO patent statistics to understand innovation activity.
We then reviewed annual reports, earnings transcripts, product documentation, pricing pages, customer case studies, and credible press coverage to confirm where AutoML is sold as a platform, packaged tool, or service bundle. In parallel, we used a paid company financials and intelligence subscription to normalize segment revenues and to track corporate actions that can shift reported revenue lines. These desk sources are illustrative only, and many other public documents and datasets were also used for data collection, cross-checking, and clarifying assumptions.
Primary Interviews and Surveys
Primary work was used to pressure-test the scope, the typical buying motion, and real pricing behavior for AutoML across cloud, on-premise, and service-led implementations. We spoke with a mix of platform providers, systems integrators, ML engineering teams, data science leaders, and procurement stakeholders across major regions to close gaps from desk research and confirm assumptions before finalizing the market model.
Distribution of primary research fieldwork respondents
Company type | Respondent position | Region |
Top tier: 25% | CXOs: 12% | APAC: 47% |
Mid tier: 60% | Functional/Unit leaders: 39% | EMEA: 32% |
Smaller Players: 15% | Managers: 49% | Americas: 21% |
Market-Sizing & ForecastingSizing is built using top-down and bottom-up logic, but the model is anchored in a top-down build that reconstructs the spend pool by region and vertical, then applies adoption and usage assumptions for AutoML tools and services. To keep totals realistic, we corroborate results with selective bottom-up approximations, such as sampled vendor revenue splits, channel checks with integrators, and ASP-by-deployment estimates multiplied by active customer counts.
Inputs used in the model include cloud versus on-premise mix shifts, AI and analytics software spending signals, the pace of enterprise ML adoption, average contract sizes by organization size, and the share of projects moving from pilot to production (a key AutoML demand fingerprint). Where bottom-up signals are missing for smaller countries or niche industries, we use peer-market ratios and confirm them with interview feedback. Forecasts are then produced using scenario analysis with a base case that ties adoption rates and ASP progression to macro IT budgets and the expected rollout of AI governance and model risk practices.
Data Validation & Update CycleValidation is done through stepwise cross-checks, starting with making sure the totals reconcile with independent demand signals like enterprise software budget growth, cloud workload expansion, and observed deal-size ranges from interviews. Outliers are flagged when a region, vertical, or deployment split moves too far from the prior-year pattern without a clear driver, and then the inputs are re-checked and corrected.
Before sign-off, the model and written insights go through a multi-analyst review so assumptions, math, and narrative stay aligned. Reports are refreshed annually, and interim updates are triggered when material events occur, such as major pricing changes, large acquisitions, or sudden regulatory shifts. Right before delivery, we perform a final pass to ensure the latest public information is reflected in the numbers and commentary.
Vijeron Intelligence's Automated Machine Learning Market Size Measured Against Other Published EstimatesPublished market values for automated machine learning can look far apart because the included revenue lines are not consistent, and the time stamps for pricing and currency conversion are not always aligned. Differences also come from how each publisher treats bundled AI platforms and services, plus how fast they refresh assumptions for cloud consumption growth.
Some external estimates broaden the scope to include wider AI software suites, general analytics, or adjacent MLOps tooling that sits outside AutoML. In Vijeron Intelligence, revenue is counted only when the product or service is explicitly positioned and purchased for automating ML pipeline steps (data processing, feature engineering, modeling, and related automation), and platform spend that is not attributable to AutoML is kept out.
Benchmark comparison
Source | Market Size | Gaps in Research Methodology |
Vijeron Intelligence | USD 2.59 B (2025) | |
Trade Journal A | USD 2.22 B (2024) | Uses an earlier base year and a narrower revenue capture that leans toward packaged AutoML tools, with limited visibility into services and enterprise-wide platform bundles. |
Industry Research Publisher B | USD 1.10 B (2023) | Back-solves from older vendor-reported lines and applies a conservative adoption curve, which tends to undercount cloud-based consumption and newer AutoML add-ons sold inside broader platforms. |
Overall, the spread mainly reflects scope decisions and the year used for pricing and demand signals, and then those differences compound quickly in a fast-growth software category. By tying the size to clear AutoML activity and checking it against deal-size ranges, deployment mix, and enterprise adoption behavior, our estimate stays traceable to repeatable inputs that a buyer can validate.
Section 13
Key Questions Answered in the ReportWhat is the current size of the automated machine learning market? The automated machine learning market is valued at USD 3.68 billion in 2026 and is projected to reach USD 21.19 billion by 2031.
Which deployment model grows fastest in automated machine learning? Cloud-based solutions expand at 43.72% CAGR because they provide elastic compute, frequent feature updates, and lower upfront costs.
Why is healthcare the fastest-growing end-user segment? Regulatory clarity and the need for clinical decision support drive healthcare to a 43.26% CAGR, outpacing other industries in adopting explainable AutoML tools.
How are talent shortages influencing adoption? Limited availability of data-science professionals pushes firms toward no-code AutoML platforms, adding 6.8% to overall market CAGR.
What regions present the highest growth potential through 2031? Asia Pacific leads with a 44.63% CAGR, fuelled by national AI policies, manufacturing modernisation, and rising cloud penetration.
How do data-privacy regulations affect cloud AutoML uptake? Strict frameworks such as the EU GDPR slow deployments by 3.2% CAGR points as firms demand hybrid or local-hosted options with strong auditing capabilities.
Section 14
Related Reports Explore More ReportsMarket Analysis of Adaptive AIAI Data Labeling Market GrowthMarket Trends in AI PlatformCloud AI Market ResearchData Mining Market TrendsEnterprise AI Market ShareExplainable AI Market GrowthArtificial Intelligence Market TrendsMachine Learning As A Service (MLaaS) Market ShareSearch Engine Market