Gene Therapy Market Size & Share Analysis - Growth Trends and Forecast (2026 - 2031)
Gene Therapy Market Size & Share Analysis - Growth Trends and Forecast (2026 - 2031)
Industry: Biotechnology & Genomics (Healthcare (Pharma, Medical Devices, Biotech))
Source: https://www.mordorintelligence.com/industry-reports/gene-therapy-market
Scraped Date: 2026-09-17
Key Market Estimates
| Variable | Value | Unit |
|---|
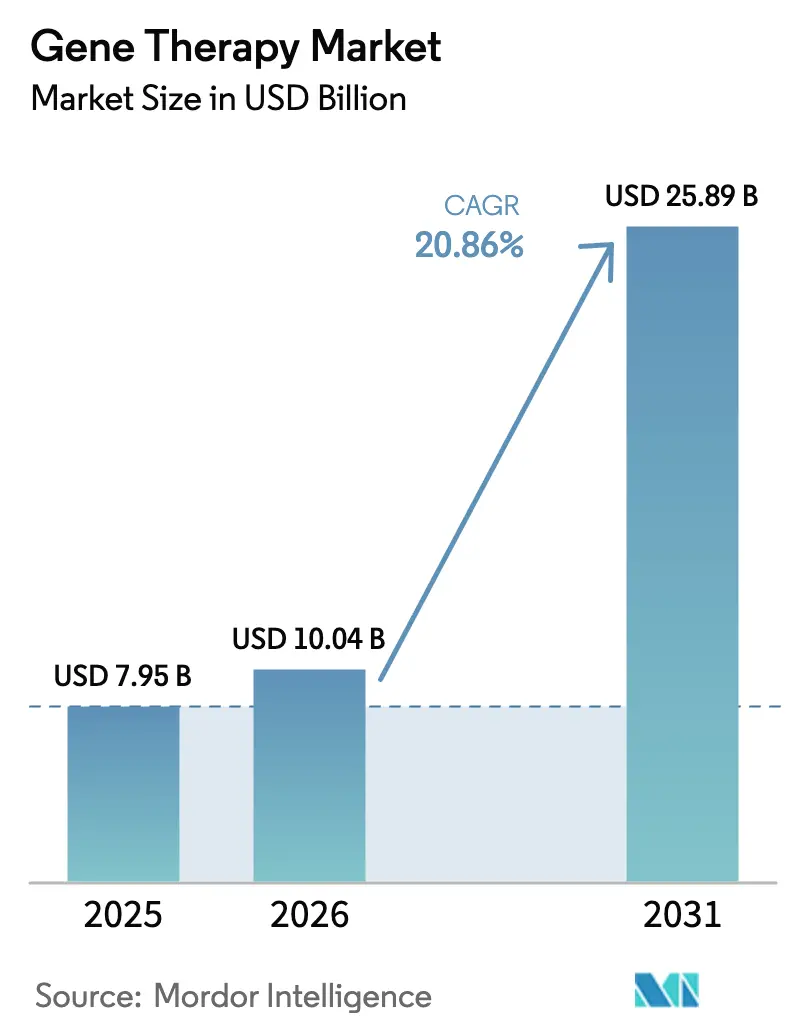
| Market Size (2026) | 10.04 | USD Billion |
|---|
| Market Size (2031) | 25.89 | USD Billion |
|---|
| Growth Rate (2026 - 2031) | 20.86 | PERCENT |
|---|
| Fastest Growing Market | Asia Pacific |
|---|
| Largest Market | North America |
|---|
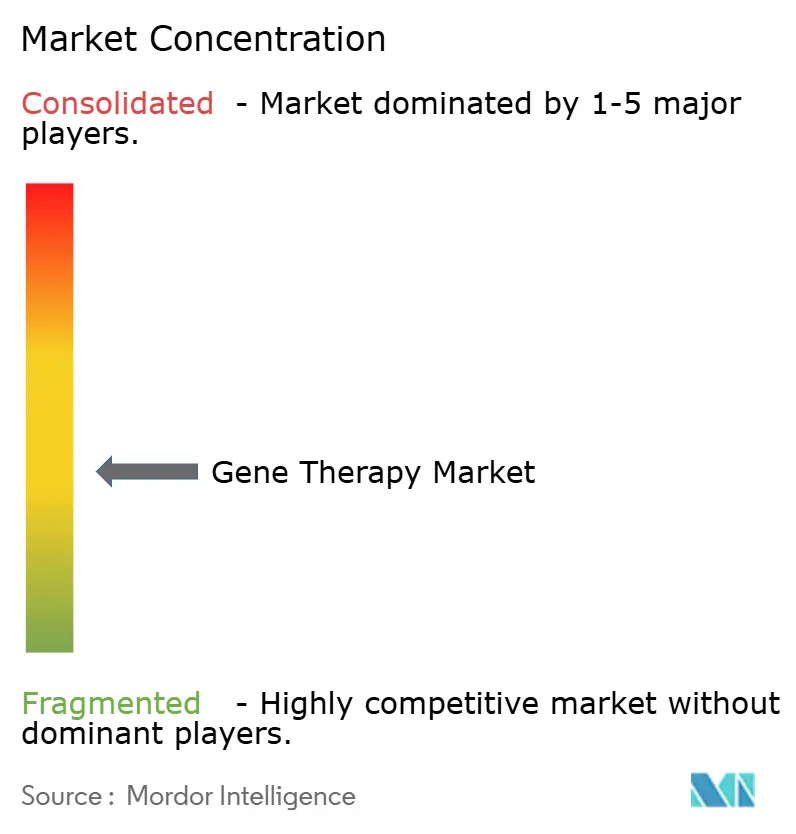
| Market Concentration | Medium |
|---|
Section 1
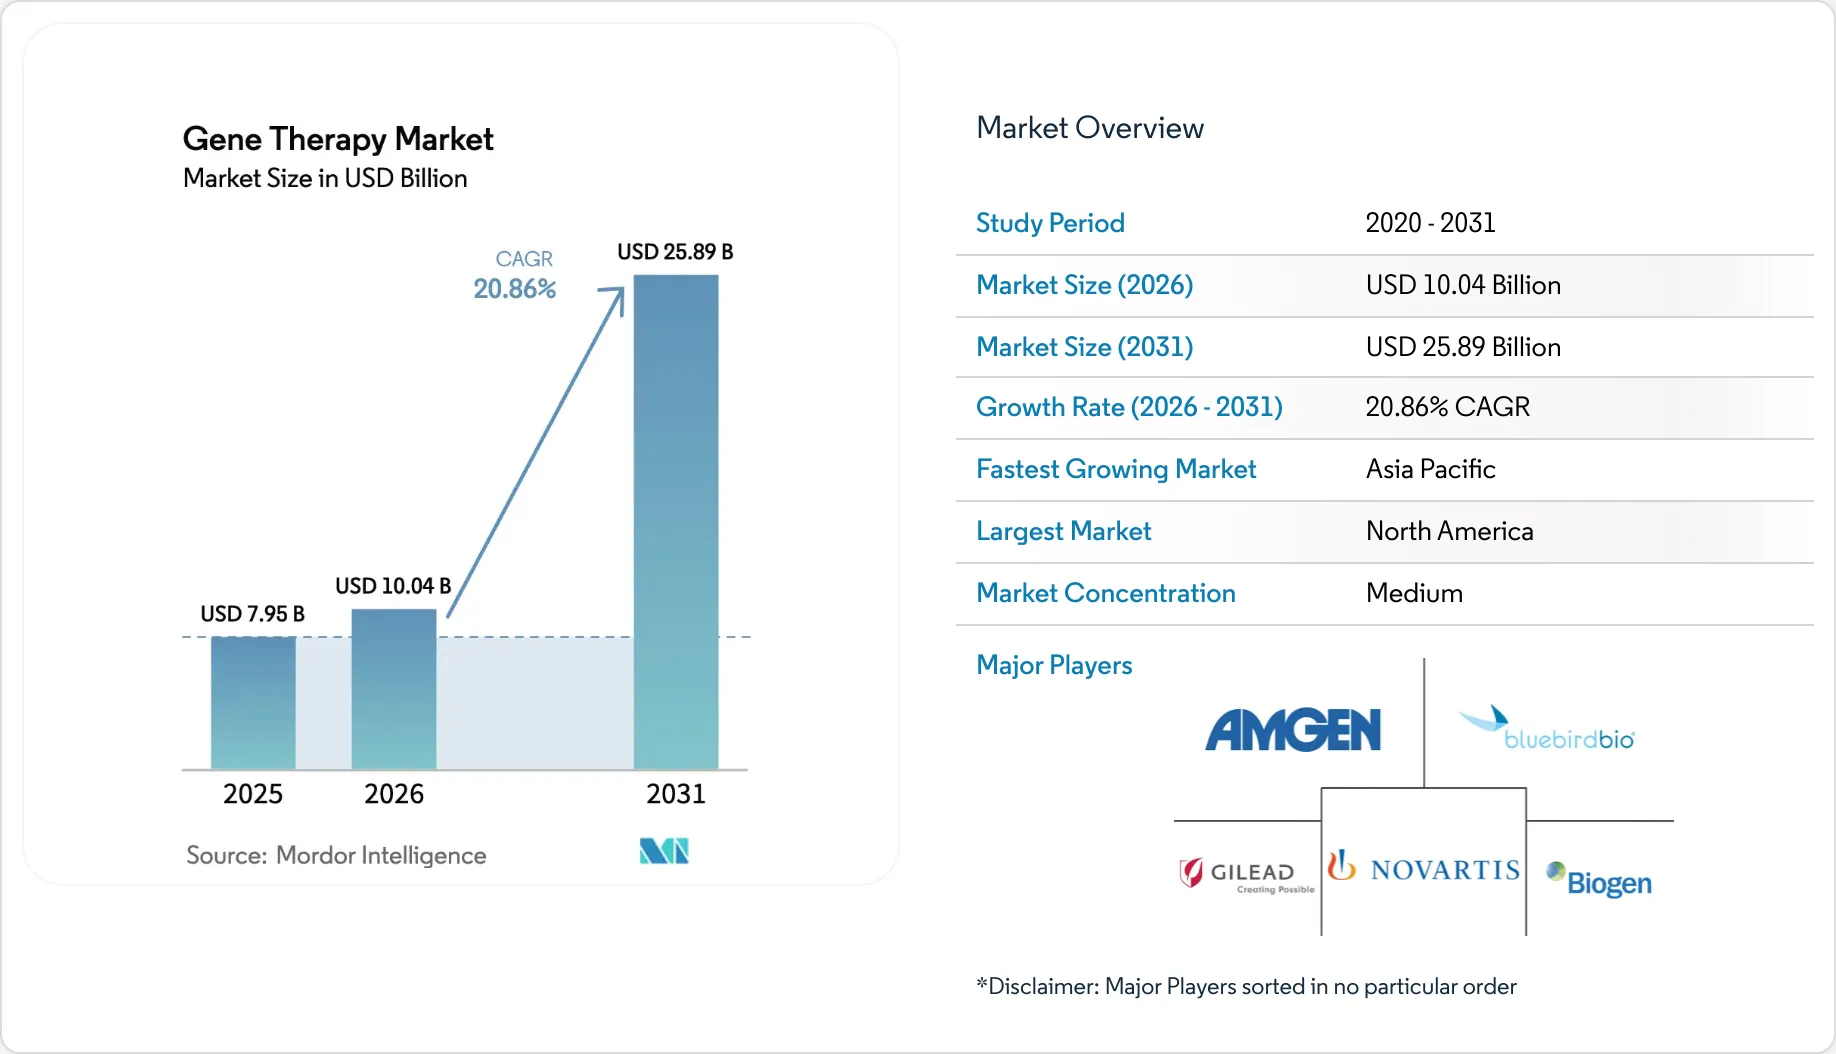
Gene Therapy Market Size and ShareMarket OverviewStudy Period | 2020 - 2031 |
Market Size (2026) | USD 10.04 Billion |
Market Size (2031) | USD 25.89 Billion |
Growth Rate (2026 - 2031) | 20.86 % |
Fastest Growing Market | Asia Pacific |
Largest Market | North America |
Market Concentration | Medium |
Major Players*Disclaimer: Major Players sorted in no particular order
Image © Vijeron Intelligence. Reuse requires attribution under CC BY 4.0.
Image © Vijeron Intelligence. Reuse requires attribution under CC BY 4.0.
Section 2
Gene Therapy Market Analysis by Vijeron IntelligenceThe Gene Therapy Market size was valued at USD 7.95 billion in 2025 and is estimated to grow from USD 10.04 billion in 2026 to reach USD 25.89 billion by 2031, at a CAGR of 20.86% during the forecast period (2026-2031).
Accelerating one-time curative approvals, outcomes-based reimbursement models, and platform manufacturing efficiencies are transforming gene therapy from an experimental modality into a commercially scalable treatment class. Payer reluctance is easing as real-world evidence shows durable benefit, while standardized adeno-associated virus (AAV) and lentivirus (LV) processes are compressing production timelines by up to 50%, supporting higher batch success rates. Venture investors have shifted toward late-stage assets, reducing development risk and directing capital toward assets with nearer-term revenue potential. Meanwhile, non-viral lipid nanoparticle systems are maturing, setting up cross-platform competition that could further expand therapeutic reach. Intellectual property competition around engineered capsids and editing payloads is intensifying, as more than 500 novel AAV capsid patents were filed between 2020 and 2024, signaling a decisive scramble for delivery leadership.
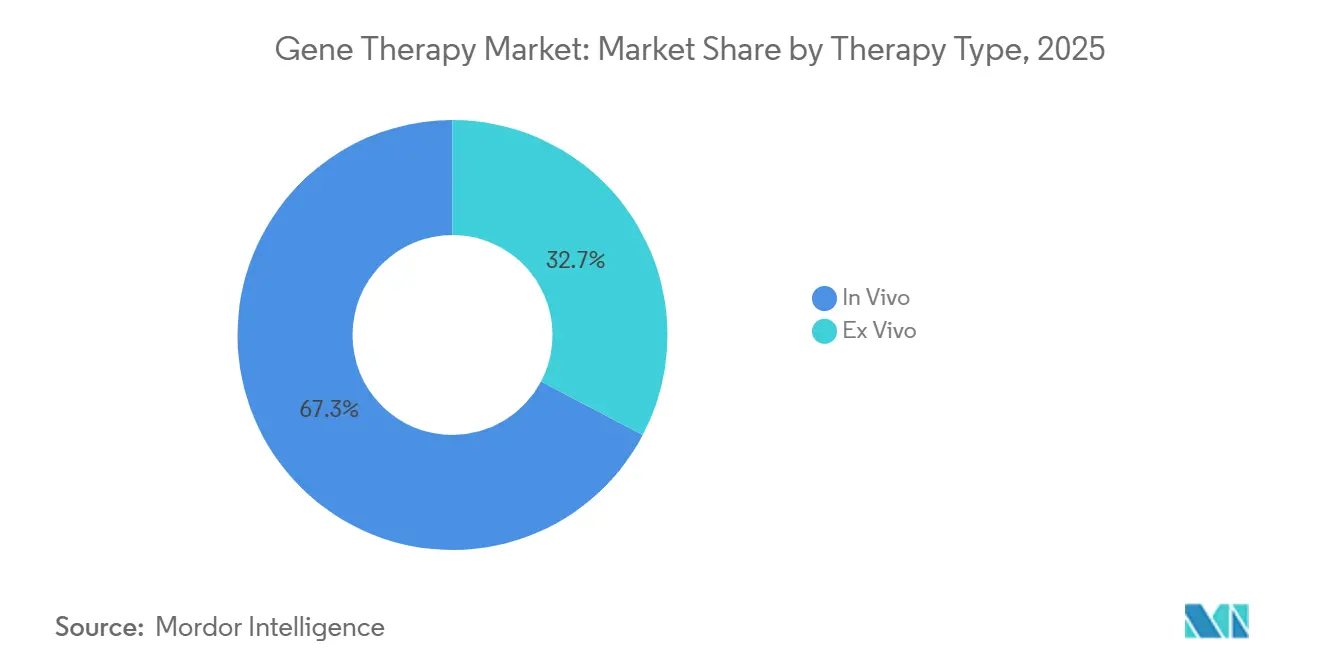
Key Report Takeaways* By therapy type, in vivo approaches led with 67.31% revenue share in 2025, while ex vivo posted the fastest 21.97% CAGR outlook to 2031.
- By vector type, viral vectors commanded 74.83% of the gene therapy market share in 2025; however, non-viral systems are forecasted to expand at a 23.41% CAGR through 2031.
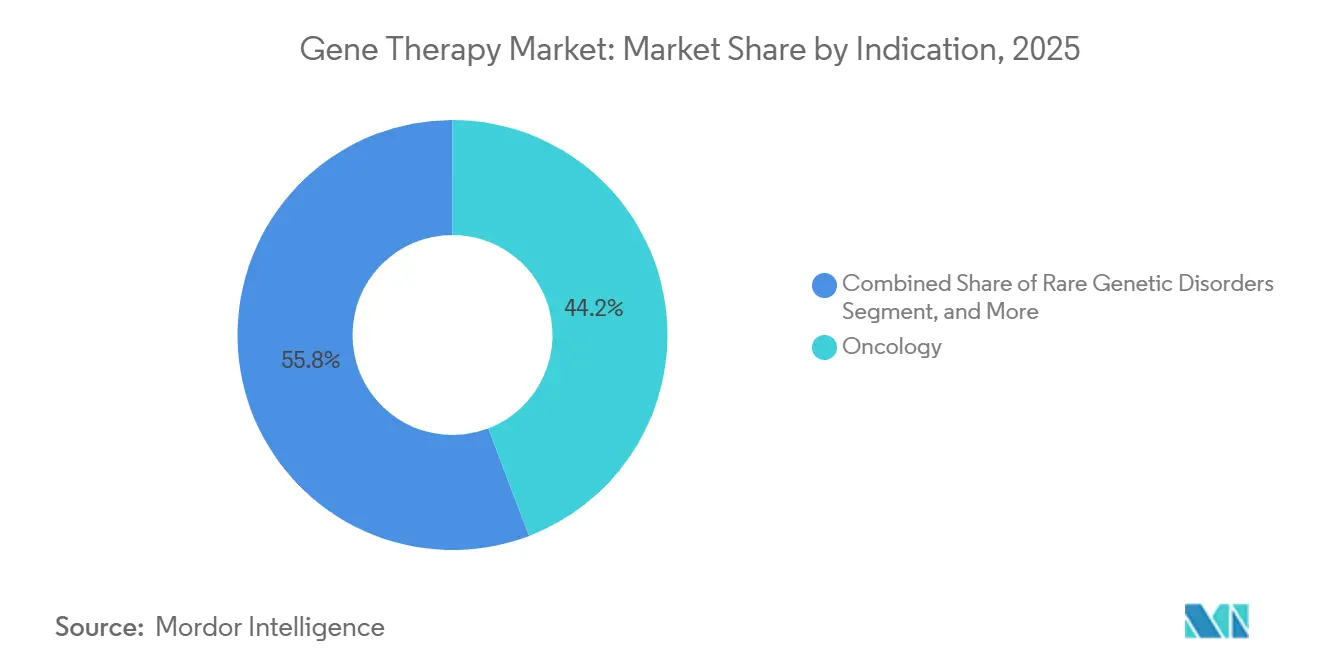
- By indication, oncology generated 44.15% of 2025 revenue, whereas neurology applications are advancing at a 22.71% CAGR toward 2031.
- By delivery method, systemic administration accounted for 46.36% of 2025 sales, while localized routes are projected to grow at 25.18% through 2031.
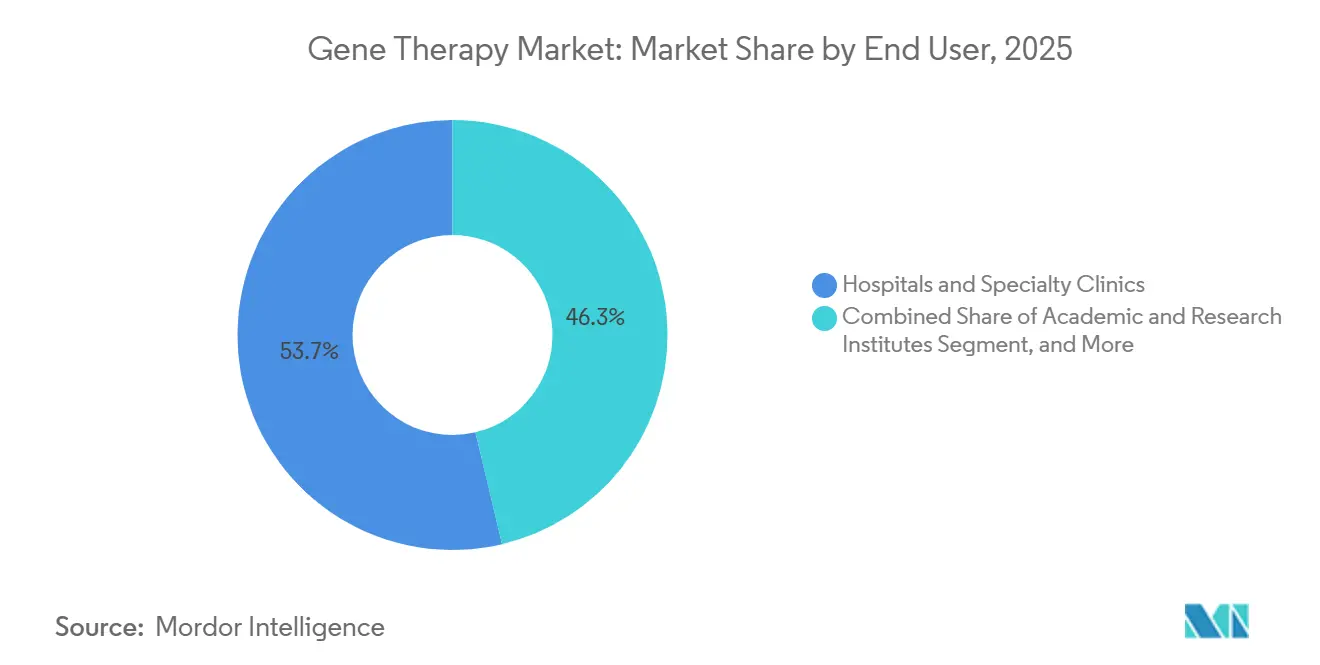
- By end user, hospitals and specialty clinics accounted for 53.66% of revenue in 2025, while academic and research institutes are on track for a 26.64% CAGR through 2031.
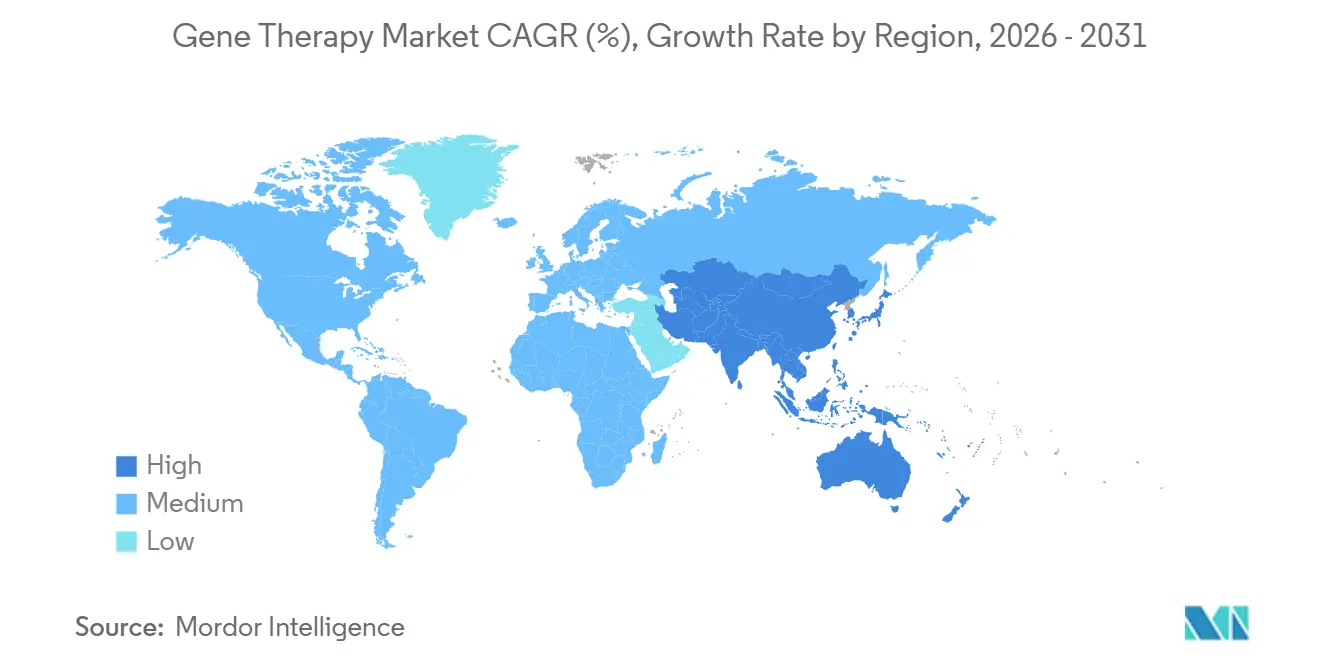
- By geography, North America retained 41.36% of 2025 value, yet Asia-Pacific is poised for the highest 28.78% CAGR between 2026 and 2031.
Note: Market size and forecast figures in this report are generated using Vijeron Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Section 3
Market Trends and InsightsDrivers Impact Analysis of Gene Therapy Market*Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
Surge in Approvals of One-Shot Curative Therapies | +5.2% | Global, with North America and Europe leading | Medium term (2-4 years) |
Expanding Reimbursement for Ultra-Rare Disorders | +4.8% | North America, selective EU markets, emerging in Asia-Pacific | Medium term (2-4 years) |
Manufacturing Platform Standardisation (AAV & LV) | +4.1% | Global, concentrated in North America, Europe, and East Asia manufacturing hubs | Long term (≥ 4 years) |
Growing Venture & SPAC Funding Pipelines | +2.9% | North America and Europe, spillover to Israel and Singapore | Short term (≤ 2 years) |
CRISPR-Based In Vivo Editing Breakthroughs | +3.6% | Global, with clinical leadership in US, UK, and Switzerland | Medium term (2-4 years) |
Growing Inclusion of Rare-Disease Gene Therapies | +2.7% | Global, with strong regulatory support in North America, EU, and Japan | Medium term (2-4 years) |
Source: Vijeron Intelligence |
Surge in Approvals of One-Shot Curative TherapiesRegulators accelerated timelines in 2024-2025, clearing therapies such as Waskyra for Wiskott-Aldrich syndrome, Itvisma for spinal muscular atrophy, and Casgevy for sickle-cell disease under priority pathways.[1]U.S. Food and Drug Administration, “Approved Cellular and Gene Therapy Products,” fda.gov Clinical datasets underpinning these decisions demonstrate durable efficacy, with Casgevy keeping 93.5% of patients crisis-free over 12 months and Beqvez maintaining greater than 40% factor IX activity, thereby eliminating the need for hemophilia B prophylaxis. Payers acknowledge that one-time interventions can offset decades of chronic-care costs, triggering recalibrated budget models. Japan’s Sakigake pathway extension to gene therapy underscores the broader alignment in the Asia-Pacific region, reinforcing the global shift toward curative paradigms.
Expanding Reimbursement for Ultra-Rare DisordersOutcomes-based models now govern roughly 40% of U.S. commercial contracts, and CMS’s Cell and Gene Therapy Access Model covers 35 Medicaid programs, sharing financial risk with manufacturers.[2]Centers for Medicare & Medicaid Services, “Cell and Gene Therapy Access Model,” cms.gov Europe remains fragmented but is experimenting with installment payments, as France’s HAS spreads Zolgensma’s USD 2.1 million cost over five years. U.S. forecasts from the Congressional Budget Office indicate that sickle-cell therapies alone could generate USD 1.8 billion in annual Medicaid expenditures by 2028, prompting legislatures to develop pooled-purchase solutions. Registry data from real-world Zolgensma use indicate that 95% of treated children retain motor milestones at a five-year follow-up, reinforcing the value of pay-for-performance schemes.
Manufacturing Platform Standardization (AAV & LV)Lonza’s USD 1 billion Portsmouth facility and Catalent’s USD 675 million Harmans expansion are purpose-built for modular bioreactors ranging from 50 to 2,000 liters, which can pivot across multiple campaigns without requiring process transfer.[3]Lonza, “Lonza Announces USD1 Billion Portsmouth Facility,” lonza.com MilliporeSigma’s AAV-MAX system cuts upstream costs in half by eliminating adherent culture requirements, while Viralgen’s Pro10™ platform reduced batch-failure rates to below 5% across 1,500 runs. Samsung Biologics is adding Asia-Pacific’s first large-scale AAV plant, foreshadowing a geographically diversified supply chain. The 2024 joint FDA-EMA guidance on AAV analytics harmonizes release testing, directly reducing duplicated validation costs.
Growing Venture & SPAC Funding PipelinesVenture investors deployed USD 3.2 billion in 2024, with 70% of the funds allocated to Phase 2+ assets, indicating a higher demand for clinical de-risking. Prime Medicine’s USD 315 million Series C and Tome Biosciences’ USD 213 million Series A exemplify oversized bets on differentiated editing. SPAC activity declined in 2024-2025 as public markets prioritized revenue visibility; however, corporate venture arms such as Novo Holdings and Takeda Ventures remained active, bringing regulatory and CMC expertise alongside capital.
Restraints Impact Analysis of Gene Therapy Market*Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
High COGS and Six-Figure Price Backlash | -3.7% | Global, acute in Europe and emerging markets | Medium term (2-4 years) |
Complex Long-Term Safety Monitoring Mandates | -2.4% | Global, most stringent in North America and EU | Long term (≥ 4 years) |
Global Viral-Vector Capacity Bottlenecks | -2.8% | Global, concentrated impact in North America and Europe manufacturing hubs | Short term (≤ 2 years) |
Emerging Patent Thickets on Gene-Editing Payloads | -1.9% | Global, most acute in North America and Europe with spillover to Asia-Pacific | Medium term (2-4 years) |
Source: Vijeron Intelligence |
High COGS and Six-Figure Price BacklashViral-vector batches cost USD 500,000–2 million, driving list prices such as Lenmeldy’s USD 4.25 million, provoking U.S. Senate Finance hearings and NICE rejections under GBP 100,000/QALY thresholds. Yield variability ranging from 30% to 70% per campaign forces overproduction and write-offs. Continuous-manufacturing pilots by Resilience and Fujifilm Diosynth promise a 50% cost reduction but will not reach commercial scale meaningfully before 2027. Bluebird’s 2024 withdrawal of Zynteglo from the EU, following reimbursement failures, illustrates the existential risk posed by HTA bodies' reluctance to accept prices.
Complex Long-Term Safety Monitoring MandatesThe FDA requires 15-year patient surveillance for integrating vectors, including annual to triennial visits, plus hematologic malignancy screening, which costs smaller firms USD 5-10 million per year. EMA’s risk plans further extend the burden until full marketing authorization is achieved, thereby delaying breakeven timelines. Zolgensma’s REMS and Lyfgenia’s leukemia monitoring illustrate the multi-decade post-market commitments that strain single-asset developers. ASGCT’s voluntary registry initiative could centralize data but lacks universal participation.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Section 4
Gene Therapy Market Segment AnalysisBy Therapy Type:Ex Vivo Platforms Accelerate on Allogeneic PotentialThe gene therapy market size for in vivo approaches accounted for 67.31% of the revenue in 2025, reflecting its dominance in liver and systemic applications. Ex vivo therapies accounted for the remainder but are projected to outpace the market at a 21.97% CAGR, fueled by CRISPR-enabled allogeneic CAR-T designs that bypass autologous bottlenecks. Allogene and CRISPR Therapeutics advanced Phase 2 trials in 2024, demonstrating rapid 14-day vein-to-vein workflows. FDA draft CMC guidance clarified batch testing and donor-screening criteria, reducing regulatory ambiguity.
Adoption hinges on cost-effective point-of-care manufacturing. Lonza and Miltenyi Biotec piloted mobile clean rooms in 2024 that slash per-dose costs by 40%, positioning hospital sites as micro-factories. In vivo programs still encounter immunogenicity; up to 50% of candidates possess neutralizing antibodies, prompting the development of engineered capsids. Neurodegenerative disorders, led by uniQure’s AMT-130, show promise where ex vivo is impractical, keeping therapeutic diversity high.
Image © Vijeron Intelligence. Reuse requires attribution under CC BY 4.0. By Vector Type:Non-Viral Systems Close Efficacy GapsViral platforms generated 74.83% of 2025 revenue, anchored by AAV’s hepatocyte tropism and LV’s integration for hematologic disorders. Non-viral vectors are expected to expand at a 23.41% CAGR, narrowing the gap through optimized lipid nanoparticles that delivered 40%-60% editing rates in Moderna and BioNTech preclinical models. MaxCyte’s electroporation supports 50+ clinical trials, offering transient expression suitable for ex vivo editing.
Within viral categories, engineered AAV-PHP.B capsids entered first-in-human studies for Parkinson’s disease, highlighting next-generation tropism for CNS delivery. Touchlight’s enzymatic DNA competes as a plasmid alternative that avoids bacterial contaminants, broadening non-viral options. The FDA non-viral guidance standardized quality expectations, aligning oversight with irreversible editing risk rather than vector category.
By Indication:Neurology Gains MomentumOncology’s 44.15% contribution in 2025 is expected to continue as CAR-Ts advance into earlier-line settings, with Carvykti achieving 73% complete responses in multiple myeloma. However, neurology indications are forecast to grow at a 22.71% CAGR as intrathecal AAV delivery bypasses the blood-brain barrier. Successes include uniQure’s 79% huntingtin-protein knockdown and Neurocrine’s GBA1 Parkinson’s program. Ophthalmology remains a profitable niche thanks to the eye’s immune privilege, with Luxturna’s five-year durability data reinforcing payer confidence.
Rare genetic disorders continue to receive regulatory priority, with Waskyra and Itvisma obtaining approvals in 2025. Hematology stays competitive; eight hemophilia assets in late-stage development may squeeze pricing power, motivating differentiation through lower vector doses or outpatient administration settings.
Image © Vijeron Intelligence. Reuse requires attribution under CC BY 4.0. By Delivery Method:Localized Administration EscalatesSystemic infusion represented 46.36% of revenue in 2025, but localized delivery is on a 25.18% CAGR trajectory. Intrathecal approaches require one-tenth the vector dose for spinal muscular atrophy, lowering immunogenic risk. Subretinal surgical protocols standardized by Luxturna are now in operation across 150 U.S. centers, ensuring reproducible outcomes. Intravitreal delivery is under evaluation for wet AMD, potentially reducing monthly anti-VEGF injections to annual schedules. Systemic regimens still dominate hepatocyte editing but face exclusion due to the development of neutralizing antibodies, prompting ongoing redesign of the capsid.
By End User:Academic Institutes Propel Early InnovationHospitals and specialty clinics captured 53.66% of 2025 revenue, functioning as commercial administration hubs equipped with GMP apheresis suites. Academic institutes, holding a smaller base, show a 26.64% CAGR, as 60% of active trials originate from investigator-initiated protocols. European Reference Networks exemplify cross-border harmonization, pooling cases of rare diseases for higher-powered studies. Hospital investments such as Massachusetts General’s USD 50 million cell-processing plant enhance domestic manufacturing, supporting decentralized point-of-care production.
Image © Vijeron Intelligence. Reuse requires attribution under CC BY 4.0.
Section 5
Geography AnalysisNorth America Gene Therapy MarketNorth America maintained 41.36% of 2025 revenue, supported by 45 new RMAT designations and the CMS Access Model easing Medicaid barriers. Capacity built by Lonza, Catalent, and Resilience totaled 1.2 million liters of bioreactors, cementing the region’s supply dominance. Outcomes-based contracts now cover 40% of U.S. therapies, as exemplified by Lyfgenia’s coverage for 100 million lives. Canada trails with only two approvals in 2024, due to protracted provincial reimbursement negotiations.
APAC Gene Therapy MarketThe Asia-Pacific region, projected to grow at a 28.78% CAGR, is driven by China’s NMPA approvals of Roctavian and Yescarta, as well as over 200 active clinical trials. WuXi AppTec’s plasmid facility and Samsung’s AAV plant diversify global manufacturing. Japan’s PMDA extended Sakigake's fast-track to gene therapy, and India green-lit its first CAR-T at one-tenth the U.S. price, showcasing cost innovation. Australia approved Casgevy but faces delays in reimbursement.
EMEA and South America Gene Therapy MarketEurope grapples with fragmented HTA systems. Bluebird’s Zynteglo exit following reimbursement failures exemplifies the commercial risk associated with EMA approval. Germany’s IQWiG positive Hemgenix assessment and France’s installment payments for Zolgensma are isolated wins. EUnetHTA’s 2025 joint assessments aim to harmonize evidence, yet national payers still control pricing. The Middle East & Africa, as well as South America, remain nascent but are developing regulatory frameworks, with the UAE and Brazil approving select therapies for compassionate or public hospital use.
Image © Vijeron Intelligence. Reuse requires attribution under CC BY 4.0.
Section 6
Regulatory LandscapeRegulatory oversight for gene therapies continues to tighten around quality, safety, and comparability, while also introducing mechanisms intended to accelerate development in smaller patient populations. In the United States, the FDA has expanded its suite of cell and gene therapy guidances, including a September 2025 draft on innovative clinical trial designs for small populations and a June 2026 draft focused on platform knowledge and CMC flexibilities for genome editing and related modalities. The stated intent is to reduce submission burden while maintaining expectations around product control.
In Europe, gene therapies remain regulated as Advanced Therapy Medicinal Products (ATMPs) under EMA processes, with ongoing CAT procedures and quarterly updates in 2026 reflecting active evaluations and authorizations (for example, EU-level actions around products such as Adstiladrin and Itvisma during 2026). At the same time, EU institutions advanced legislative work on a proposed European Biotech Act during 2025-2026. The proposal is framed to strengthen biotech and biomanufacturing competitiveness and to revisit parts of the ATMP framework, including Regulation (EC) No 1394/2007, which is relevant for sponsors managing classification, evidence expectations, and cross-country access planning.
Section 7
Value Chain AnalysisThe gene therapy value chain runs from discovery and vector engineering through translational and preclinical development, clinical operations, GMP manufacturing, quality control and release testing, distribution logistics (including cold chain and chain-of-custody systems), and administration through hospitals and specialty clinics. Inputs and enabling services include plasmid DNA, cell banks, single-use consumables, analytical testing, CRO support, and specialized CDMOs for viral vectors (AAV and lentivirus) as well as emerging non-viral systems, with downstream access increasingly shaped by payer contracts and long-term follow-up infrastructure.
Manufacturing is the most capacity- and cost-sensitive segment, reflecting complex upstream production, variable yields, and labor-intensive operations. This increases reliance on experienced CDMOs and specialized raw materials. Regulatory moves in 2026 reinforce standardization and reuse of platform knowledge, including a flexible approach to CMC oversight (such as flexibility around certain release specifications informed by post-approval experience) and draft guidance to leverage existing public platform knowledge for CMC submissions. Together, these changes support a chain-wide shift toward closed-system automation, standardized analytics, and hybrid operating models that combine centralized scale manufacturing with point-of-care capabilities for select ex vivo workflows.
Section 8
Competitive Landscape
The gene therapy industry remains moderately fragmented; Novartis, Gilead, and Bristol Myers Squibb together generated high value from CAR-T franchises in 2024. Vertically integrated majors continue to expand their plants, whereas platform biotechs license capsids or editors more broadly. Pfizer’s Beam takeover and Novartis’s Voyager acquisition highlight consolidation around differentiated delivery technologies.
Competitive thrust in CNS disorders involves fewer than 10 late-stage candidates, leaving unmet-need white space for innovators with BBB-penetrating capsids. Allogeneic CAR-T players, such as CRISPR Therapeutics, Allogene, and Cellectis, could disrupt autologous incumbents if Phase 3 data confirm comparable efficacy and safety. Patents drive strategic alliances; the over 500 AAV capsid filings since 2020 pressure entrants to negotiate licenses or risk litigation.
Non-viral specialists Moderna, BioNTech, and Intellia leverage lipid nanoparticle know-how from mRNA vaccines to deliver editing payloads, achieving 40%-60% liver editing in preclinical models. Technology differentiation, particularly in terms of promoter selection, payload size, and organ tropism, will likely dictate deal flow and valuation more than sheer pipeline count.
Gene Therapy Industry Leaders* Amgen Inc.
- Novartis AG
- bluebird bio Inc.
- Biogen Inc.
- Gilead Sciences Inc.
- *Disclaimer: Major Players sorted in no particular order
Image © Vijeron Intelligence. Reuse requires attribution under CC BY 4.0.Gene Therapy Market Companies Covered in this Report* Amgen
- Beam Therapeutics
- bluebird bio Inc.
- Bristol-Myers Squibb
- Biogen
- CRISPR Therapeutic
- Editas Medicine
- Freeline Therapeutics
- Gilead Sciences
- Intellia Therapeutics
- LogicBio Therapeutics
- MeiraGTx
- Mustang Bio
- Novartis
- Orchard Therapeutics
- Passage Bio
- Pfizer
- Regenxbio
- Sangamo Therapeutics
- Sarepta Therapeutics
- Spark Therapeutics
- Takeda Pharmaceuticals
- uniQure N.V.
- ViGeneron
Section 9
Market Opportunities and Future Outlook
A near-term opportunity is in industrializing viral-vector supply through standardized, higher-productivity platforms and qualified commercial facilities that reduce cycle time and batch failure risk. In March 2026, SK pharmteco completed cGMP qualification for its commercial-scale viral vector site in Corbeil-Essonnes, France (5,000 square meters, 12 single-use bioreactors spanning 50 L to 1,000 L and 5,000 L total upstream capacity), and in June 2026 it launched the SKyvec viral vector platform, positioned around five- to six-fold AAV productivity gains and integrated development across AAV, lenti, and adeno vectors. CDMO-led capacity access is also expanding via partnerships, including the June 2026 Forge Biologics and Skylark Bio agreement that leverages Forge’s Columbus, Ohio facility footprint for AAV development and cGMP manufacturing.
Another opportunity is reducing development friction through clearer, risk-adapted CMC expectations and more consistent potency strategies, which helps address comparability and scale-up bottlenecks across indications and geographies. The FDA’s 2026 communications on flexible CMC oversight, alongside industry work such as BioPhorum’s 2026 potency strategy roadmap for in vivo gene therapy, creates room for sponsors to invest in phase-appropriate assays and platform analytics that can carry across programs. Manufacturing investment in Asia also continues to widen the supply base, including AGC’s planned 2026 launch of expanded facilities in Yokohama for mRNA pharmaceuticals and gene/cell therapies (backed by METI support), which supports more distributed development-to-commercial pathways for global sponsors.
Section 10
Recent Industry Developments in Gene Therapy Market* June 2026: SK pharmteco launched the SKyvec viral vector platform, positioning it as an integrated development and manufacturing approach across AAV, lentiviral, and adenoviral vectors with multi-fold AAV productivity gains. The platform launch strengthens CDMO-led supply options for sponsors looking for faster tech transfer from clinical to commercial production. It also increases competitive pressure on incumbent viral-vector manufacturing offerings by emphasizing standardized, higher-output processes.
- May 2025: Japan’s MHLW approved Sarepta Therapeutics’ ELEVIDYS (delandistrogene moxeparvovec-rokl) under conditional approval for Duchenne muscular dystrophy in children aged 3-7 who meet antibody and genotype criteria, supported by Phase 3 EMBARK data. Commercialization is handled by Chugai and Roche in Japan, extending access for a high-profile AAV therapy in a major Asia-Pacific market. The approval adds momentum to regional fast-track pathways and expands the addressable treated population in pediatric neuromuscular disease.
- October 2024: New York State launched the next phase of New York BioGenesis Park, a USD 430 million cell and gene therapy hub on Long Island backed by a USD 150 million state investment. The project targets research, manufacturing, and commercialization capacity, expanding local infrastructure for advanced therapies. It also reinforces the role of public-sector funding in building regional ecosystems that attract developers, CDMOs, and clinical networks.
Section 11
Table of Contents for Gene Therapy Industry Report1. Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
- Research Methodology
- Executive Summary
- Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers* 4.2.1 Surge in Approvals of One-Shot Curative Therapies
- 4.2.2 Expanding Reimbursement for Ultra-Rare Disorders
- 4.2.3 Manufacturing Platform Standardisation (AAV & LV)
- 4.2.4 Growing Venture & SPAC Funding Pipelines
- 4.2.5 CRISPR-Based in Vivo Editing Breakthroughs
- 4.2.6 Growing Inclusion of Rare-Disease Gene Therapies
- 4.3 Market Restraints* 4.3.1 High COGS And Six-Figure Price Backlash
- 4.3.2 Complex Long-Term Safety Monitoring Mandates
- 4.3.3 Global Viral-Vector Capacity Bottlenecks
- 4.3.4 Emerging Patent Thickets on Gene-Editing Payloads
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter’s Five Forces Analysis* 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- Market Size & Growth Forecasts
- 5.1 By Therapy Type* 5.1.1 In Vivo
- 5.1.2 Ex Vivo
- 5.2 By Vector Type* 5.2.1 Viral Vectors
- 5.2.1.1 Adeno-Associated Virus
- 5.2.1.2 Lentivirus
- 5.2.1.3 Adenovirus
- 5.2.1.4 Retrovirus & γ-Retrovirus
- 5.2.1.5 Other Viral
- 5.2.2 Non-viral Vectors
- 5.3 By Indication* 5.3.1 Oncology
- 5.3.2 Rare Genetic Disorders
- 5.3.3 Ophthalmology
- 5.3.4 Hematology
- 5.3.5 Neurology
- 5.3.6 Cardiovascular & Others
- 5.4 By Delivery Method* 5.4.1 Systemic Administration
- 5.4.2 Localised Administration
- 5.5 By End User* 5.5.1 Hospitals & Specialty Clinics
- 5.5.2 Academic & Research Institutes
- 5.5.3 Other End Users
- 5.6 By Geography* 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 India
- 5.6.3.4 Australia
- 5.6.3.5 South Korea
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 Middle East & Africa
- 5.6.4.1 GCC
- 5.6.4.2 South Africa
- 5.6.4.3 Rest of Middle East & Africa
- 5.6.5 South America
- 5.6.5.1 Brazil
- 5.6.5.2 Argentina
- 5.6.5.3 Rest of South America
- Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market-level Overview, Core Segments, Financials, Strategic Information, Market Rank/Share, Products & Services, Recent Developments)* 6.3.1 Amgen Inc.
- 6.3.2 Beam Therapeutics
- 6.3.3 bluebird bio Inc.
- 6.3.4 Bristol Myers Squibb
- 6.3.5 Biogen Inc.
- 6.3.6 CRISPR Therapeutics
- 6.3.7 Editas Medicine
- 6.3.8 Freeline Therapeutics
- 6.3.9 Gilead Sciences Inc.
- 6.3.10 Intellia Therapeutics
- 6.3.11 LogicBio Therapeutics
- 6.3.12 MeiraGTx
- 6.3.13 Mustang Bio
- 6.3.14 Novartis AG
- 6.3.15 Orchard Therapeutics
- 6.3.16 Passage Bio
- 6.3.17 Pfizer Inc.
- 6.3.18 Regenxbio
- 6.3.19 Sangamo Therapeutics
- 6.3.20 Sarepta Therapeutics
- 6.3.21 Spark Therapeutics
- 6.3.22 Takeda Pharmaceutical
- 6.3.23 uniQure N.V.
- 6.3.24 ViGeneron
- Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment
Section 12
Gene Therapy Market Report Scope and Research MethodologyMarket Definition and CoverageFor this study, the gene therapy market covers revenues earned from therapies that add, silence, or edit genetic material in a patient to treat or prevent disease. It includes products delivered using viral and non-viral vectors across major geographies.
Scope exclusions: We do not count treatments that only expand or reinfuse manipulated cells without direct genomic alteration.
Segments Covered in This Report By Therapy Type In Vivo
- Ex Vivo
- By Vector Type Viral Vectors Adeno-Associated Virus
- Lentivirus
- Adenovirus
- Retrovirus & γ-Retrovirus
- Other Viral
- Non-viral Vectors
- By Indication* Oncology
- Rare Genetic Disorders
- Ophthalmology
- Hematology
- Neurology
- Cardiovascular & Others
- By Delivery Method* Systemic Administration
- Localised Administration
- By End User* Hospitals & Specialty Clinics
- Academic & Research Institutes
- Other End Users
- By Geography North America United States
- Canada
- Mexico
- Europe* Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific* China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa* GCC
- South Africa
- Rest of Middle East & Africa
- South America* Brazil
- Argentina
- Rest of South America
Data Sources, Market Sizing, and ValidationDesk Research
Desk work starts with building a clean view of demand and supply signals that can be checked over time. We used public sources such as the FDA and NIH for approval and pipeline signals, the WHO and CDC for disease prevalence context, and OECD health statistics for system-level spend and access indicators.
The model is then supported with company filings, investor presentations, peer-reviewed journals, and reputable press coverage to confirm launch timing, therapy positioning, and broad pricing direction. Where needed, we also used paid subscriptions for company financials and intelligence, patent databases, and shipment-level import and export data to sanity-check manufacturing footprint changes and cross-border movement of critical inputs. These sources are illustrative and not exhaustive, since many additional references were reviewed for data collection, validation, and clarification.
Primary Interviews and Surveys
Primary work was used to convert desk signals into practical sizing assumptions, especially where public data is incomplete or reported with time lags. We spoke with a mix of therapy developers, vector and CDMO-side experts, treatment center stakeholders, and domain specialists across APAC, EMEA, and the Americas to test pricing ranges, uptake pacing, and regional access constraints.
Distribution of primary research fieldwork respondents
Company type | Respondent position | Region |
Top tier: 38% | CXOs: 16% | APAC: 42% |
Mid tier: 46% | Functional/Unit leaders: 26% | EMEA: 34% |
Smaller Players: 16% | Managers: 58% | Americas: 24% |
Market-Sizing & ForecastingSizing was built using top-down and bottom-up logic. The top-down view starts from an addressable treated-patient pool, then is rebuilt by indication-specific prevalence, eligibility, diagnosis rates, and expected access by region. Those volumes are paired with therapy pricing direction and the likely share of one-time versus repeat administrations to arrive at revenue.
To keep totals realistic, results are cross-checked with selective bottom-up approximations, such as roll-ups of known commercial launches, sampled ASP ranges from expert inputs, and capacity and utilization signals from vector and fill-finish activity where available. When the bottom-up view had gaps, for example early launches with limited disclosure, the model uses conservative ranges and then narrows them through follow-up checks with respondents.
For forecasting, scenario analysis is used alongside simple regression checks, because uptake depends on a few drivers moving together rather than one smooth historical curve. Inputs that most often shift the curve include approval cadence, label expansions, reimbursement and coverage timelines, manufacturing throughput constraints, and the pace of treatment center readiness. These inputs are validated through primary feedback before finalizing the curve.
Data Validation & Update CycleOutputs are validated through a sequence of checks that compare implied patient volumes and revenue per treated patient against independent signals, and then against what experts describe as feasible in real clinics. If a region shows an unusual jump, assumptions are revisited for pricing, access, or approval timing, and we re-contact sources when the variance cannot be explained with public evidence.
Before sign-off, the full model is reviewed in multiple analyst passes so inputs, formulas, and year-to-year transitions remain consistent. The report is refreshed annually, and interim updates are made when major approvals, safety actions, or step-changes in manufacturing capacity materially alter the forecast. A final pre-delivery review is then completed to reflect the latest information.
Vijeron Intelligence's Gene Therapy Market Size Compared Against Other Published EstimatesPublished market sizes for gene therapy can differ even when the topic name looks identical, since the counted revenue can shift based on what is considered a gene therapy, which years are treated as the base, and how early pipeline value is translated into near-term sales.
By tracking treated-patient eligibility and approval-timing assumptions, Vijeron Intelligence keeps the scope anchored to in-patient genetic modification therapies and excludes cell-only manipulations. This boundary is a common reason numbers move up or down between publications.
Benchmark comparison
Source | Market Size | Gaps in Research Methodology |
Vijeron Intelligence | USD 10.04 B (2026) | |
Industry Publisher A | USD 8.57 B (2024) | Uses an earlier base year and does not clearly state whether cell-only therapy revenues are removed, which can change the boundary and pull the total downward. |
Industry Publisher B | USD 11.40 B (2025) | Leans on broader segmentation and a different pricing and uptake progression, so faster adoption or higher ASP carry-through can inflate the near-term value. |
The spread in the table is mainly explained by timing and scope, and then by how quickly uptake is assumed to move after approvals. Our approach stays traceable because each step ties back to patient eligibility, access, and pricing logic, and the final totals are checked against practical supply and adoption constraints.
Section 13
Key Questions Answered in the ReportHow fast is the gene therapy market expected to grow through 2031? The sector is forecast to expand at a 20.86% CAGR, taking revenue from USD 10.04 billion in 2026 to USD 25.89 billion by 2031.
Which therapy type is projected to grow the quickest? Ex vivo therapies exhibit the fastest 21.97% CAGR outlook, driven by allogeneic CAR-T programs that eliminate the need for patient-specific manufacturing.
Why are payers beginning to cover high-priced gene therapies? Outcomes-based contracts and real-world evidence demonstrating durable benefit have persuaded payers that one-time costs can offset lifelong disease management expenses.
Which region is poised for the highest growth through 2031? Asia-Pacific leads with a projected 28.78% CAGR as China, Japan, and South Korea align regulatory pathways and build manufacturing capacity.
What limits broader adoption despite regulatory momentum? High manufacturing costs, long-term safety monitoring requirements, and viral-vector capacity constraints create cost and supply challenges that temper uptake.
Section 14
Related Reports Explore More Reports Find Latest Data onCell Therapy MarketChitosan Industry OverviewDNA Microarray Market SizeGene-Editing Tools For Non-Human Primates Industry OverviewGene Panel MarketGene Synthesis Industry OverviewGene Vector IndustryGenomics Market ForecastsHLA Typing Market SizePatient Derived Xenograft Models MarketSingle-Use Pump Industry Overview