Optical Imaging Market Size & Share Analysis - Growth Trends and Forecast (2026 - 2031)
Optical Imaging Market Size & Share Analysis - Growth Trends and Forecast (2026 - 2031)
Industry: Technology, Media & Telecom (TMT)
Source: https://www.mordorintelligence.com/industry-reports/optical-imaging-market-industry
Scraped Date: 2026-09-17
Key Market Estimates
| Variable | Value | Unit |
|---|
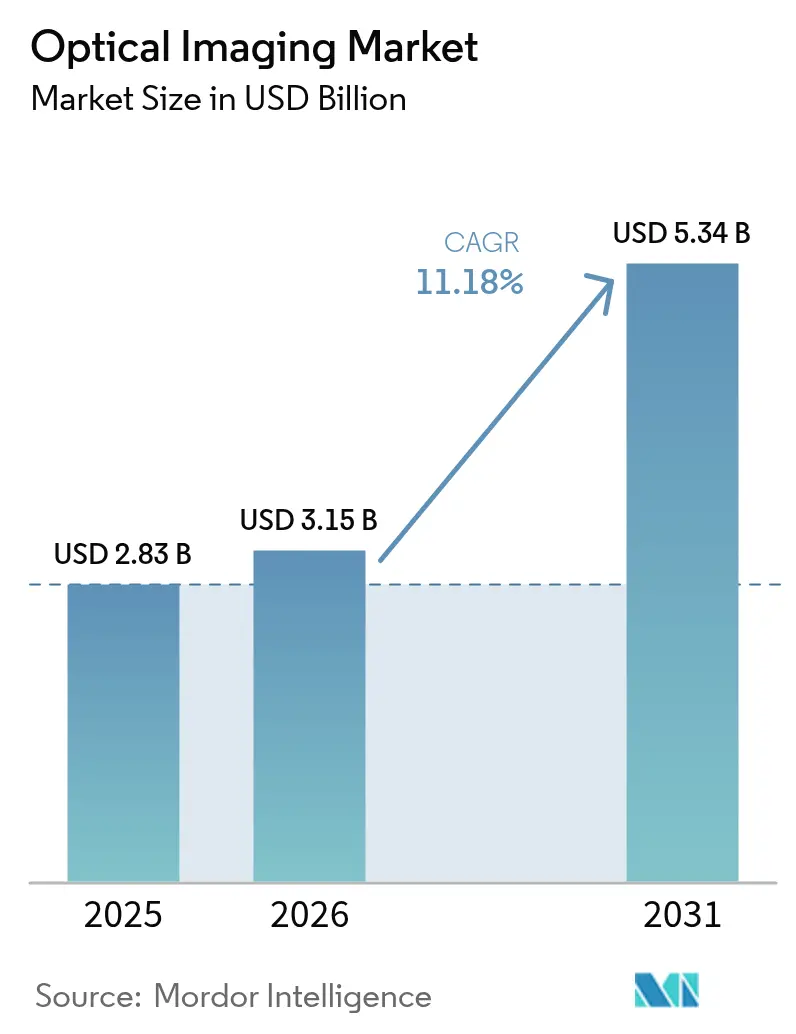
| Market Size (2026) | 3.15 | USD Billion |
|---|
| Market Size (2031) | 5.34 | USD Billion |
|---|
| Growth Rate (2026 - 2031) | 11.18 | PERCENT |
|---|
| Fastest Growing Market | Asia |
|---|
| Largest Market | North America |
|---|
| Market Concentration | Medium |
|---|
Section 1
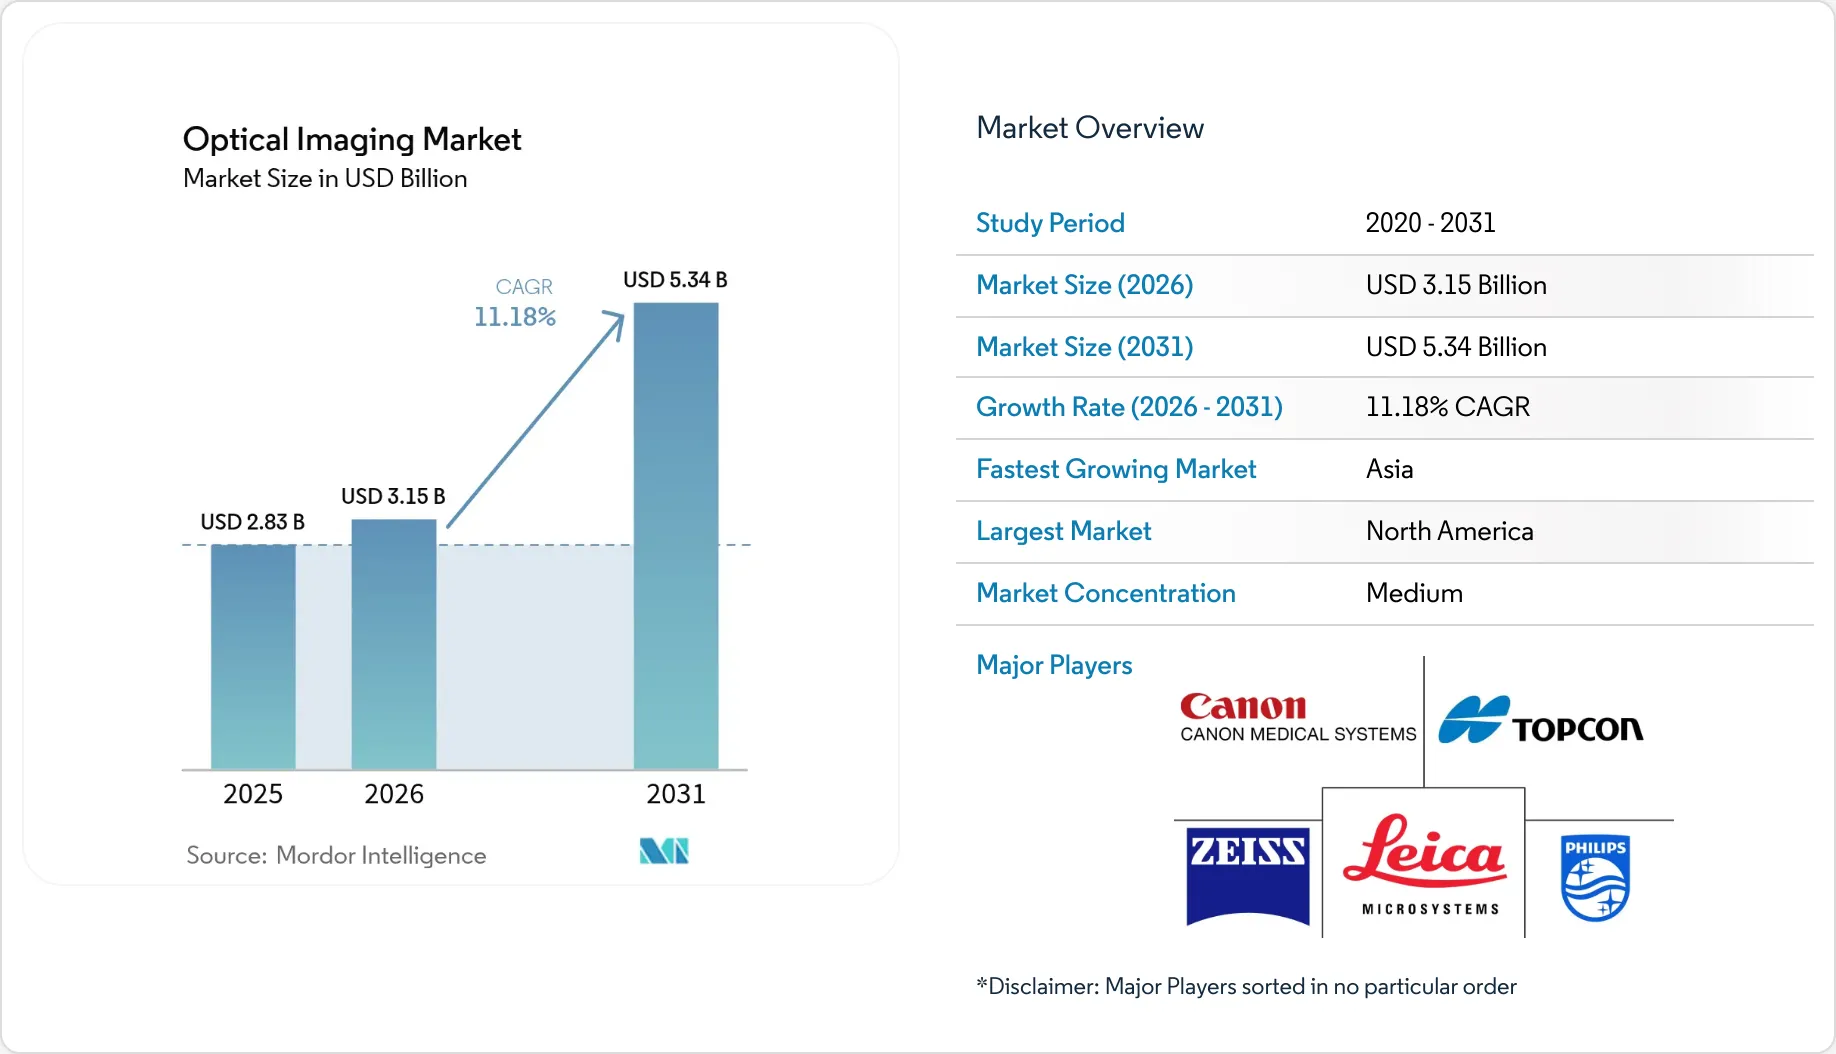
Optical Imaging Market Size and ShareMarket OverviewStudy Period | 2020 - 2031 |
Market Size (2026) | USD 3.15 Billion |
Market Size (2031) | USD 5.34 Billion |
Growth Rate (2026 - 2031) | 11.18 % |
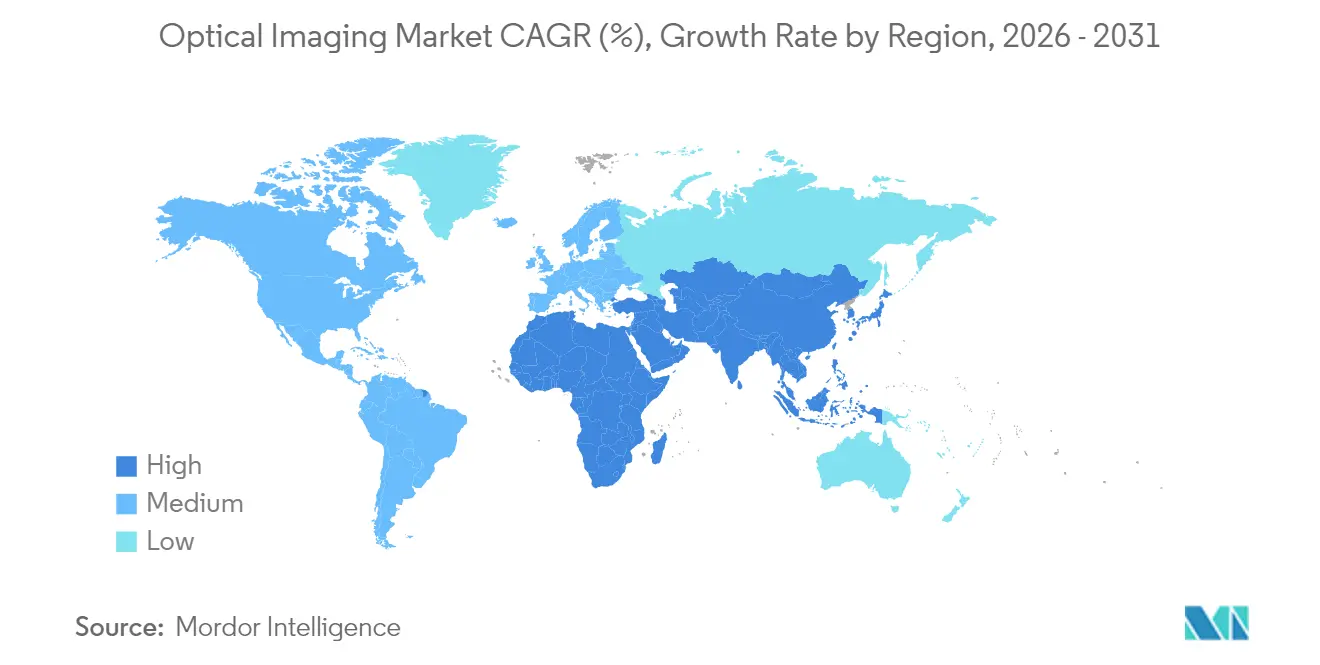
Fastest Growing Market | Asia |
Largest Market | North America |
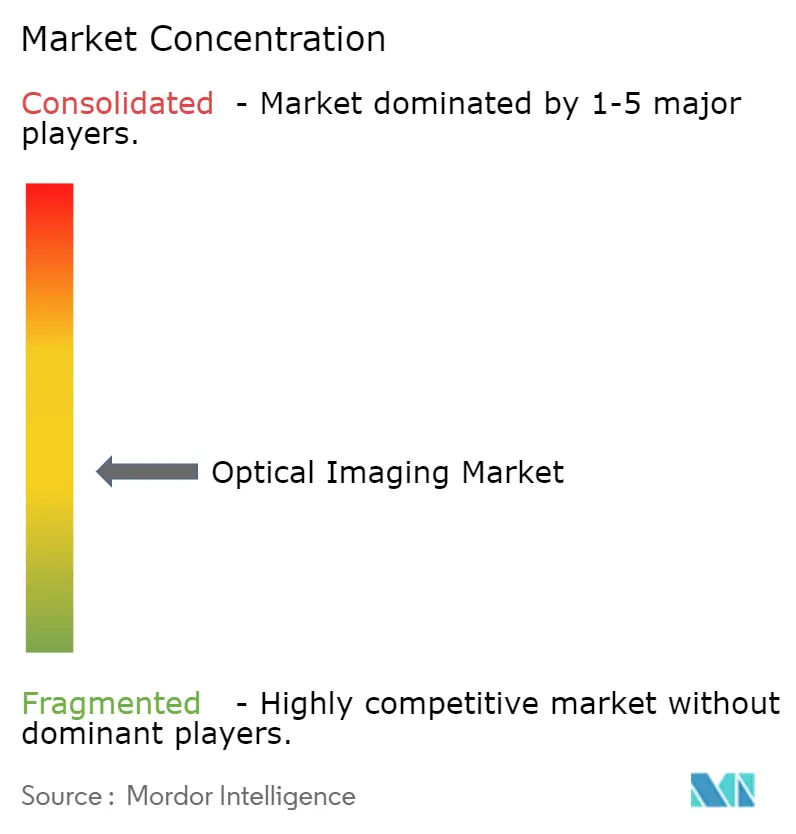
Market Concentration | Medium |
Major Players*Disclaimer: Major Players sorted in no particular order
Image © Vijeron Intelligence. Reuse requires attribution under CC BY 4.0.
Image © Vijeron Intelligence. Reuse requires attribution under CC BY 4.0.Select Another GeographyAsia[https://www.mordorintelligence.com/industry-reports/asia-pacific-optical-imaging-market-industry]Europe[https://www.mordorintelligence.com/industry-reports/europe-optical-imaging-market-industry]Middle East and Africa[https://www.mordorintelligence.com/industry-reports/middle-east-and-africa-optical-imaging-market-industry]North America[https://www.mordorintelligence.com/industry-reports/north-america-optical-imaging-market-industry]South America[https://www.mordorintelligence.com/industry-reports/south-america-optical-imaging-market]
Section 2
Optical Imaging Market Analysis by Vijeron IntelligenceThe optical imaging market size is expected to grow from USD 2.83 billion in 2025 to USD 3.15 billion in 2026 and is forecast to reach USD 5.34 billion by 2031 at 11.18% CAGR over 2026-2031. Growth is being propelled by steady breakthroughs in high-resolution imaging systems, the shift toward non-invasive diagnostics, and widening use in ophthalmology, cardiology, oncology, dermatology, and neurology. Integration with artificial intelligence is improving detection accuracy and workflow speed, while multi-modal platforms that merge optical coherence tomography (OCT) with photoacoustic or hyperspectral tools are expanding clinical value. Semiconductor shortages are nudging suppliers to redesign detectors and pursue vertical integration, yet the optical imaging market continues to benefit from resilient procurement budgets in hospitals, ambulatory surgery centers, and research labs. Asia-Pacific’s rapid uptake of handheld OCT for diabetic eye screening and North America’s favorable reimbursement for OCT-guided coronary interventions further reinforce the expansion path.
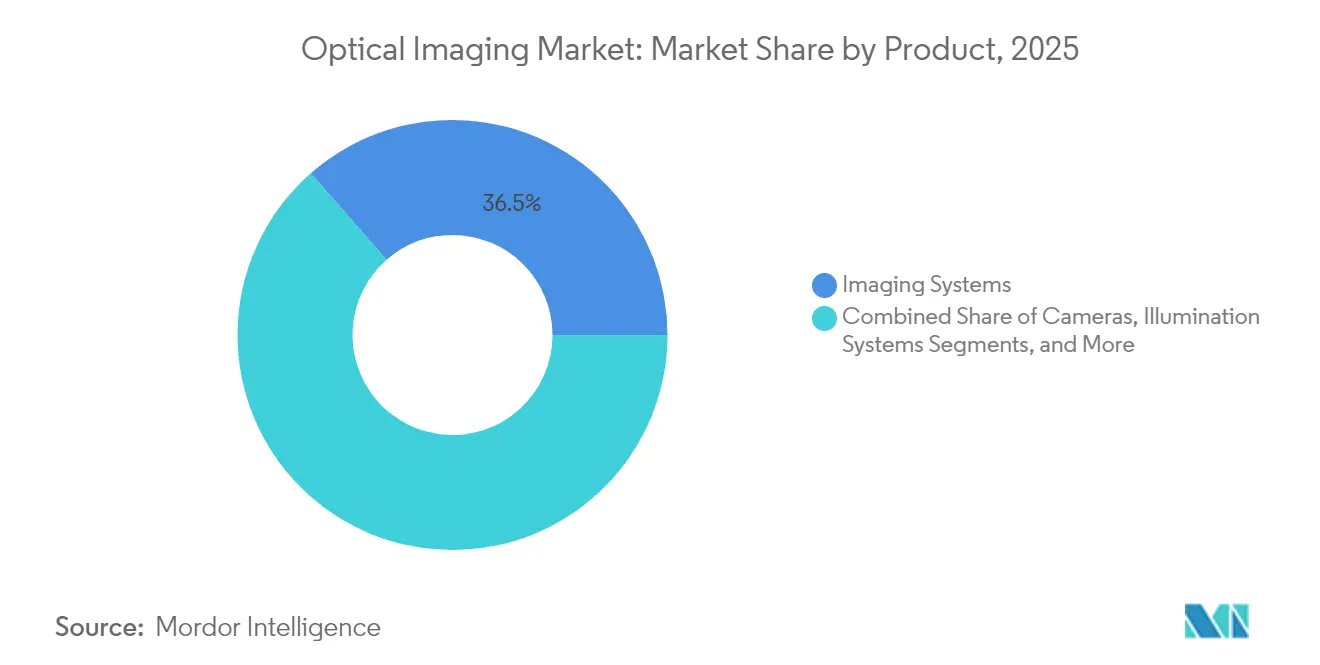
Key Report Takeaways* By product, Imaging Systems led with 36.45% revenue share in 2025, whereas Cameras are forecast to post the fastest 12.1% CAGR through 2031.
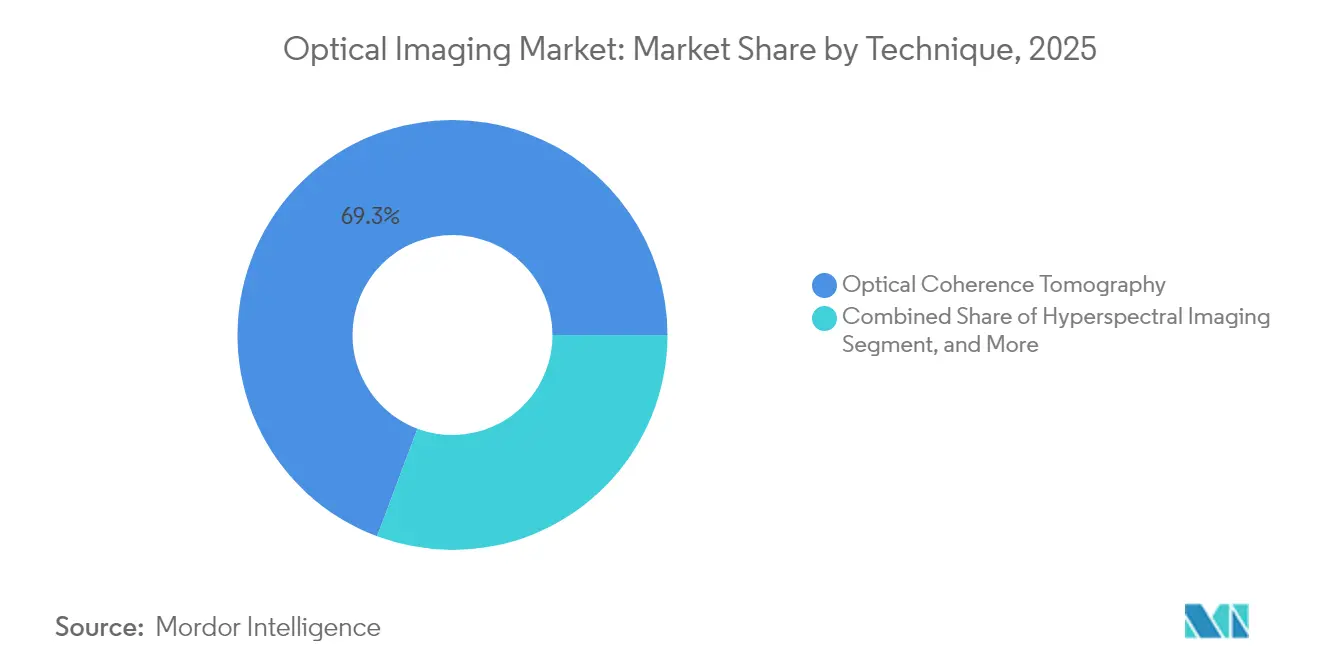
- By technique, Optical Coherence Tomography accounted for 69.30% of the optical imaging market share in 2025; Photoacoustic Tomography is projected to grow at 13.12% CAGR to 2031.
- By application, Ophthalmology held 34.10% of the optical imaging market size in 2025, while Oncology is advancing at a 14.58% CAGR to 2031.
- By end-user, Hospitals & Clinics retained a 44.25% share in 2025; Research & Diagnostic Laboratories are poised for a 12.36% CAGR over 2026-2031.
- By Region, North America commanded 39.40% of 2025 revenue, yet Asia-Pacific is expected to achieve a 12.02% CAGR, the highest among all regions.
Note: Market size and forecast figures in this report are generated using Vijeron Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Section 3
Market Trends and InsightsDrivers Impact Analysis of Optical Imaging Market*Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
Accelerated deployment of intra-operative optical imaging systems in ambulatory surgery centers | +2.8% | North America & EU | Medium term (2-4 years) |
Expanding reimbursement coverage for OCT-guided PCI in the United States & Japan | +2.3% | United States & Japan | Medium term (2-4 years) |
Rapid adoption of handheld OCT for diabetic retinopathy screening in primary-care settings | +2.0% | Asia, spillover to North America | Short term (≤ 2 years) |
Integration of AI-based spectral algorithms in dermatology diagnostic workflows | +1.7% | EU clinics, North America | Medium term (2-4 years) |
Surge in pharma demand for label-free optical sectioning to accelerate oncology drug discovery | +1.4% | Global | Long term (≥ 4 years) |
Military funding for photoacoustic tomography in trauma triage | +1.1% | Middle-East, spillover to North America | Long term (≥ 4 years) |
Source: Vijeron Intelligence |
Accelerated deployment of intra-operative optical imaging systems in ambulatory surgery centersAmbulatory surgery centers (ASCs) performed more than 23 million procedures in the United States in 2024, a 15% year-on-year rise as payers reposition surgeries to outpatient settings. Compact intra-operative optical platforms, exemplified by UCLA Health’s Dynamic Optical Contrast Imaging device, are gaining traction because they delineate tumor margins in real time and trim procedure time by 20%, boosting ASC throughput. Capital spending on these systems is justified by 35-50% cost savings relative to hospital surgeries and by growing insurer support for outpatient pathways. Reimbursement shifts are expected to drive ASC share of all surgeries to 68% by 2030, feeding demand for portable, network-ready optical rigs and widening the optical imaging market base.[1]Kevin Hermosura, “Dynamic Optical Contrast Imaging Enhances Cancer Surgery,” UCLA Health, uclahealth.org
Expanding reimbursement coverage for OCT-guided PCI in the United States & JapanThe OCCUPI trial reported a 4.9% composite event rate for OCT-guided PCI at one year compared with 9.5% for angiography alone, sparking policy changes that lift reimbursement by 12% in the United States and broaden coverage in Japan. Providers gain a 22% drop in repeat procedures, offsetting higher per-procedure costs and spurring adoption across high-risk coronary lesions. Utilization of OCT in coronary interventions is forecast to climb from 15% in 2024 to about 35% by 2028, embedding optical imaging deeper into interventional cardiology workflows.[2]Michael O’Riordan, “OCCUPI Trial Shows Benefits of OCT-Guided PCI,” TCTMD, tctmd.com
Rapid adoption of handheld OCT for diabetic retinopathy screening in primary care settingsLightweight OCT scanners priced roughly 60% below tabletop systems are entering Asia’s clinics and pharmacies, enabling same-visit exams for diabetic patients. The Lancet documented a 43% jump in screening compliance when AI-enhanced OCT was offered in primary care, compressing diagnosis time from weeks to minutes. National programs in India and China screened more than 3 million patients in 2024, validating the model and encouraging public health agencies elsewhere to follow suit. The American Diabetes Association’s call for annual OCT screening further cements handheld devices as a primary-care staple.[3]Rebecca Voelker, “Handheld OCT Boosts Diabetic Eye Screening Compliance,” The Lancet, thelancet.com
Integration of AI-based spectral algorithms in dermatology diagnostic workflowsMultispectral cameras coupled with deep-learning classifiers are achieving 95% sensitivity and 86% specificity for melanoma detection, outperforming average dermatologist accuracy. Clinics adopting these systems report a 30% reduction in unnecessary biopsies and a 25% rise in early malignant lesion detection. As regulatory clearances accelerate and cloud-based software lowers entry costs, penetration is projected to reach 40% of dermatology practices in developed markets by 2027, adding momentum to the optical imaging market.[4]Youn-Hee Nahm, “AI-Assisted Spectral Imaging in Melanoma Detection,” International Journal of Dermatology, onlinelibrary.wiley.com
Restraints Impact Analysis of Optical Imaging Market*Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
Capital-intensive shift from benchtop to integrated operating-room imaging suites | -1.7% | Global, with higher impact in emerging markets | Medium term (2-4 years) |
Limited reimbursement for dental optical imaging procedures in Europe | -1.4% | Europe | Short term (≤ 2 years) |
Scarcity of hyperspectral imaging experts slows clinical validation in emerging Asia | -1.1% | Asia-Pacific, particularly India and Southeast Asia | Medium term (2-4 years) |
Phototoxicity concerns restricting repeat imaging in paediatric neurology | -0.9% | Global | Long term (≥ 4 years) |
Source: Vijeron Intelligence |
Capital-intensive shift from benchtop to integrated operating-room imaging suitesFully integrated optical suites bundling OCT, fluorescence, and navigation cost USD 1.5-2.5 million per theater, triple to quadruple benchtop setups, and require extensive infrastructure rewiring. Hospitals also carry 15-20% extra ownership costs over five years for service contracts and specialist training. Consequently, only 23% of eligible hospitals had completed full integration in 2024, with many deferring upgrades or phasing modules over multiple budget cycles. Emerging economies face sharper constraints, slowing penetration despite clear clinical benefits.
Limited reimbursement for dental optical imaging procedures in EuropeInsurance frameworks across Germany, France, Italy, Spain, and the UK cover fewer than 15% of advanced dental OCT or photoacoustic scans, labeling them premium services. Adoption sits at 8% of European dental practices versus 27% in North America, producing a two-tier market divided between upscale clinics and standard practices that rely on radiography. Efforts by industry and professional associations to harmonize reimbursement codes are ongoing, yet until policy alignment occurs, uptake in mainstream dentistry will lag, tempering overall optical imaging market growth.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Section 4
Optical Imaging Market Segment AnalysisBy Product:Cameras Disrupt Traditional Imaging SystemsImaging Systems held 36.45% of revenue in 2025 on the strength of turnkey consoles used across ophthalmology, cardiology, and research settings. The optical imaging market size for this segment is forecast to expand steadily as vendors augment consoles with AI software and multi-modal add-ons. Rising demand for real-time guidance in minimally invasive surgery maintains hospital investment, even as procurement teams grapple with semiconductor shortages that inflate detector costs. Meanwhile, high-speed Cameras are redefining performance thresholds. Phantom High-Speed’s S710 camera achieves 4,000 fps in holographic retinal blood-flow imaging, enabling precise Doppler calculations that enhance vascular diagnostics. This technical leap aligns with a projected 12.1% CAGR through 2031, the fastest within the product spectrum.
Next-generation illumination engines using narrow-band LEDs and super-continuum lasers sustain interest in the Illumination Systems segment as surgeons seek tissue-specific contrast. Software solutions, once peripheral, now anchor differentiation because AI algorithms deliver automated segmentation, vessel quantification, and anomaly flagging. Lenses remain indispensable: advances in aspheric and gradient-index optics boost depth penetration and reduce chromatic aberration, elevating image clarity. To mitigate chip shortages, TDK’s Spin Photo Detector leverages magnetic elements to detect light at ultra-high speeds, opening a path to sidestep conventional semiconductor bottlenecks and stabilize component supply chains.
Image © Vijeron Intelligence. Reuse requires attribution under CC BY 4.0. By Application:Oncology Emerges as Growth CatalystOphthalmology retained the largest slice at 34.10% in 2025 due to entrenched OCT use for retinal disease management. Adaptive optics technologies are now revealing photoreceptor mosaics and choriocapillaris flow, allowing pre-symptomatic detection of macular disorders. In parallel, Oncology is gaining momentum with a 14.58% CAGR because optical imaging guides margin assessment during tumor resection and tracks vascular response during therapy. Photoacoustic contrast agents targeting hypoxic zones are enabling centimeter-deep visualization of tumor microenvironments in real time. Consequently, the optical imaging market share for oncology applications is set to rise as tertiary hospitals standardize intraoperative optical guidance.
Cardiology follows closely: OCT-guided percutaneous coronary intervention is proving superior to angiography alone in complex lesion management. The optical imaging market size for cardiology is projected to accelerate as more payers authorize coverage. Dermatology benefits from AI-enabled spectral scanners that cut biopsies and improve triage of suspicious lesions. Neurology and Dentistry niches are smaller yet innovative: intraoperative brain OCT tracks tissue mechanics, while dental OCT aids early caries detection without ionizing radiation. Pharmaceutical research groups employ label-free sectioning to visualize drug-cell interactions, shortening oncology drug discovery cycles.
By Technique:Photoacoustic Tomography Gains MomentumOptical Coherence Tomography dominated with 69.30% share in 2025 because it combines micrometer-scale resolution with rapid acquisition. Dynamic contrast OCT is breaking new ground by mapping live cell activity without exogenous labels, widening appeal in neurology and regenerative medicine. At the same time, Photoacoustic Tomography is surging on a 13.12% CAGR trajectory. By converting absorbed optical energy into ultrasonic waves, PAT provides optical contrast at ultrasonic resolution several centimeters deep, facilitating vascular imaging beyond the reach of pure optical methods. The International Photoacoustic Standardization Consortium’s protocols and the introduction of CPT codes are smoothing clinical entry, which should enlarge the optical imaging market size attributed to PAT procedures.
Near-Infrared Spectroscopy continues to assist in bedside tissue-oxygenation monitoring in oncology and neonatal care, while Hyperspectral Imaging addresses surgical guidance by differentiating perfused versus ischemic tissue. Hyperspectral datasets remain computationally intensive, but cloud-based analytics and lighter push-broom cameras are making operating-room deployment feasible. Collaborative research focuses on compressive sensing algorithms that shrink acquisition time, potentially lifting adoption where surgical schedules are tight.
Image © Vijeron Intelligence. Reuse requires attribution under CC BY 4.0. By End-User:Research Labs Accelerate Innovation AdoptionHospitals & Clinics captured 44.25% of spending in 2025, embedding multi-modal optical imaging towers in operating rooms and catheterization labs. Many centers bundle optical modalities with robotic systems, aiming to elevate surgical precision and shorten recovery times. The optical imaging market continues to benefit from hospitals’ shift toward value-based care that rewards diagnostics enabling early intervention. Research & Diagnostic Laboratories, however, are the fastest movers at 12.36% CAGR. Pharmaceutical firms rely on label-free optical sectioning to study cell mechanics and drug uptake in living tissues, compressing lead-optimization timelines and lowering attrition in oncology pipelines.
Diagnostic Imaging Centers expand service menus by adding ocular, coronary, and dermatologic optical scans, addressing outpatient demand and relieving hospital backlogs. Ambulatory surgery centers demand portable, network-enabled optical scanners that align with compact OR footprints and quick turnover. Specialized clinics in dermatology and dentistry are adopting handheld or cart-based devices, bridging the gap between point-of-care cost efficiency and advanced imaging quality.
Section 5
Geography AnalysisNorth America Optical Imaging MarketNorth America held 39.40% share in 2025, anchored by strong reimbursement and an innovation ecosystem linking universities, startups, and large device makers. The FDA’s green light for AI-assisted skin-cancer optical readers in 2024 accelerated cross-specialty adoption, while Duke University’s handheld OCT prototypes advance point-of-care eye exams. The optical imaging market size in the region will keep growing as insurers widen coverage for AI-integrated diagnostics and as capital budgets target hybrid OR upgrades.
APAC Optical Imaging MarketAsia-Pacific is the fastest-growing cluster, projected at a 12.02% CAGR. Governments in China, India, and Japan are funding domestic manufacturing, lowering import reliance, and subsidizing upgrades for rural clinics. Widespread use of handheld OCT in diabetic retinopathy screening is closing access gaps. Nevertheless, the lack of hyperspectral imaging specialists slows clinical trials, particularly in India and Southeast Asia. Cross-border training partnerships aim to build a talent pipeline that sustains longer-term adoption. Despite these hurdles, the optical imaging market in Asia-Pacific benefits from rising healthcare investment and high diabetes prevalence that drives retinal screening demand.
EMEA Optical Imaging MarketEurope maintains a sizeable base supported by robust research grants and academic hospital networks. German, French, and UK centers lead clinical validation in dermatology and neurology, yet dental applications suffer under fragmented reimbursement. Only 8% of dental practices use optical imaging because private pay models limit patient uptake. Eastern European health systems, meanwhile, seek lower-cost platforms to address unmet oncology imaging needs. The Middle East and Africa, while smaller, record steady uptake in specialist hospitals across the UAE and Saudi Arabia, buoyed by government-backed infrastructure spending and military interest in trauma imaging.
Image © Vijeron Intelligence. Reuse requires attribution under CC BY 4.0.
Section 6
Regulatory LandscapeOptical imaging systems and software are regulated primarily as medical devices when used for diagnosis, treatment planning, or intra-procedural guidance, with additional scrutiny when artificial intelligence is embedded in image interpretation or clinical decision support. In the United States, the FDA finalized guidance on Predetermined Change Control Plans (PCCP) for AI-enabled devices on December 3, 2024, formalizing an approach to manage post-market model updates within an agreed change protocol, rather than treating each modification as a standalone submission.
Regulatory classification is also shifting for certain optical diagnostic and software-aided skin lesion analysis tools. On March 25, 2026, the FDA issued a final order reclassifying software-aided adjunctive diagnostic devices for skin lesion analysis (and related technologies such as electrical impedance spectrometers used in melanoma assessment) from Class III to Class II with special controls, lowering barriers for compliant products while keeping defined performance and risk controls in place. In Europe, the Medical Device Regulation (MDR) continues to shape requirements for optical imaging hardware and software, while the EU AI Act (Regulation 2024/1689) adds a parallel compliance layer for high-risk AI, with key obligations phasing in from August 2, 2026; this pushes suppliers toward stronger lifecycle documentation, validation, and traceability practices. Standards development also anchors conformity work, including ISO 16971-1:2024 for ophthalmic instruments (OCT) and ISO 8600-1:2025 for endoscopes, alongside ISO/TR 24936:2026 addressing health informatics aspects of endoscopic video.
Section 7
Competitive Landscape
The optical imaging market is moderately fragmented, with incumbents such as Carl Zeiss Meditec, Leica Microsystems, and Olympus competing alongside agile specialists like Optovue and Damae Medical. Strategic focus has shifted from hardware differentiation to integrated software ecosystems that leverage AI and cloud connectivity. Recurring revenue from consumables and analytics subscriptions accounted for 47% of leading vendors’ turnover in 2024, underscoring the transition to service-centric models.
Semiconductor shortages triggered by a 75% jump in germanium prices since January 2023 compelled companies to redesign detectors, qualify second-source suppliers, and in some cases acquire upstream component makers. TDK’s Spin Photo Detector illustrates how magnetic-based photonics could relieve pressure on traditional supply chains and unlock ultrafast light detection for next-gen systems. Meanwhile, Carl Zeiss Meditec reported EUR 2,066.1 million revenue in fiscal 2024, crediting premium intraocular lenses and advanced imaging for segment growth.
White-space opportunities arise in point-of-care scenarios. Portable OCT and photoacoustic units tailored for ASCs and field hospitals broaden reach beyond tertiary centers. AI-augmented dermatology cameras are penetrating outpatient clinics, driven by rising skin-cancer incidence and consumer demand for quick triage. Competitive intensity is poised to heighten as multinational imaging firms acquire niche AI startups to add proprietary algorithms and accelerate regulatory approvals.
Optical Imaging Industry Leaders* Carl Zeiss AG
- Leica Microsystems (Danaher Corporation)
- Topcon Corporation
- Canon Medical Systems Corporation (Canon Inc.)
- Koninklijke Philips NV (Philips)
- *Disclaimer: Major Players sorted in no particular order
Image © Vijeron Intelligence. Reuse requires attribution under CC BY 4.0.Optical Imaging Market Companies Covered in this Report* Carl Zeiss AG
- Leica Microsystems (Danaher)
- Topcon Corporation
- Canon Medical Systems (Canon Inc.)
- Koninklijke Philips NV
- PerkinElmer Inc.
- Nikon Metrology NV (Nikon Corp.)
- Olympus Corporation
- Teledyne Princeton Instruments
- Prior Scientific
- Thorlabs Inc.
- Abbott Laboratories
- Headwall Photonics Inc.
- Optovue Inc.
- Cytoviva Inc.
- Michelson Diagnostics Ltd.
- Damae Medical
- Wasatch Photonics Inc.
- Santec Corporation
- BaySpec Inc.
- Optovue Inc.
Section 8
Market Opportunities and Future Outlook
Near-term whitespace is opening where optical imaging can be used outside traditional tertiary settings, supported by portability, workflow automation, and reimbursement-aligned use cases. Handheld OCT adoption for diabetic retinopathy screening in primary care is supported by large-scale screening activity in India and China, with more than 3 million patients screened in 2024 across national programs referenced in the study context. This activity supports demand for lower-cost systems, cloud-connected software, and AI triage that fit retail clinics and community care pathways. In cardiology, expanded reimbursement coverage for OCT-guided PCI in the United States and Japan supports broader clinical standardization, which tends to favor vendors that bundle imaging consoles with procedure workflows, automated interpretation, and lab integration rather than selling hardware alone.
Technology roadmaps in 2026 research also point to opportunities for multi-modal and computationally enabled optical imaging aimed at improving depth, throughput, and robustness in real-world samples. Publications in 2026 highlighted high-throughput volumetric microscopy concepts (for example, RUSH3D-HR in Nature Biotechnology) and hybrid optics approaches such as HySIL (Nature Biotechnology), reinforcing a market shift toward systems that combine advanced optics with algorithmic correction, automated analysis pipelines, and high-volume data handling. In translational and clinical workflows, multimodal combinations such as photoacoustic-ultrasound with fluorescence agents (Scientific Reports, 2026) and integrated two-photon and photoacoustic microscopy (Nature Communications, 2026) outline product design space for platforms that unify structural, functional, and molecular contrast in one session, which aligns with oncology and intraoperative guidance where margin assessment and tissue characterization influence purchasing decisions.
Section 9
Recent Industry Developments in Optical Imaging Market* June 2026: Leica Microsystems expanded its Viventis Deep dual view light sheet microscope capabilities to include cleared sample imaging. The update broadens a single platform from live dynamics to structural context workflows, supporting labs that want both high-speed 3D imaging and deep tissue visualization without switching systems.
- August 2025: Carl Zeiss Meditec received CE mark approval for CIRRUS PathFinder, an AI-integrated clinical support tool designed to aid OCT interpretation. This strengthens ZEISS position in software-led differentiation and supports faster clinical workflows in ophthalmology by pairing imaging hardware with decision-support capabilities.
- June 2024: Carl Zeiss Meditec announced OCT technology enhancements across its portfolio. These updates reinforce incremental performance and usability improvements that help protect installed-base competitiveness as providers increasingly compare devices on workflow integration and diagnostic consistency rather than imaging hardware specifications alone.
Section 10
Table of Contents for Optical Imaging Industry Report1. Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
- Research Methodology
- Executive Summary
- Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers* 4.2.1 Accelerated deployment of intra-operative optical imaging systems in ambulatory surgery centres (North America and EU)
- 4.2.2 Expanding reimbursement coverage for OCT-guided PCI in the United States and Japan
- 4.2.3 Rapid adoption of handheld OCT for diabetic retinopathy screening in primary-care settings (Asia)
- 4.2.4 Integration of AI-based spectral algorithms in dermatology diagnostic workflows (EU major clinics)
- 4.2.5 Surge in pharma demand for label-free optical sectioning to accelerate oncology drug discovery
- 4.2.6 Military funding for photoacoustic tomography in trauma triage (Middle-East and Israel)
- 4.3 Market Restraints* 4.3.1 Capital-intensive shift from benchtop to integrated operating-room imaging suites
- 4.3.2 Limited reimbursement for dental optical imaging procedures in Europe
- 4.3.3 Scarcity of hyperspectral imaging experts slows clinical validation in emerging Asia
- 4.3.4 Phototoxicity concerns restricting repeat imaging in paediatric neurology
- 4.4 Regulatory Outlook
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis* 4.6.1 Bargaining Power of Suppliers
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
- Market Size and Growth Forecasts (Value)
- 5.1 By Product* 5.1.1 Imaging Systems
- 5.1.1.1 Optical Imaging Systems
- 5.1.1.2 Spectral Imaging Systems
- 5.1.2 Cameras
- 5.1.3 Illumination Systems
- 5.1.4 Lenses
- 5.1.5 Software
- 5.2 By Application* 5.2.1 Ophthalmology
- 5.2.2 Dentistry
- 5.2.3 Dermatology
- 5.2.4 Cardiology
- 5.2.5 Neurology
- 5.2.6 Oncology
- 5.2.7 Biotechnology and Research
- 5.2.8 Other Applications
- 5.3 By Technique* 5.3.1 Optical Coherence Tomography
- 5.3.2 Near-Infrared Spectroscopy
- 5.3.3 Hyperspectral Imaging
- 5.3.4 Photoacoustic Tomography
- 5.4 By End-User* 5.4.1 Hospitals and Clinics
- 5.4.2 Diagnostic Imaging Centres
- 5.4.3 Research and Diagnostic Laboratories
- 5.4.4 Other End-Users
- 5.5 By Geography* 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Chile
- 5.5.2.4 Peru
- 5.5.2.5 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 South Korea
- 5.5.4.4 India
- 5.5.4.5 Australia
- 5.5.4.6 New Zealand
- 5.5.4.7 Rest of Asia-Pacific
- 5.5.5 Middle East
- 5.5.5.1 United Arab Emirates
- 5.5.5.2 Saudi Arabia
- 5.5.5.3 Turkey
- 5.5.5.4 Rest of Middle East
- 5.5.6 Africa
- 5.5.6.1 South Africa
- 5.5.6.2 Rest of Africa
- Competitive Landscape
- 6.1 Strategic Developments
- 6.2 Vendor Positioning Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)* 6.3.1 Carl Zeiss AG
- 6.3.2 Leica Microsystems (Danaher)
- 6.3.3 Topcon Corporation
- 6.3.4 Canon Medical Systems (Canon Inc.)
- 6.3.5 Koninklijke Philips NV
- 6.3.6 PerkinElmer Inc.
- 6.3.7 Nikon Metrology NV (Nikon Corp.)
- 6.3.8 Olympus Corporation
- 6.3.9 Teledyne Princeton Instruments
- 6.3.10 Prior Scientific
- 6.3.11 Thorlabs Inc.
- 6.3.12 Abbott Laboratories
- 6.3.13 Headwall Photonics Inc.
- 6.3.14 Optovue Inc.
- 6.3.15 Cytoviva Inc.
- 6.3.16 Michelson Diagnostics Ltd.
- 6.3.17 Damae Medical
- 6.3.18 Wasatch Photonics Inc.
- 6.3.19 Santec Corporation
- 6.3.20 BaySpec Inc.
- Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment
Section 11
Optical Imaging Market Report Scope and Research MethodologyMarket Definition and CoverageFor this study, the optical imaging market is defined as the revenue generated from optical imaging techniques and related systems that use light (from UV to near-infrared) to create images for clinical, diagnostic, and research use across major regions.
Scope exclusions: We exclude general-purpose photography equipment and consumer imaging devices that are not used for medical, diagnostic, industrial inspection, or scientific imaging workflows.
Segments Covered in This Report By Product Imaging Systems* Optical Imaging Systems
- Spectral Imaging Systems
- Cameras
- Illumination Systems
- Lenses
- Software
- By Application* Ophthalmology
- Dentistry
- Dermatology
- Cardiology
- Neurology
- Oncology
- Biotechnology and Research
- Other Applications
- By Technique* Optical Coherence Tomography
- Near-Infrared Spectroscopy
- Hyperspectral Imaging
- Photoacoustic Tomography
- By End-User* Hospitals and Clinics
- Diagnostic Imaging Centres
- Research and Diagnostic Laboratories
- Other End-Users
- By Geography North America United States
- Canada
- Mexico
- South America* Brazil
- Argentina
- Chile
- Peru
- Rest of South America
- Europe* Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific* China
- Japan
- South Korea
- India
- Australia
- New Zealand
- Rest of Asia-Pacific
- Middle East* United Arab Emirates
- Saudi Arabia
- Turkey
- Rest of Middle East
- Africa* South Africa
- Rest of Africa
Data Sources, Market Sizing, and ValidationDesk Research
Desk research was used to build the market structure, confirm commonly used technology definitions, and collect indicators that move demand up or down each year. Public sources such as the US FDA device databases, the US National Institutes of Health (NIH) publications and grants, the World Health Organization (WHO) health statistics, and OECD health expenditure series were reviewed to understand adoption signals tied to imaging usage.
We also scanned customs and trade statistics portals for optical components, reviewed peer-reviewed journals for clinical uptake patterns (for example, OCT usage in ophthalmology), and checked association websites and reputed press releases for product launches and regulatory clearances. Company filings, annual reports, and investor decks were used to sense-check pricing direction, product mix shifts, and geography focus. Where public disclosures were limited, company financials, intelligence subscriptions, and patent databases were used selectively to fill gaps. The sources listed here are illustrative only, and many other public references were also used for data collection, validation, and clarification during the analysis.
Primary Interviews and Surveys
Primary work was used to pressure-test market model assumptions that desk research cannot confirm cleanly, especially around average selling price movement, modality adoption speed, and replacement cycles for installed systems. We spoke with a mix of manufacturers, distributors, clinical users, and research labs across APAC, EMEA, and the Americas, then re-checked outlier responses with follow-up questions so the final inputs stayed consistent by technique and end use.
Distribution of primary research fieldwork respondents
Company type | Respondent position | Region |
Top tier: 26% | CXOs: 16% | APAC: 44% |
Mid tier: 53% | Functional/Unit leaders: 27% | EMEA: 37% |
Smaller Players: 21% | Managers: 57% | Americas: 19% |
Market-Sizing & ForecastingThe market was sized using a top-down and bottom-up blend. The top-down view starts from the addressable diagnostic and research imaging demand pool by region, then allocates spend across optical techniques and product categories. After building the demand pool, the totals were corroborated using selective bottom-up checks, such as sampled system shipments and typical price bands by modality, followed by channel feedback on mix and discounting.
Key model inputs included procedure and screening volumes in imaging-heavy specialties (especially ophthalmology), the pace of hospital and diagnostic center equipment refresh, penetration trends for OCT and other optical techniques, average selling price progression by system class, and regional healthcare and research funding signals. Because not all countries disclose the same level of data, gaps were handled through proxy indicators such as per-capita healthcare spend, import trends for optical components, and primary feedback on utilization and procurement timing.
For forecasting, scenario analysis was used as the main technique so the model could reflect different adoption speeds for newer modalities and different budget environments across regions. The scenarios were anchored to consensus ranges gathered from primary experts, then converted into annual growth paths that stayed consistent with the input variables and historical movement.
Data Validation & Update CycleModel outputs were validated through multiple checks, where estimates by region, technique, and end use were compared with independent signals such as procedure trends, regulatory approvals, and reported revenue direction from public company disclosures. When a segment showed a jump that did not match the underlying drivers, inputs were re-reviewed, and targeted call-backs were triggered to understand whether it was pricing, mix, or timing that drove the variance.
Before sign-off, the full workbook is reviewed in steps, first at the assumption level and then at the final totals level, so arithmetic, currency conversions, and year alignment stay consistent. Reports are refreshed annually, and interim updates are made when there are material events that can shift demand or pricing, followed by a final pre-delivery pass to make sure clients receive the most current view.
Vijeron Intelligence's Optical Imaging Market Market Size Compared With Other Published EstimatesIt is common to see different market sizes for optical imaging because publishers do not always count the same product scope, end-use settings, or timing for revenue recognition. Differences also come from how fast pricing is assumed to decline, how software is treated, and whether forecasts are built from procedure-driven demand signals or from broader equipment spending pools.
The main gap drivers here are what gets included under optical imaging systems versus adjacent imaging or optics categories, how technique-level adoption (such as OCT versus hyperspectral) is weighted by region, and whether estimates use an aggressive or conservative uptake curve for newer platforms. The table points to this spread, where some sources may fold in adjacent optical components and non-clinical imaging, while they are counted only when tied to defined optical imaging applications and product lines in the approach used by Vijeron Intelligence.
Benchmark comparison
Source | Market Size | Gaps in Research Methodology |
Vijeron Intelligence | USD 3.15 B (2026) | |
Global Consultancy A | USD 2.12 B (2025) | Uses an earlier base year and a narrower demand pool that leans toward clinical hardware, which can undercount software, illumination, and non-hospital research purchases that still drive revenue. |
Industry Publisher B | USD 1.90 B (2024) | Starts from a smaller 2024 base and applies a high-growth curve, but the scope description appears to mix technique coverage with broader optics categories, which can shift what is counted as optical imaging revenue year to year. |
Overall, the differences are largely explained by year alignment and what is treated as in-scope revenue, rather than by arithmetic. By tying totals back to technique adoption, end-user procurement, and pricing checks that can be repeated each year, the estimate stays traceable and easier to reconcile when buyers compare sources.
Section 12
Key Questions Answered in the ReportWhat is the current value of the optical imaging market? The optical imaging market is valued at USD 3.15 billion in 2026.
How fast is the optical imaging market expected to grow? It is forecast to expand at an 11.18% CAGR, reaching USD 5.34 billion by 2031.
Which technique holds the largest optical imaging market share? Optical Coherence Tomography commands 69.30% of revenue, making it the dominant technique.
Why is Asia-Pacific the fastest-growing region for optical imaging? Rapid adoption of handheld OCT for diabetic eye screening and expanding healthcare investment drive a projected 12.02% CAGR.
What factor is most boosting oncology applications in optical imaging? Surge in intra-operative optical imaging for real-time tumor margin assessment is propelling oncology applications at a 14.58% CAGR.
How are semiconductor shortages influencing optical imaging device design? Firms are investing in alternative detector technologies like magnetic-based Spin Photo Detectors to reduce reliance on scarce materials and stabilize supply.
Section 13
Related ReportsReport on Medical Imaging Software IndustryOptical Sensor IndustryIndustry Trends in US Optical Sensors