Optical Sorter Market Size & Share Analysis - Growth Trends and Forecast (2026 - 2031)
Optical Sorter Market Size & Share Analysis - Growth Trends and Forecast (2026 - 2031)
Industry: Technology, Media & Telecom (TMT)
Source: https://www.mordorintelligence.com/industry-reports/optical-sorter-market
Scraped Date: 2026-09-17
Key Market Estimates
| Variable | Value | Unit |
|---|
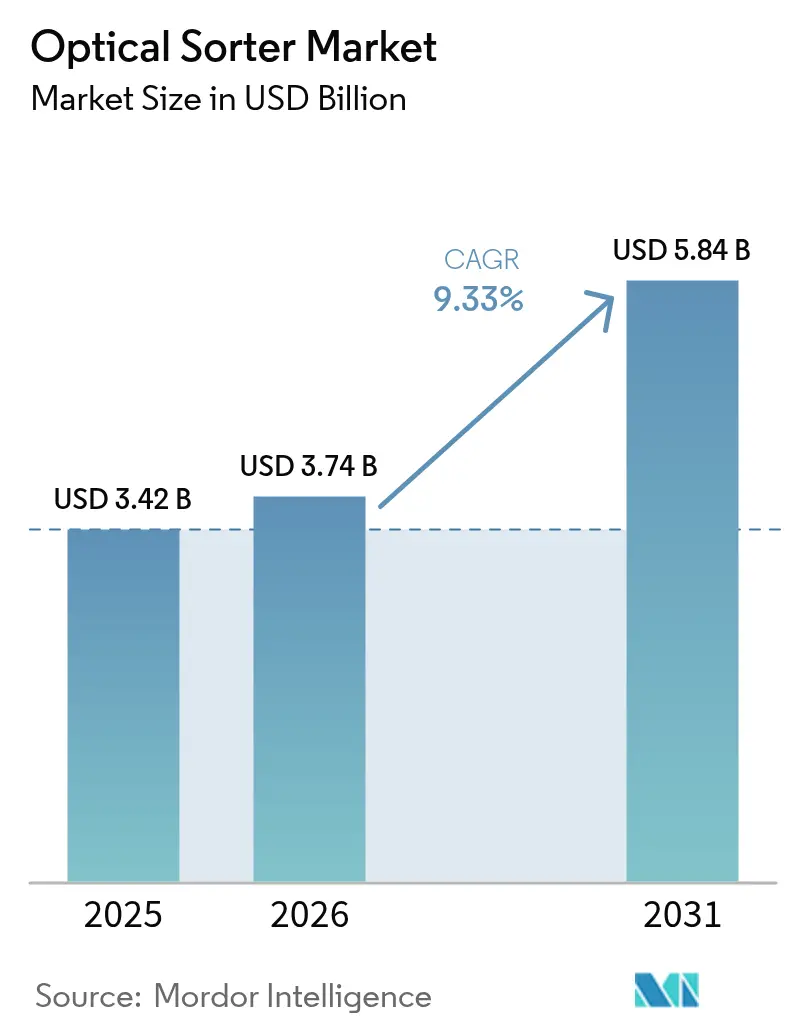
| Market Size (2026) | 3.74 | USD Billion |
|---|
| Market Size (2031) | 5.84 | USD Billion |
|---|
| Growth Rate (2026 - 2031) | 9.33 | PERCENT |
|---|
| Fastest Growing Market | Asia Pacific |
|---|
| Largest Market | North America |
|---|
| Market Concentration | Medium |
|---|
Section 1
Optical Sorter Market Size and ShareMarket OverviewStudy Period | 2020 - 2031 |
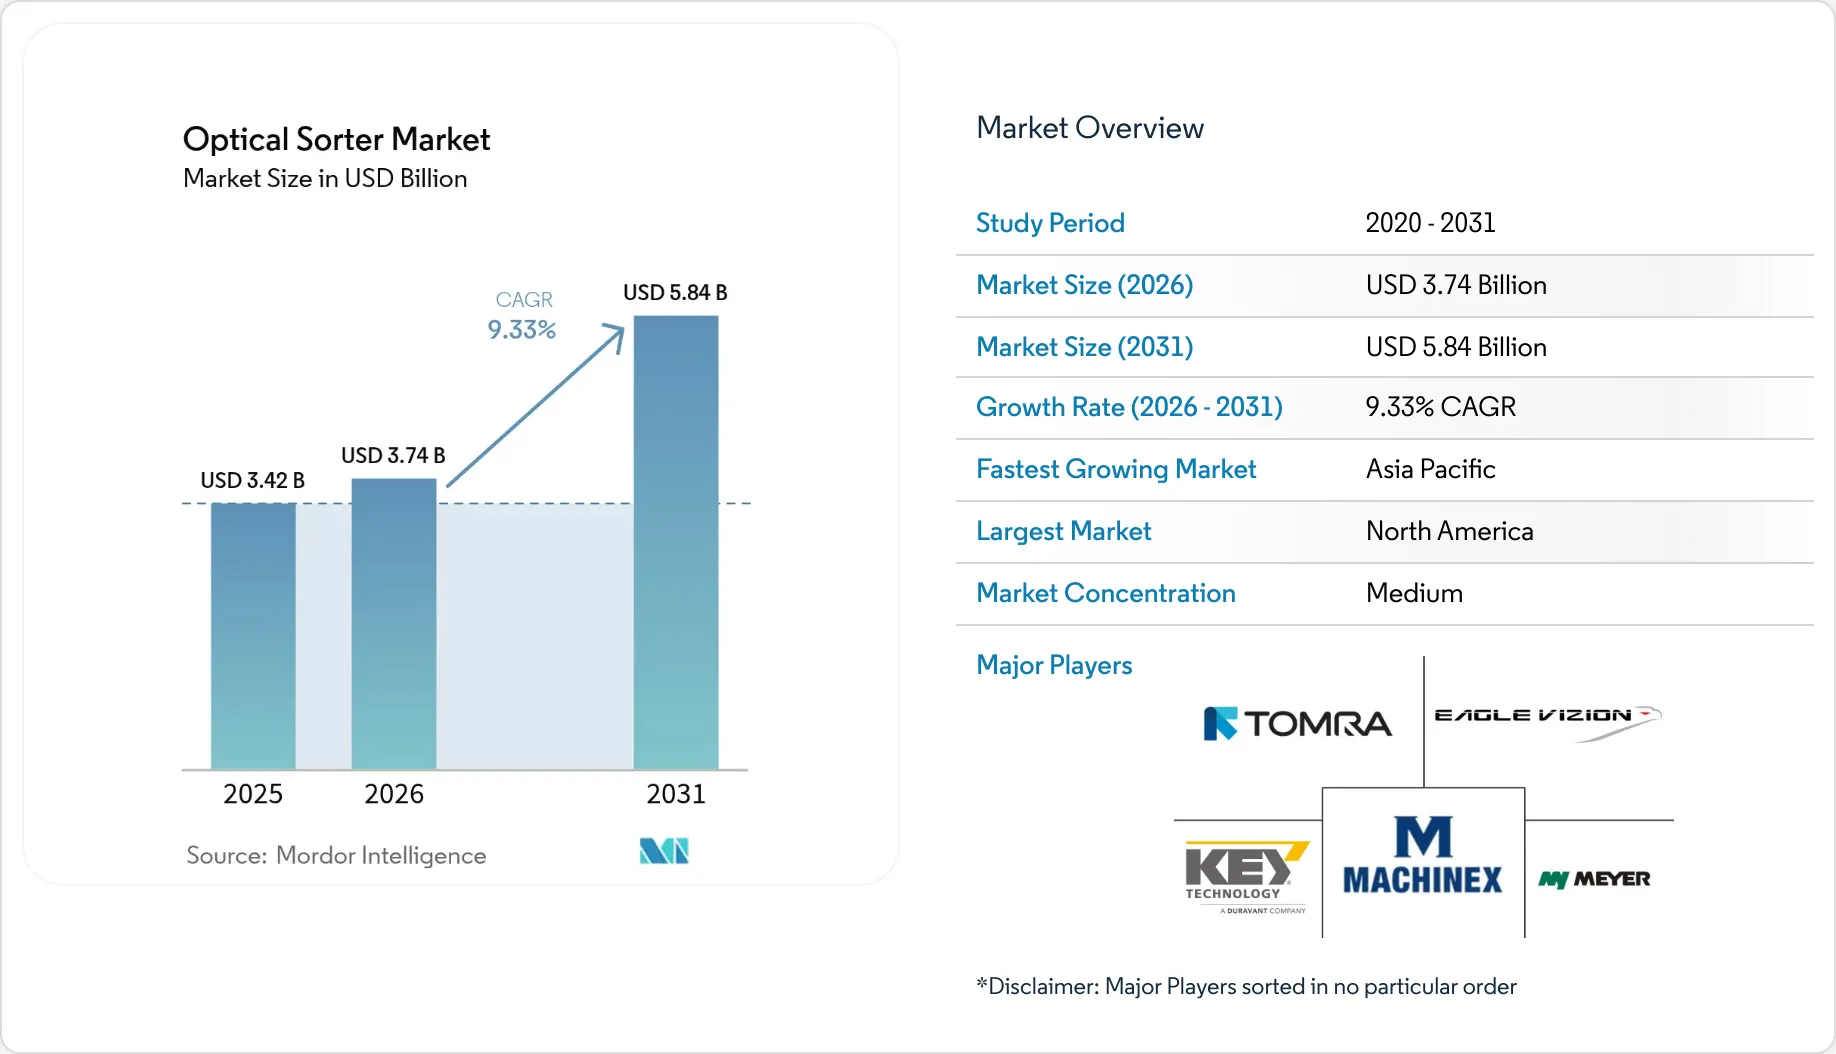
Market Size (2026) | USD 3.74 Billion |
Market Size (2031) | USD 5.84 Billion |
Growth Rate (2026 - 2031) | 9.33 % |
Fastest Growing Market | Asia Pacific |
Largest Market | North America |
Market Concentration | Medium |
Major Players*Disclaimer: Major Players sorted in no particular order
Image © Vijeron Intelligence. Reuse requires attribution under CC BY 4.0.
Image © Vijeron Intelligence. Reuse requires attribution under CC BY 4.0.
Section 2
Optical Sorter Market Analysis by Vijeron IntelligenceThe optical Sorter market size in 2026 is estimated at USD 3.74 billion, growing from 2025 value of USD 3.42 billion with 2031 projections showing USD 5.84 billion, growing at 9.33% CAGR over 2026-2031. This expansion stems from three intersecting forces: widening labor gaps across manufacturing hubs, increasingly stringent food safety and recycling mandates, and the rapid diffusion of AI-driven hyperspectral imaging that detects defects invisible to the human eye or to legacy camera systems. Suppliers are also benefiting from falling sensor costs and government funding that offsets capital expenditure for high-efficiency sorting equipment in food, recycling, and mining facilities. Competitive intensity is rising as Asian entrants roll out lower-priced, AI-infused platforms while Western incumbents integrate deep-learning modules into existing belt systems to protect installed bases. In parallel, sustainability regulations such as Extended Producer Responsibility (EPR) in Asia and deposit-return schemes in Europe continue to enlarge the total addressable market by tightening purity requirements for plastics, metals, and textiles.
Key Report Takeaways* By technology, camera-based systems led the optical sorter market with 33.92% of the market share in 2025, whereas near-infrared (NIR) sorters are projected to post the fastest growth of 11.45% CAGR through 2031.
- By platform, belt configurations accounted for 54.35% of the optical sorter market size in 2025 and are set to expand at a 11.86% CAGR, reflecting strong scalability for high-throughput lines.
- By end-user industry, food processing dominated with a 57.60% revenue share in 2025; the recycling segment is projected to grow at a 10.28% CAGR through 2031.
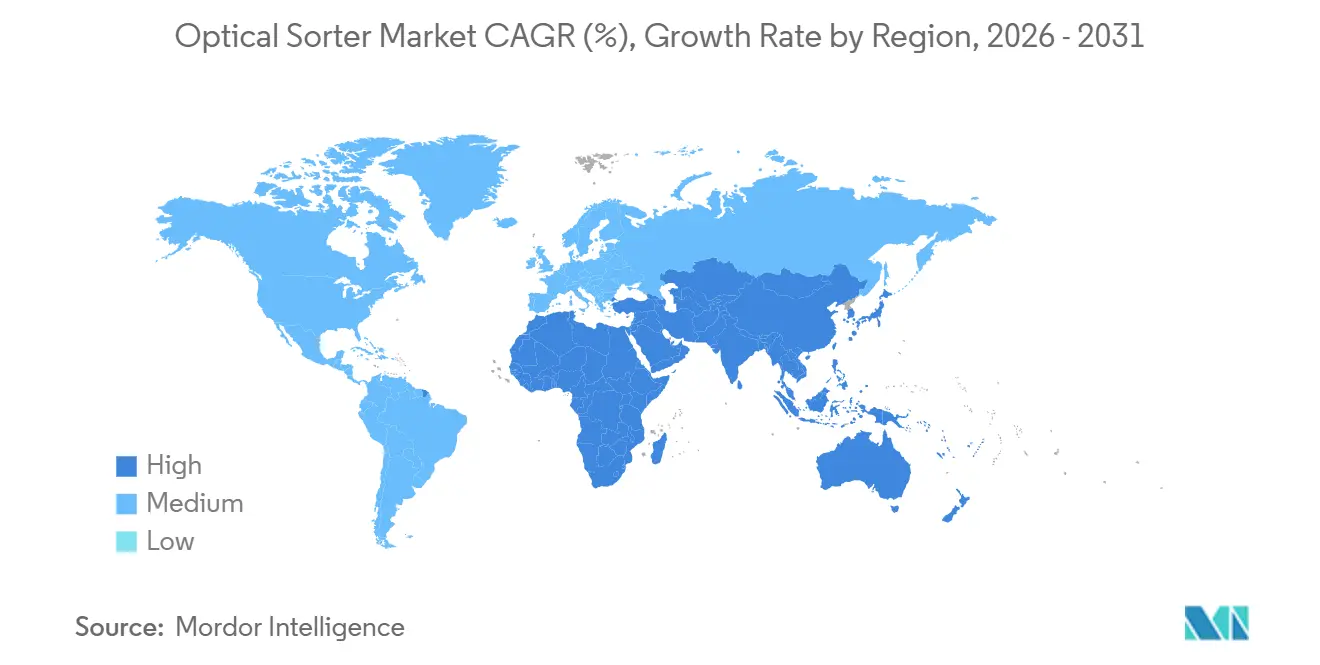
- By geography, North America held 33.55% revenue share of the optical sorter market in 2025, while Asia-Pacific is forecast to register the fastest 12.32% CAGR to 2031.
Note: Market size and forecast figures in this report are generated using Vijeron Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Section 3
Market Trends and InsightsDrivers Impact Analysis of Optical Sorter Market*Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
Automation demand in large-scale North American food plants | +2.10% | North America; spill-over to Europe | Medium term (2-4 years) |
Tightening global HACCP and EU food-hygiene regulations | +1.80% | EU, North America, Asia | Long term (≥ 4 years) |
Labor shortages and wage inflation in European recycling | +1.60% | Europe; spill-over to Asia-Pacific | Short term (≤ 2 years) |
AI-driven hyperspectral breakthroughs | +2.30% | Global | Long term (≥ 4 years) |
Extended Producer Responsibility (EPR) mandates in Asia | +1.20% | Asia-Pacific; emerging in MEA | Medium term (2-4 years) |
Declining ore grades prompting sensor-based pre-concentration | +1.40% | South America; Australia, Africa | Medium term (2-4 years) |
Source: Vijeron Intelligence |
Automation demand in large-scale North American food plantsPersistent staffing gaps 615,000 manufacturing jobs remained vacant in the United States at end-2024 are forcing processors to replace manual inspectors with high-speed optical sorters that sustain 24/7 uptime while securing 25–35% higher product yield.[1]Mick Dueholm et al., “Does Worker Scarcity Spur Investment, Automation and Productivity?” stlouisfed.org Platform vendors now bundle vision algorithms that learn from production drifts to preserve accuracy without halting the line. Capital budgets reflect this priority shift, as U.S. food manufacturers invested USD 55 billion in automation between 2021 and 2024, allocating a growing slice to next-generation belt sorters capable of achieving 99% detection precision.[2]Karen Hanna, “High-speed sorting technology recovers 25–35% more product compared to manual inspection,” processingmagazine.com
Tightening global HACCP and EU food-hygiene regulationsEU Regulation 2023/915 explicitly positions optical sorter as an endorsed mitigation measure against mycotoxins and physical contaminants, compelling processors targeting the European market to adopt certified systems.[3]European Commission, “Regulation 2023/915,” eur-lex.europa.euComparable rules are rippling across Asia, prompting multinational food companies to synchronize quality-control investments. Compliance audits are increasingly requesting digital defect logs, a feature integrated into AI-enabled sorters that archives every rejected item for traceability.
Labor shortages and wage inflation in European recyclingWestern European recovery facilities report double-digit wage inflation and rising absenteeism, a mix that lifts the payback attractiveness of robotic optical sorter. Deployments of AI-guided pick-and-place arms have delivered 40% material-recovery gains at German plants while slashing labor costs 40–60%
AI-driven hyperspectral breakthroughsThe cost per hyperspectral line-scan sensor fell nearly 35% between 2021 and 2024, enabling vendors to combine visible, NIR, and short-wave infrared data streams on a single platform. Deep-learning firmware lifts yield by recognizing subtle spectral signatures of aflatoxins or polymer fillers, unlocking new use cases in nuts, pet food, and lithium ore sorting
Restraints Impact Analysis of Optical Sorter Market*Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
High CapEx for hyperspectral & X-ray systems in SME grain mills | –1.8% | Developing markets worldwide | Medium term (2-4 years) |
Frequent calibrations increase downtime in continuous-flow mining | –1.2% | South America, Australia, Africa | Short term (≤ 2 years) |
Data-ownership concerns in cloud-connected sorters | –0.9% | North America, EU | Medium term (2-4 years) |
Sensor fouling in high-moisture food applications | –0.7% | Global | Short term (≤ 2 years) |
Source: Vijeron Intelligence |
High CapEx for hyperspectral and X-ray systems in SME grain millsA fully loaded hyperspectral sorter can exceed USD 500,000, a threshold that strains balance sheets of small and medium grain processors. surveys rank upfront cost as the primary barrier to advanced equipment, especially where credit lines remain tight. Without leasing schemes, many mills continue to rely on less capable camera-only machines.
Frequent calibrations increase downtime in continuous-flow miningSensor drift from dust, humidity, and ore variability forces mines to recalibrate optical sorters every few shifts, pausing throughput and eroding return on investment. Remote sites often lack vision-system technicians, compounding the interruption and prompting requests for self-calibrating hardware
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Section 4
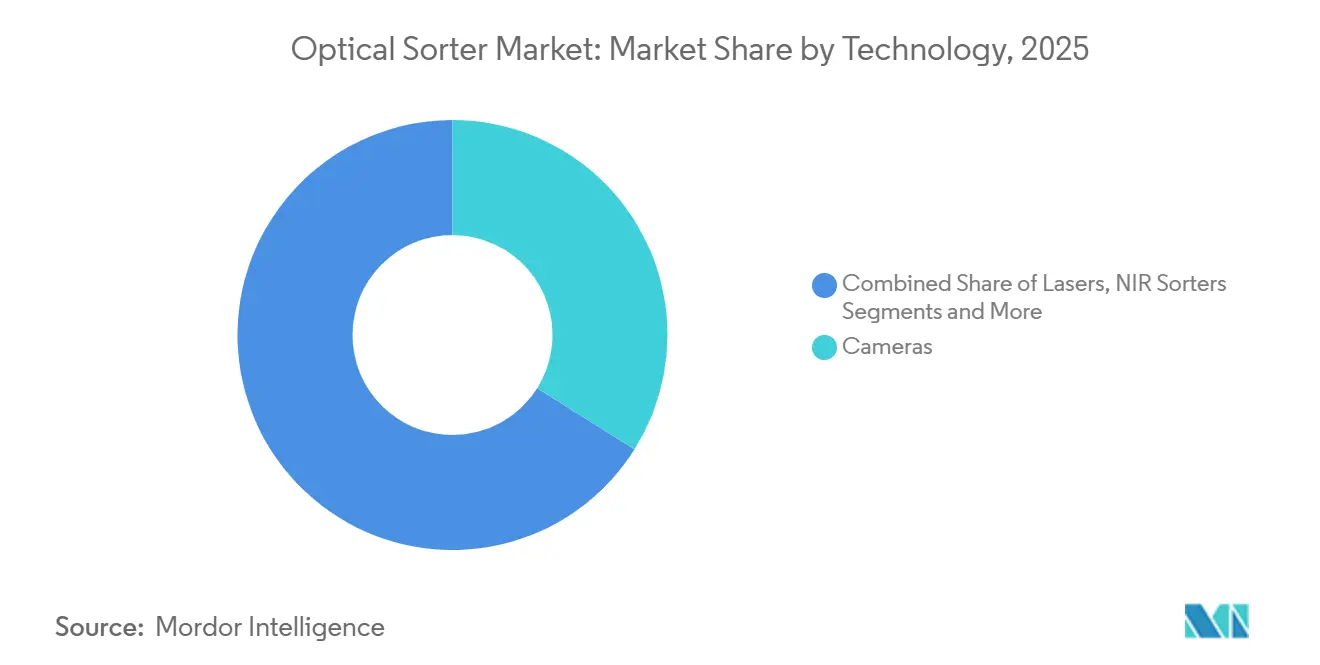
Optical Sorter Market Segment AnalysisBy Technology:AI Integration Accelerates NIR AdoptionIn revenue terms, camera systems accounted for 33.92% of the optical sorter market share in 2025, owing to their versatility in color-based defect removal. The optical sorter market size attributable to NIR platforms is on track to post the fastest 11.45% CAGR as processors utilize spectral fingerprints to distinguish polymers, proteins, and valuable ore fractions. Vendors now embed machine-learning engines that raise detection accuracy to 95%, trimming false-reject rates by double digits. Laser solutions retain niche demand for geometry-based differentiation, while hyperspectral systems target premium segments such as aflatoxin detection in pistachios or gemstone sorting. X-ray transmission is gaining traction in the separation of dense materials within copper and lithium mines, complementing optical sensors when density, rather than color, determines value recovery.
Blended sensing is becoming standard as OEMs stack cameras, NIR arrays, and short-wave infrared detectors inside the same chassis. This convergence cuts footprint, eases calibration, and broadens target defect profiles. Euro-funded R&D consortia anticipate that AI-assisted hyperspectral modules will increase overall yield by 20% compared to 2023 baselines. As multinationals demand turnkey solutions, platform suppliers that master cross-sensor data fusion stand to secure long-term service contracts.
Image © Vijeron Intelligence. Reuse requires attribution under CC BY 4.0. By Platform:Belt Systems Strengthen Scalability LeadBelt architectures held 54.35% of the optical sorter market size in 2025, due to compatibility with conventional conveyor layouts and the ability to process up to 10 metric tons per hour in cereal, nut, and polymer recycling lines. Engineering refinements such as velocity-controlled feed belts and automatic singulation now push defect detection above 98%, mitigating historical mis-sort issues. Compact free-fall designs remain favored for fragile dried fruits, while lane configurations address items requiring precise orientation, such as blister-pack tablets or sliced vegetables. Hybrid footprints merge belt infeed with cascade or chute discharge to cope with variable bulk densities.
AI-backed condition-monitoring modules are reducing the total cost of ownership by predicting actuator wear days in advance of failure. A leading cereal producer reported an 8% reduction in downtime after installing cloud-linked vibration sensors on its main ejection cylinders. As OEMs standardize modular frames, operators can retrofit sensor suites instead of replacing entire units, prolonging asset life and encouraging incremental upgrades.
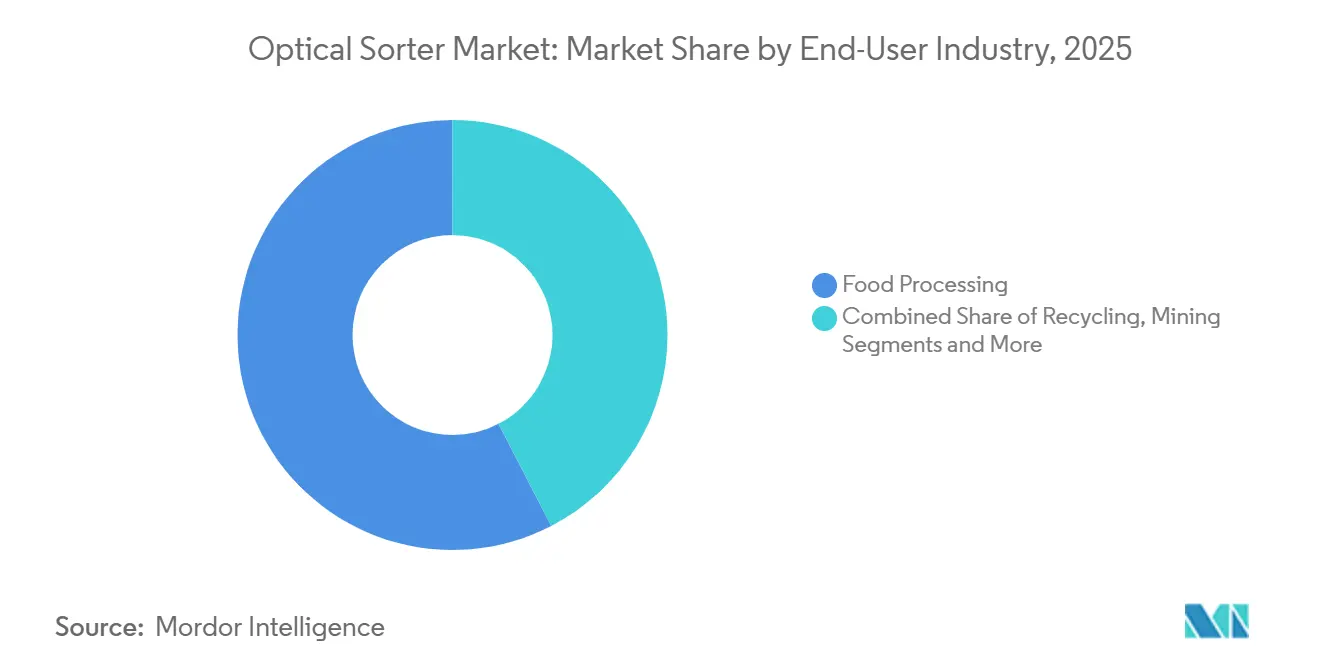
By End-User Industry:Recycling Becomes Growth EngineFood processors remained the revenue anchor with a 57.60% share in 2025, driven by safety mandates and retailer zero-defect contracts. However, the recycling sector is poised for the most rapid growth, with a 10.28% CAGR, as EPR legislation in China, Vietnam, and South Korea elevates purity thresholds for rPET, rPP, and aluminum flake. The optical sorter market serves recycling by combining vision, spectroscopy, and robotics to hit ≥95% purity at lower labor cost, as evidenced by Korean facilities running AI-guided arms that achieve 99.3% accuracy across 96 picks per minute.
Mining now moves beyond the pilot stage as ore grades deteriorate. A CAD 7.6 million ore-sorting trial at Rio Tinto’s Lac Tio mine underscores how sensor-based pre-concentration can defer costly mill expansions by stripping barren rock early in the flow sheet. Over the forecast horizon, mixed-material applications, such as textile-to-textile recycling, create new revenue streams for versatile optical sorters capable of distinguishing between cotton, polyester, and elastane blends.
Image © Vijeron Intelligence. Reuse requires attribution under CC BY 4.0.
Section 5
Geography AnalysisNorth America Optical Sorter MarketNorth America commanded 33.55% of 2025 revenues as processors adopted automation to address persistent labor shortages and comply with FSMA and state-level recycled-content regulations. Federal energy grants totaling USD 33 million earmarked for smart manufacturing accelerate optical-sorting retrofits across meat, dairy, and beverage facilities. Canada’s Plastics Innovation Challenges channel additional funds toward AI-led hyperspectral projects, enabling recyclers to double the recovery of flexible packaging.
APAC Optical Sorter MarketThe Asia-Pacific region is forecast to lead with a 12.32% CAGR to 2031, driven by China’s first fully automated carton-sorting plant in Xiamen and Japan’s demographic headwinds, which are expected to boost demand for robotic vision systems. Vietnam’s EPR rollout mandates brands to finance downstream purity improvements, mobilizing capex for optics-rich PET and HDPE sorting. South Korea’s 49% increase in plastic waste since 2018, along with a 70% recycling rate goal, bolsters orders for high-throughput belt platforms. Meanwhile, Australia leverages its AUD 200 million (USD 128.64 million) Recycling Modernisation Fund to support local optical-sorter assembly, thereby shortening supply chains.
EMEA and LATAM Optical Sorter MarketEurope sustains steady demand by coupling circular-economy directives with subsidies for textile, WEEE, and fiber-based packaging recovery. ANDRITZ’s automated line in France that classifies garments by fiber composition illustrates how EU funding expands beyond food and beverage into new feedstocks. Latin America and Middle East & Africa remain nascent but strategic, with copper and lithium mines in Chile and Zimbabwe piloting sensor-based pre-concentration to offset declining ore grades and constrained water resources.
Image © Vijeron Intelligence. Reuse requires attribution under CC BY 4.0.
Section 6
Regulatory LandscapeFood safety, machinery safety, and circular-economy compliance are the main regulatory levers shaping optical sorter requirements across regions. In the European Economic Area, the EU Machinery Directive 2006/42/EC anchors conformity assessment for sorting machinery, pushing OEMs and integrators to document risk assessments and align designs with harmonised standards as part of CE marking for installed lines.
In the United States, the FDA Food Safety Modernization Act (FSMA) Preventive Controls framework drives validation, monitoring, and verification when optical sorting is used as a preventive control for hazard mitigation. This strengthens demand for auditable digital defect logs and traceability-ready records, with procurement favoring systems that can demonstrate validated performance and maintain compliance documentation during audits and import inspections.
Section 7
Value Chain AnalysisThe optical sorter value chain starts with upstream component suppliers providing cameras and optical sensors (including NIR and hyperspectral modules), illumination, high-speed ejectors/valves, electronics/PCBs, and compute hardware that supports real-time inference. OEMs (for example, TOMRA, Buhler, Satake, Sesotec, Key Technology, and Hefei Meyer Optoelectronic Technology) combine these inputs into platforms built around feeding/singulation, the detection zone, image processing and AI software, and the separation/ejection system. As hyperspectral costs have fallen and deep-learning models have become embedded at the edge, software and model tuning increasingly sit alongside hardware as a core bill-of-materials and differentiation layer.
Downstream, systems integrators and plant engineering firms adapt sorters to line layouts and hygiene or dust-control requirements, then connect them to plant automation/IIoT for data logging, recipe management, and predictive maintenance. Aftermarket services (spares, calibration tools, model updates, and remote monitoring) capture a growing share of lifetime value, while end users in food processing, recycling, and mining drive specifications around purity, yield, uptime, and compliance reporting. That, in turn, supports demand for modular architectures that can be retrofitted rather than fully replaced.
Section 8
Competitive Landscape
Global leadership rests with TOMRA, Bühler, Key Technology, and Sesotec, whose combined portfolio spans cameras, NIR, X-ray, and data analytics. These players integrate AI inference engines; TOMRA’s GAINnext detects over 95% of opaque plastic contaminants to safeguard installed bases and increase service revenue. Acquisition remains the primary route to capability expansion; TOMRA’s 25% stake in PolyPerception enhances waste-flow monitoring, and Duravant’s Key Technology has absorbed Herbert Solutions to extend its root-crop equipment lines.
Asian challengers reshape price-performance curves. AETECH’s ATron robot, marketed at a 20–30% discount to its European counterparts, achieves 99.3% accuracy and operates in 13 Korean plants, underscoring how home-grown AI technology helps narrow performance gaps. Chinese OEMs are exporting belt sorters, bundled with cloud analytics, at aggressive financing terms, capturing small- to mid-sized recycling sites that previously relied on manual triage.
Competitive differentiation now hinges on full-suite offerings, including hardware, adaptive firmware, cloud dashboards, and predictive maintenance services. Vendors that master sensor fusion and data valorization secure multiyear service contracts, raising switching costs for operators. Conversely, markets with commodity-grade requirements bulk grain cleaning or quartz sorting remain price sensitive, enabling lower-cost suppliers to win share on capex efficiency.
Optical Sorter Industry Leaders* TOMRA Systems ASA
- Eagle Vizion Inc.
- Key Technology Inc. (A Duravant LLC)
- Hefei Meyer Optoelectronic Technology Inc.
- Machinex Industries Inc.
- *Disclaimer: Major Players sorted in no particular order
Image © Vijeron Intelligence. Reuse requires attribution under CC BY 4.0.Optical Sorter Market Companies Covered in this Report* TOMRA Systems ASA
- Buhler Group
- Key Technology Inc. (Duravant LLC)
- Hefei Meyer Optoelectronic Technology Inc.
- Satake Corporation
- Sesotec GmbH
- Cimbria A/S (AGCO Corporation)
- Machinex Industries Inc.
- Pellenc ST
- Eagle Vizion Inc.
- Raytec Vision S.p.A
- Steinert GmbH
- National Recovery Technologies Inc.
- Binder+Co AG
- Angelon Electronics Co. Ltd.
- Techik Instrument Co. Ltd.
- Hefei Baite Optoelectronic Technology Co. Ltd.
- Bhler Sortex Limited
- Bollegraaf Group
- Colour Sorting Group (CSG)
Read Analysis of Optical Sorter Companies
Section 9
Market Opportunities and Future Outlook
A clear whitespace is emerging where operators need higher-purity outcomes with fewer changeover disruptions, particularly in recycling and high-care food lines that require auditable performance logs. TOMRA Recycling expanded its GAINnext ecosystem in 2026 through an AI-native platform approach and new deep-learning applications focused on food-grade PET tray sorting and higher-throughput used beverage can (UBC) aluminum recovery. This highlights how OEM roadmaps are moving toward software-defined upgrades that can be deployed across installed hardware, creating room for vendors and integrators to package outcome-oriented offers (performance monitoring, model updates, and validation support) rather than selling standalone machines.
In food processing, opportunities cluster around hygienic, washdown-ready platforms and reduced false rejects, where product-specific solutions shorten commissioning time across multiple SKUs. In 2026, Key Technology introduced its COMPASS optical sorter for fresh and IQF vegetables with a hygienic design and Pixel Fusion detection, and TOMRA Food debuted the TOMRA 4C at Interpack 2026 with LUCAi-based deep learning aimed at lowering false reject rates in nuts and IQF products. Together, these launches reinforce a pathway for multi-sensor fusion (visible plus NIR/hyperspectral) and automated calibration capabilities, aligning with end-user priorities for labor substitution, faster changeovers, and compliance-ready inspection records.
Section 10
Recent Industry Developments in Optical Sorter Market* May 2026: TOMRA Food debuted the TOMRA 4C optical sorter at Interpack 2026, combining LUCAi deep learning with machine learning to reduce false rejects in demanding applications such as nuts and IQF products. The launch strengthens the push toward software-led performance gains on high-throughput belt systems and supports processors that need consistent quality with fewer manual inspectors.
- June 2025: Pellenc ST outfitted a Norwegian PET facility designed to process 14,000 tons per year at 99% clear-PET purity. This type of high-purity reference installation raises competitive benchmarks for rPET lines operating under tighter recycled-content and quality requirements.
- April 2024: TOMRA acquired a 25% stake in PolyPerception to expand AI-based waste-flow analytics that complement optical sorting. The move deepened access to data and model capabilities that enhance sorter accuracy and supports a broader shift toward connected, insight-driven sorting operations.
Section 11
Table of Contents for Optical Sorter Industry Report1. INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
- RESEARCH METHODOLOGY
- EXECUTIVE SUMMARY
- MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers* 4.2.1 Automation Demand for High-Throughput Sorting in Large-Scale Food Processing Plants Across North America
- 4.2.2 Tightening Global HACCP and EU Food-Hygiene Regulations Elevating Adoption of Optical Sorting
- 4.2.3 Labor Shortages and Wage Inflation Accelerating Automation Investments in European Recycling Facilities
- 4.2.4 Declining Ore Grades in Copper and Lithium Mines Triggering Sensor-Based Pre-Concentration in South America
- 4.2.5 Extended Producer Responsibility (EPR) Mandates Boosting High-Purity Plastic Flake Sorting in Asia
- 4.2.6 AI-Driven Hyperspectral Imaging Breakthroughs Expanding Addressable Use-Cases Beyond Color Sorting
- 4.3 Market Restraints* 4.3.1 High CapEx for Hyperspectral and X-ray Systems Limiting Penetration in SME Grain Mills
- 4.3.2 Frequent Calibrations Elevate Downtime Cost in Continuous-Flow Mining Operations
- 4.3.3 Limited Availability of Skilled Vision Engineers in Developing Regions
- 4.3.4 Data Security Concerns Around Cloud-Connected Sorting Lines
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Outlook
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis* 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Technology* 5.1.1 Cameras
- 5.1.2 Lasers
- 5.1.3 NIR Sorters
- 5.1.4 Hyperspectral Cameras
- 5.1.5 X-ray Transmission
- 5.2 By Platform* 5.2.1 Belt
- 5.2.2 Freefall
- 5.2.3 Lane
- 5.2.4 Hybrid
- 5.3 By End-User Industry* 5.3.1 Food Processing
- 5.3.1.1 Fruits and Vegetables
- 5.3.1.2 Grains and Cereals
- 5.3.1.3 Nuts and Dry Fruits
- 5.3.1.4 Meat and Seafood
- 5.3.1.5 Confectionery and Snacks
- 5.3.2 Recycling
- 5.3.2.1 Plastics
- 5.3.2.2 Metals
- 5.3.2.3 Glass
- 5.3.2.4 E-waste
- 5.3.3 Mining
- 5.3.3.1 Coal
- 5.3.3.2 Precious and Base Metals
- 5.3.3.3 Industrial Minerals
- 5.3.4 Other Industries
- 5.4 By Geography* 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 United Kingdom
- 5.4.2.2 Germany
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 India
- 5.4.3.3 Japan
- 5.4.3.4 South Korea
- 5.4.3.5 Australia
- 5.4.3.6 Rest of Asia-Pacific
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 Turkey
- 5.4.5.2 South Africa
- 5.4.5.3 Saudi Arabia
- 5.4.5.4 Rest of Middle East and Africa
- COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)* 6.4.1 TOMRA Systems ASA
- 6.4.2 Buhler Group
- 6.4.3 Key Technology Inc. (Duravant LLC)
- 6.4.4 Hefei Meyer Optoelectronic Technology Inc.
- 6.4.5 Satake Corporation
- 6.4.6 Sesotec GmbH
- 6.4.7 Cimbria A/S (AGCO Corporation)
- 6.4.8 Machinex Industries Inc.
- 6.4.9 Pellenc ST
- 6.4.10 Eagle Vizion Inc.
- 6.4.11 Raytec Vision S.p.A
- 6.4.12 Steinert GmbH
- 6.4.13 National Recovery Technologies Inc.
- 6.4.14 Binder+Co AG
- 6.4.15 Angelon Electronics Co. Ltd.
- 6.4.16 Techik Instrument Co. Ltd.
- 6.4.17 Hefei Baite Optoelectronic Technology Co. Ltd.
- 6.4.18 Bhler Sortex Limited
- 6.4.19 Bollegraaf Group
- 6.4.20 Colour Sorting Group (CSG)
- MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment
Section 12
Optical Sorter Market Report Scope and Research MethodologyMarket Definition and CoverageThe optical sorter market, for this study, covers equipment and integrated systems that use sensors and imaging to detect and separate materials on processing lines, and the value reflects revenues generated from these machines and their core sorting functions.
Scope exclusions: We exclude general material handling equipment that does not perform sensor based detection, and we also exclude plant wide automation that sits outside the optical sorting step.
Segments Covered in This Report By Technology Cameras
- Lasers
- NIR Sorters
- Hyperspectral Cameras
- X-ray Transmission
- By Platform* Belt
- Freefall
- Lane
- Hybrid
- By End-User Industry Food Processing Fruits and Vegetables
- Grains and Cereals
- Nuts and Dry Fruits
- Meat and Seafood
- Confectionery and Snacks
- Recycling* Plastics
- Metals
- Glass
- E-waste
- Mining* Coal
- Precious and Base Metals
- Industrial Minerals
- Other Industries
- By Geography North America United States
- Canada
- Mexico
- Europe* United Kingdom
- Germany
- France
- Italy
- Rest of Europe
- Asia-Pacific* China
- India
- Japan
- South Korea
- Australia
- Rest of Asia-Pacific
- South America* Brazil
- Argentina
- Rest of South America
- Middle East and Africa* Turkey
- South Africa
- Saudi Arabia
- Rest of Middle East and Africa
Data Sources, Market Sizing, and ValidationDesk Research
Desk work started with building a fact base on where optical sorting is used most, and how demand moves with processing capacity. We reviewed public sources such as UN Comtrade trade statistics, USGS mineral commodity summaries, FAOSTAT crop and food output series, Eurostat industrial production indicators, and EPA or equivalent national recycling and waste statistics.
To convert these signals into a usable market model, we also leaned on manufacturer brochures, product catalogs, and non paywalled technical papers that explain sensor types and throughput ranges. Company annual reports, investor presentations, and trusted business press helped validate expansion plans and regional demand direction. Where needed, paid subscriptions for company financials and intelligence, patent databases, and an import and export shipment-level database were used to cross-check supplier activity and adoption themes. These sources are illustrative, and many other public and paid references were also used for data collection, validation, and clarification.
Primary Interviews and Surveys
Primary work focused on interviews and structured surveys with equipment suppliers, system integrators, and end users in food processing, recycling, and mining, since buying cycles and utilization patterns can vary a lot by plant. To reduce blind spots, we checked views across APAC, EMEA, and the Americas, and then we used these inputs to confirm assumptions like typical selling prices, replacement timing, and what share of lines are actually being upgraded in the forecast window.
Distribution of primary research fieldwork respondents
Company type | Respondent position | Region |
Top tier: 39% | CXOs: 18% | APAC: 42% |
Mid tier: 42% | Functional/Unit leaders: 27% | EMEA: 37% |
Smaller Players: 19% | Managers: 55% | Americas: 21% |
Market-Sizing & ForecastingFor market sizing, we first used a top-down approach where processing output and trade flows are translated into an addressable base of sorting lines, which is then adjusted by adoption rates for optical sorting in key industries. Once the demand pool was formed, price bands were applied by technology and platform based on the typical configuration used in each application.
Inputs that mattered in the model included recycling collection volumes and sorting targets, food processing throughput and quality requirements, mining and minerals production trends, typical machine throughput (tons per hour), and replacement cycles tied to wear parts and sensor upgrades. Because some countries do not report all indicators consistently, gaps were handled by using proxy series (for example, production plus net trade) and then normalizing with interview based utilization and penetration checks.
Forecasting relied on scenario analysis supported by a simple multivariate regression on leading indicators like industrial production, recycling volumes, and processed food output, and then the growth path was tuned using expert expectations on capex timing and regulation driven adoption. Selective bottom-up approximations were also used, including sampled ASP times estimated unit shipments for major end uses, and channel feedback on order backlogs, which helped keep totals realistic.
Data Validation & Update CycleValidation was done by triangulating outputs across independent signals, and then running variance checks by region, end use, and technology so outliers could be explained before sign-off. When a step change appeared, such as a sharp price shift or unusually high unit growth, we re-checked the underlying drivers and, when needed, re-contacted sources to confirm what changed in the field.
Before publication, the model and assumptions go through multi step analyst reviews, with logic checks that compare implied units, implied ASP, and implied installed base against realistic operating ranges. Reports are refreshed annually, and interim updates are made if material events occur such as policy changes, large capacity additions, or visible demand shocks. Right before delivery, a final pass is completed so clients receive the most up to date view.
Vijeron Intelligence's Optical Sorter Market Size Measured Against Other Published EstimatesPublished market sizes for optical sorters can look different across sources because the boundaries of what is counted are not always the same, and the timing of the base year can also shift totals. Differences also come from how firms treat platform mix, sensor upgrades, and pricing over time, which can move the value even if unit demand is similar.
Evidence like the stated 2026 to 2031 growth path, along with cross-checks against end-use throughput indicators and platform level adoption feedback, is what ties Vijeron Intelligence to a 2026 market size that is consistent with the sorting demand pool rather than broad automation spending. In practice, some external estimates pull the year earlier and can blend in adjacent sorting equipment categories, and that choice changes the total even before forecasting assumptions are applied.
Benchmark comparison
Source | Market Size | Gaps in Research Methodology |
Vijeron Intelligence | USD 3.74 B (2026) | |
Industry Research Publisher A | USD 2.63 B (2024) | Uses an earlier base year and pricing set, which can understate the effect of recent demand from recycling upgrades and higher specification food lines, and it may reflect a narrower installed base refresh cycle. |
Market Analytics Group B | USD 3.12 B (2024) | Reports a different base year and can be more sensitive to short term capex timing, which can shift totals if replacement demand and multi-sensor upgrades are treated as optional rather than recurring. |
The comparison mainly shows that year selection and what gets counted around upgrades and adjacent equipment can move the headline number by a meaningful amount. By keeping the sizing tied to end-use throughput signals and realistic adoption and price bands, the final value stays traceable to a repeatable set of steps that clients can follow and stress test.
Section 13
Key Questions Answered in the ReportWhat is the current size of the optical sorter market? The optical sorter market stands at USD 3.74 billion in 2026 and is projected to reach USD 5.84 billion by 2031.
Which technology segment is growing the fastest? Near-infrared (NIR) systems are expected to register the highest 11.45% CAGR due to superior material-identification capabilities.
Why are belt platforms so dominant? Belt sorters integrate easily with existing conveyors, handle large throughputs, and now feature AI modules that cut downtime, giving them 54.35% revenue share in 2025.
Which end-user will drive future demand? Recycling plants will be the growth engine, advancing at 10.28% CAGR as EPR policies tighten purity targets for plastics and metals.
Section 14
Related Reports Explore More ReportsAsia Pacific Optical Sensors Market ShareAsia Pacific Sortation Systems MarketEurope Optical Sensors Market AnalysisMarket Trends in North America Optical ImagingNA Optical Sensors Market ReportOptical Imaging MarketOptical Pulse Sensor Market ShareOptical Sensor Market AnalysisSortation Systems Market SizeUS Optical Sensors Market Analysis