Optical Transceiver Market Size & Share Analysis - Growth Trends and Forecast (2026 - 2031)
Optical Transceiver Market Size & Share Analysis - Growth Trends and Forecast (2026 - 2031)
Industry: Technology, Media & Telecom (TMT)
Source: https://www.mordorintelligence.com/industry-reports/optical-transceiver-market
Scraped Date: 2026-09-17
Key Market Estimates
| Variable | Value | Unit |
|---|
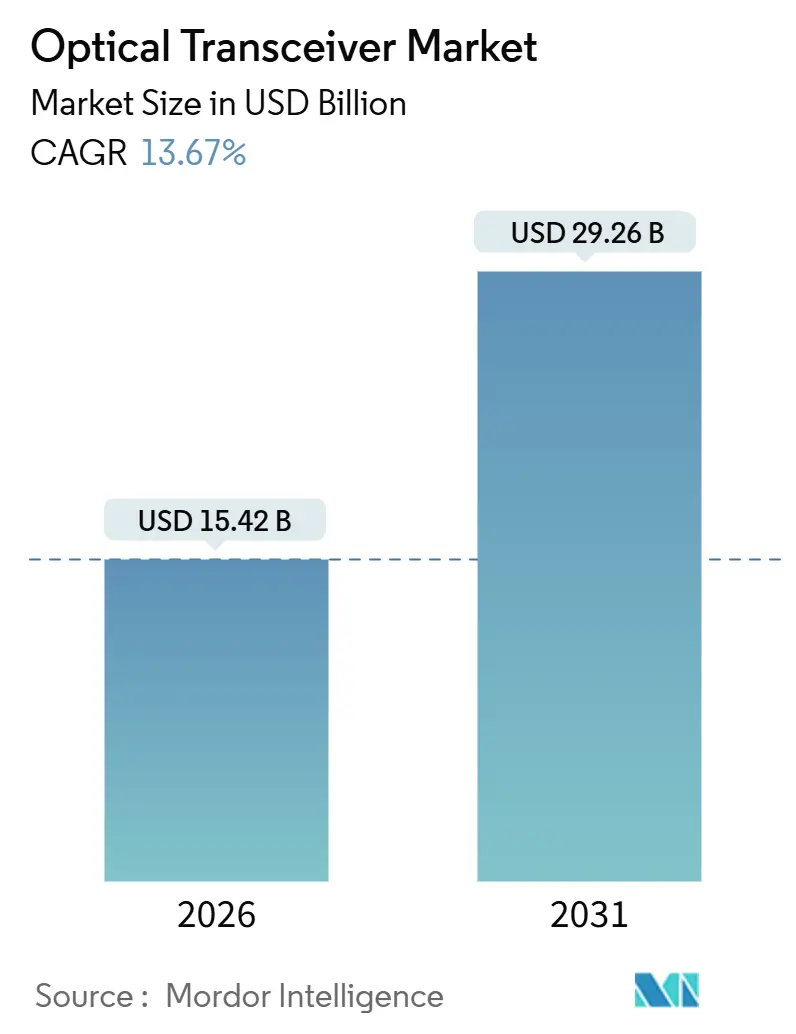
| Market Size (2026) | 15.42 | USD Billion |
|---|
| Market Size (2031) | 29.26 | USD Billion |
|---|
| Growth Rate (2026 - 2031) | 13.67 | PERCENT |
|---|
| Fastest Growing Market | Asia Pacific |
|---|
| Largest Market | North America |
|---|
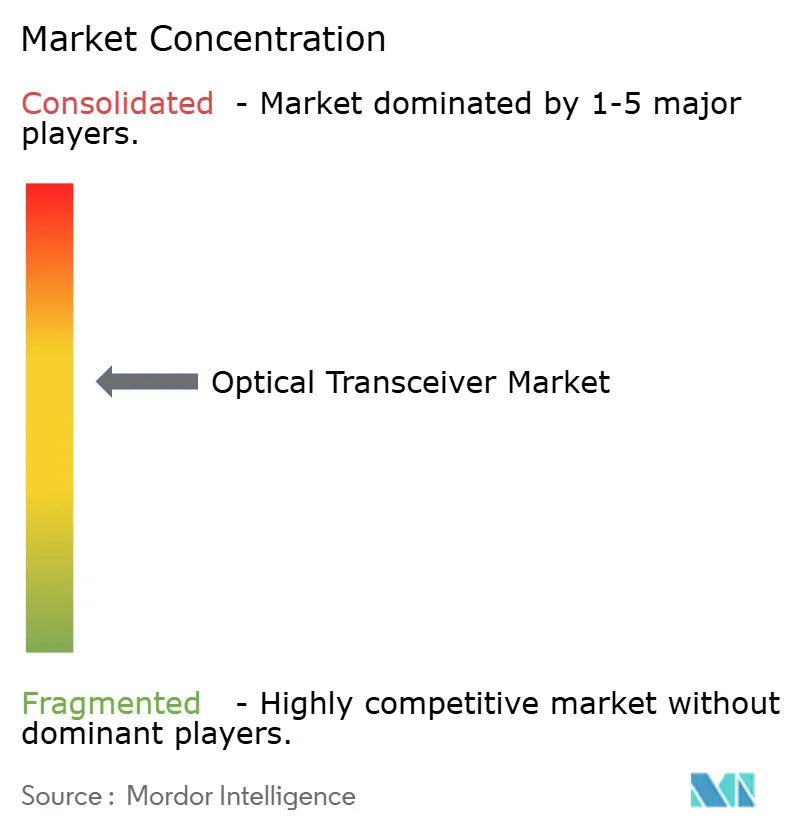
| Market Concentration | Medium |
|---|
Section 1
Optical Transceiver Market Size and ShareMarket OverviewStudy Period | 2020 - 2031 |
Market Size (2026) | USD 15.42 Billion |
Market Size (2031) | USD 29.26 Billion |
Growth Rate (2026 - 2031) | 13.67 % |
Fastest Growing Market | Asia Pacific |
Largest Market | North America |
Market Concentration | Medium |
Major Players*Disclaimer: Major Players sorted in no particular order
Image © Vijeron Intelligence. Reuse requires attribution under CC BY 4.0.
Image © Vijeron Intelligence. Reuse requires attribution under CC BY 4.0.
Section 2
Optical Transceiver Market Analysis by Vijeron IntelligenceThe optical transceiver market size reached USD 15.42 billion in 2026 and is projected to climb to USD 29.26 billion by 2031, reflecting a brisk 13.67% CAGR. The growing adoption of 400G and 800G Ethernet, the spread of artificial-intelligence clusters, and the rise of edge micro-data centers are reshaping demand patterns. Hyperscale operators are driving volume through dual-sourcing strategies that reward vendors meeting stricter power and thermal budgets. Carrier spending is shifting toward coherent wavelength-division multiplexing that maximizes spectral efficiency on constrained fiber pairs, while enterprise buyers continue incremental upgrades from 10G to 100G links. At the same time, Chinese vertically integrated suppliers are compressing bill-of-material costs by bundling lasers, modulators, and photodetectors on a single substrate, intensifying competitive pressure on incumbents.
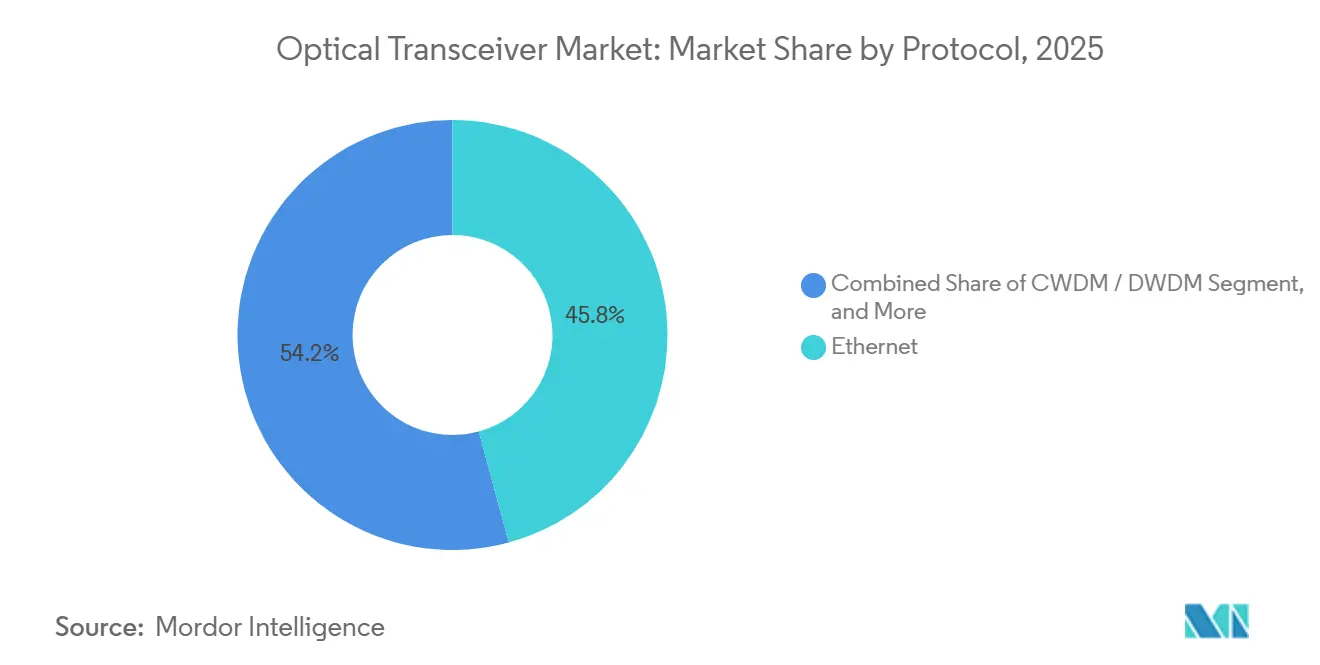
Key Report Takeaways* By protocol, Ethernet led with 45.79% of the optical transceiver market share in 2025, while coherent DWDM modules are projected to expand at a 14.88% CAGR through 2031.
- By data rate, the 100-400 Gbps band captured 39.16% of the market in 2025, while modules above 400 Gbps are set to grow at a 14.69% CAGR through 2031.
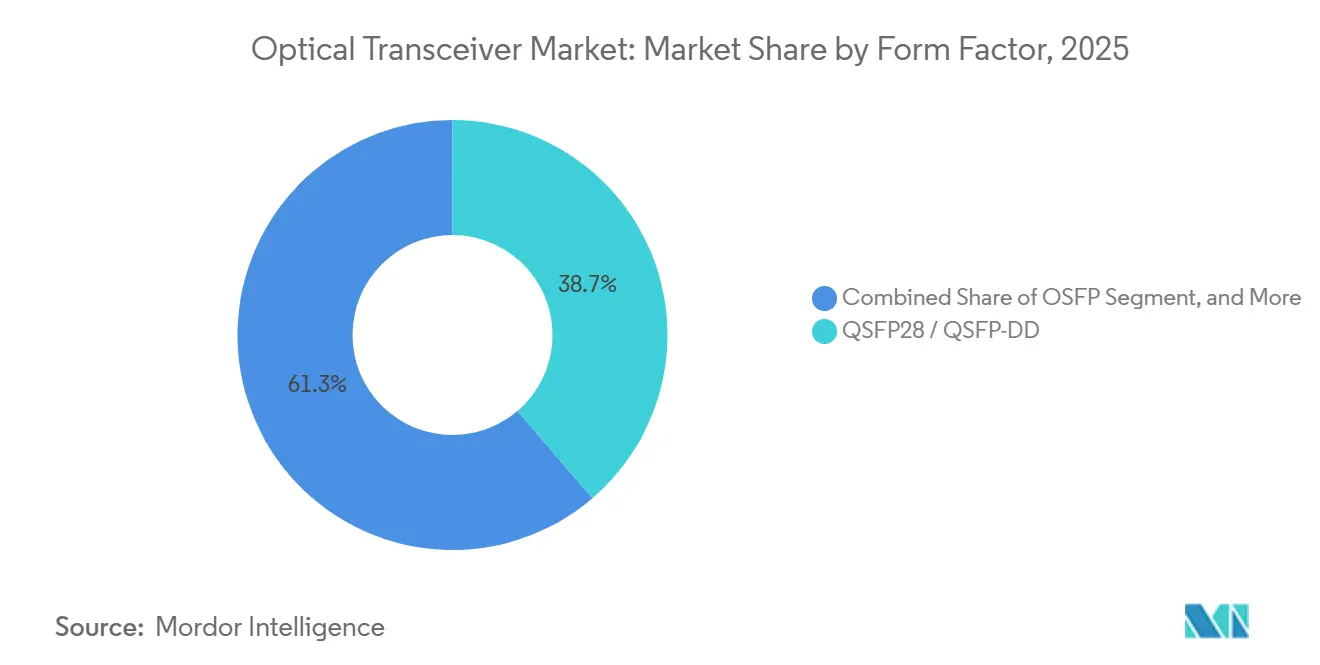
- By form factor, QSFP28 and QSFP-DD devices held 38.72% share in 2025, while OSFP packages are on course for a 14.83% CAGR to 2031.
- By fiber type, single-mode optics dominated with 62.37% of the optical transceiver market share in 2025, while multi-mode variants are forecast to advance at a 14.27% CAGR through 2031.
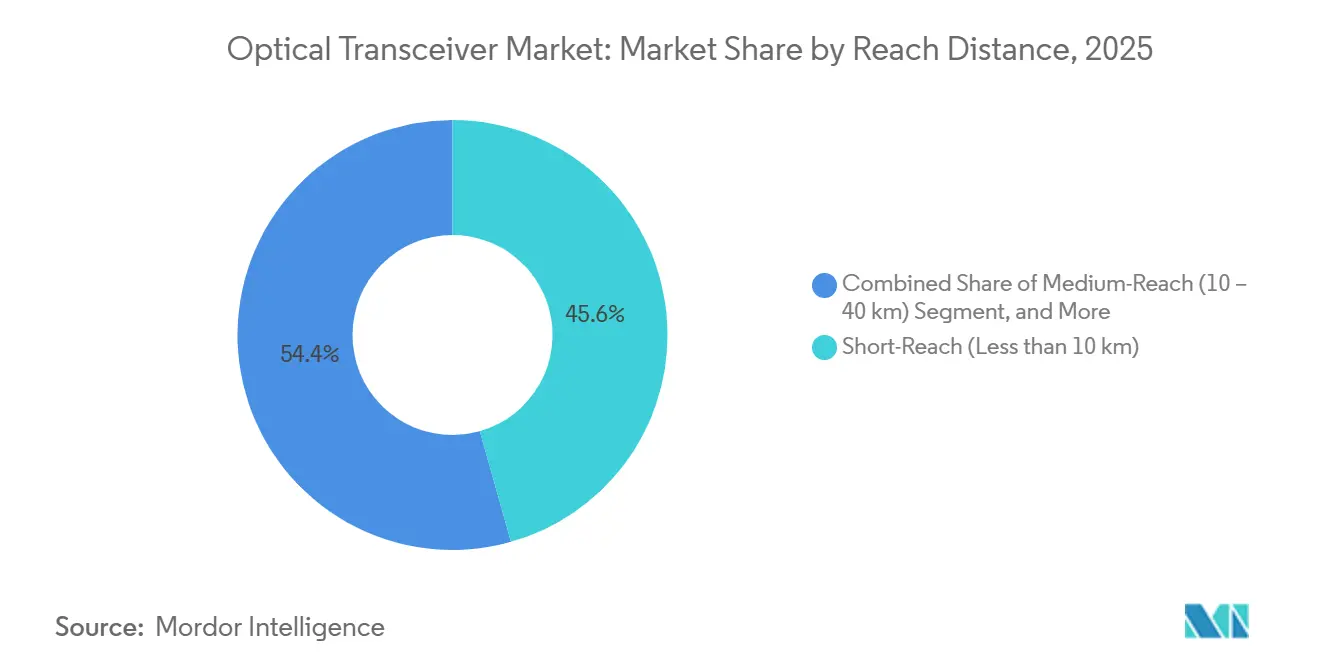
- By reach distance, short-reach modules commanded 45.61% of the optical transceiver market share in 2025, while medium-reach designs are poised for a 14.21% CAGR through 2031.
- By application, data centers led with a 55.82% revenue share in 2025 and are projected to grow at a 14.43% CAGR through 2031.
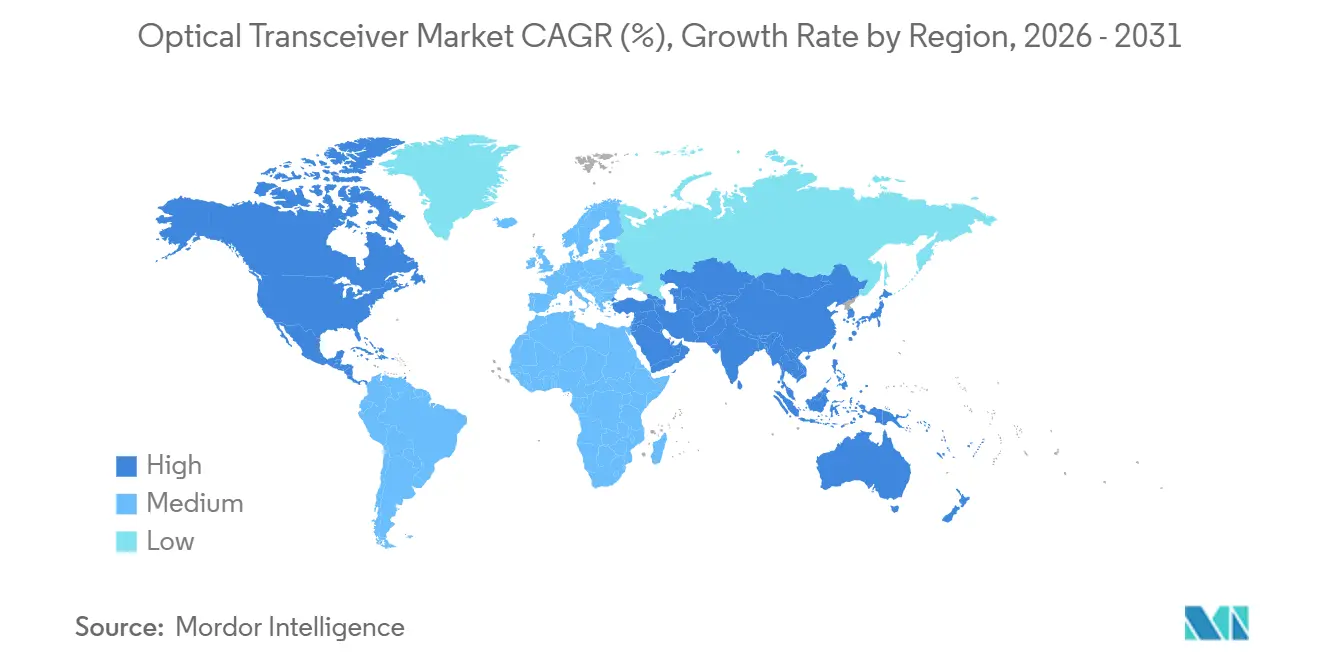
- By geography, North America accounted for 33.91% of 2025 revenue, while Asia-Pacific is projected to expand at a 14.66% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using Vijeron Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Section 3
Market Trends and InsightsDrivers Impact Analysis of Optical Transceiver Market*Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
Hyperscale Data-Center Expansion | +3.2% | Global, concentrated in North America and Asia-Pacific | Medium term (2-4 years) |
Migration to 400G and 800G Ethernet | +3.5% | Global, led by North America hyperscalers | Medium term (2-4 years) |
5G Fronthaul and Backhaul Fiber Build-Out | +2.1% | Asia-Pacific core, Europe and Middle East secondary | Short term (≤ 2 years) |
Growing Cloud AI/ML Clusters Adopting CPO | +2.4% | North America and Asia-Pacific | Long term (≥ 4 years) |
Temperature-Hardened Modules for LEO Satellites | +0.8% | Global, early adoption in North America and Europe | Long term (≥ 4 years) |
Rise of Linear Pluggable Optics | +1.7% | Global, strongest in North America data centers | Short term (≤ 2 years) |
Source: Vijeron Intelligence |
Hyperscale Data-Center ExpansionRecord capital expenditures by Meta, Google, Microsoft, and Amazon Web Services are lifting unit volumes for 400G and 800G modules, as each graphics processing unit in training clusters demands multiple high-speed links.[1]Meta Platforms, “Meta Reports Fourth Quarter and Full Year 2024 Results,” investor.fb.com Operators are standardizing on OSFP packages to unlock additional thermal headroom. Rapid scaling places pressure on suppliers to deliver lower power per bit, which, in turn, accelerates innovation in silicon photonics integration. Inter-availability-zone fabrics that rely on 400ZR and 800ZR coherent interfaces further boost demand for metro-reach pluggables. As hyperscalers move inference workloads closer to end users, short-reach linear optics are also gaining favor to minimize energy draw inside racks.
Migration to 400G and 800G EthernetThe IEEE 802.3df standard finalized 800 Gbps physical layers, setting the stage for mainstream deployments. Broadcom shipped more than 500,000 800G-capable switch ASICs in 2024, confirming that price points have fallen below key adoption thresholds.[2]Broadcom Inc., “Broadcom Announces Fourth Quarter and Fiscal Year 2024 Financial Results,” investors.broadcom.com The Optical Internetworking Forum’s 800ZR specification allows operators to light 120 km metro spans without external transponders, cutting the total cost of ownership by roughly one-quarter. Early field trials show revenue-grade performance, prompting carriers to pull forward upgrade roadmaps. Module vendors able to package 8 × 100 Gbps electrical lanes and advanced forward-error correction inside an air-cooled envelope are best positioned to win design slots.
5G Fronthaul and Backhaul Fiber Build-OutChina Mobile alone has installed more than 4 million 25 Gbps transceivers for 5G fronthaul links.[3]China Mobile Ltd., “Annual Report 2024,” chinamobileltd.com ITU-T Recommendation G.698.4 defines wavelength parameters for multiplexing 16 radio units onto a single fiber pair, reducing demand for single-mode modules in dense urban corridors. Ericsson and Nokia have both introduced temperature-hardened pluggables that operate from −40 °C to +85 °C, a prerequisite for outdoor radios. In backhaul, 100G and 200G coherent pluggables aggregate multiple cell sites onto fewer wavelengths, reducing amplifier count and fiber leasing costs. The net result is a steady pull for medium-reach optics across Asia-Pacific and emerging markets.
Growing Cloud AI/ML Clusters Adopting CPOAyar Labs shipped optical I/O chiplets that bond directly onto compute substrates, eliminating electrical retimers and lowering power budgets by several watts per 100 Gbps. Nvidia’s roadmap signals co-packaged optics on future NVLink fabrics, unlocking 1.6 Tbps per lane and slashing serialization latency. Corning qualified ultra-low-loss multicore fiber with sub-0.15 dB connector losses, safeguarding link budgets inside thermally constrained enclosures. Early hyperscale pilots show a 30% reduction in rack-level energy consumption compared to pluggable alternatives. Successful commercialization is likely to redirect a share of intra-data-center volume away from classic transceiver vendors toward switch and GPU makers.
Restraints Impact Analysis of Optical Transceiver Market*Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
High Power Consumption of greater than 800G Modules | -2.1% | Global, concentrated in North America and Asia-Pacific | Short term (≤ 2 years) |
CAPEX Burden to Upgrade Legacy Fiber Plants | -1.8% | Europe and South America, secondary in Africa | Medium term (2-4 years) |
Laser-Diode and DSP Supply Constraints | -1.4% | Global, acute in Asia-Pacific manufacturing hubs | Short term (≤ 2 years) |
IP Licensing Barriers for Second-Source Vendors | -0.9% | Asia-Pacific and emerging markets | Long term (≥ 4 years) |
Source: Vijeron Intelligence |
High Power Consumption of greater than 800G ModulesAn 800 Gbps OSFP can dissipate 50 W, and a fully populated top-of-rack switch with eight such modules approaches 800 W, pushing the limits of air cooling. Liquid cooling adds USD 500-1,000 per rack, stretching payback periods for operators on tight budgets. The Open Compute Project set a 15 W per 100 Gbps ceiling, a target that current designs exceed by up to 40%. While linear pluggable optics cut draw to roughly 12 W, their 2 km reach confines them to campus or single-site fabrics. Prolonged qualification cycles, now trending at nine months, slow revenue recognition for smaller vendors.
CAPEX Burden to Upgrade Legacy Fiber PlantsUpgrading from G.652.D to G.654.E fiber can cost USD 50,000-100,000 per route-kilometer in dense urban settings. Several Tier-2 carriers deferred long-haul builds, overlaying an additional 100 Gbps of wavelengths rather than adopting 400 Gbps or 800 Gbps coherent optics. Corning’s retrofit connectors reduce insertion loss by 0.3 dB, extending 400 Gbps reach by up to 30 km, yet they still require service interruptions and field labor. Regulatory price caps in Europe limit carriers’ ability to pass costs to wholesale customers, prolonging the life of older gray optics. The resulting bifurcation favors Tier-1 operators that can fund state-of-the-art coherent gear, widening the technology gap.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Section 4
Optical Transceiver Market Segment AnalysisBy Protocol:Ethernet Dominates, Coherent DWDM Gains TractionEthernet accounted for 45.79% of the optical transceiver market share in 2025, reflecting its ubiquity across leaf-spine fabrics and aggregation layers. Coherent DWDM solutions, though smaller today, are forecast to register a 14.88% CAGR through 2031, propelled by metro and long-haul operators extending 400ZR and 800ZR pluggables into production. InfiniBand retains a niche in high-performance computing where RDMA latency is critical, while Fibre Channel evolves to Gen 7 speeds in storage-area networks. Passive optical network modules remain essential in broadband rollouts, particularly where regulators mandate fiber-to-the-home coverage.
Ethernet’s breadth spans 25G campus uplinks to 800G hyperscale backbones, creating economies of scale that depress per-port pricing. Coherent DWDM climbs faster because carriers see spectral efficiency gains of 25-40% compared with discrete transponders. InfiniBand’s roadmap toward 1.6 Tbps EDR maintains a performance moat that justifies premium pricing. Fibre Channel’s carefully staged bandwidth jumps keep backward compatibility for mission-critical SANs. PON optics monetize civil works already sunk into last-mile fiber, giving suppliers a stable revenue stream even as data center spending fluctuates.
Image © Vijeron Intelligence. Reuse requires attribution under CC BY 4.0. By Data Rate:Sub-400G Matures, Beyond-800G EmergesTransceivers between 100 Gbps and 400 Gbps held a 39.16% share in 2025, underpinned by QSFP28 and QSFP-DD volumes. The optical transceiver market for modules above 400 Gbps is on track for a 14.69% CAGR, aided by IEEE 802.3df and the forthcoming 802.3dj frameworks. Below 40 Gbps, shipments stabilize as enterprises sweat legacy assets rather than undertake wholesale upgrades.
Cost curves for 400 Gbps have fallen sufficiently that some hyperscalers skip 100 Gbps altogether in new halls. Early engineering samples of 1.6 Tbps pluggables appear in 2026 lab trials, leveraging 200 Gbps electrical lanes. At the opposite end, SFP-based 1 Gbps and 10 Gbps modules still ship in millions to industrial and broadband CPE markets. Overall, the optical transceiver market continues its historical cadence of quadrupling bandwidth every five to six years, with silicon photonics and advanced DSPs extending that trendline.
By Form Factor:QSFP Variants Lead, OSFP AcceleratesQSFP28 and QSFP-DD accounted for 38.72% of the market in 2025, thanks to backward-compatible cages and broad switch support. OSFP is the fastest riser with a projected 14.83% CAGR, because its wider housing accommodates greater thermal mass and 8-lane electrical interfaces at 100 Gbps per lane. Legacy CFP formats are receding as DSP integration enables QSFP-DD and OSFP to match the reach once reserved for bulkier modules.
Operators favor QSFP variants for mixed-speed environments that blend 100 Gbps, 200 Gbps, and 400 Gbps ports. OSFP’s superior airflow path makes it the logical choice at 800 Gbps and above. SFP and SFP+ stay relevant in access switches, industrial controllers, and PON ONTs. The optical transceiver market benefits from the coexistence of multiple form factors, ensuring smooth migration rather than disruptive forklift upgrades.
Image © Vijeron Intelligence. Reuse requires attribution under CC BY 4.0. By Fiber Type:Single-Mode Prevails, Multi-Mode Gains in AI ClustersSingle-mode optics captured a 62.37% share in 2025, sustaining long reaches required by campus, metro, and long-haul links. Multi-mode shipments, however, are forecast to rise at a 14.27% CAGR through 2031 as artificial-intelligence pods adopt cost-optimized intra-row connectivity. OM5 wideband fiber supports 400 Gbps over 150 m, aligning with rack-scale architectures inside hyperscale halls.
Single-mode remains non-negotiable for coherent 400ZR and 800ZR spans where chromatic dispersion must be tightly controlled. Multi-mode excels when the reach is under 100 m, and operators prize lower laser costs. Together, they allow data center designers to right-size links by distance, balancing capital expense and operating power.
By Reach Distance:Short-Reach Dominates, Medium-Reach ExpandsShort-reach modules below 10 km secured 45.61% share in 2025, driven by leaf-spine fabrics and campus cores. Medium-reach optics with 10-40 km reach are advancing at a 14.21% CAGR as edge micro-data centers link suburban locations with regional aggregation points. Long-reach coherent modules remain indispensable for inter-city and submarine routes where spans stretch beyond 1,000 km.
Linear pluggable optics trim power under 2 km while coherent 400ZR collapses metro stages up to 120 km. Operators thus mix reach classes to optimize cost per transported bit. The optical transceiver market rewards suppliers that offer uniform firmware, diagnostics, and thermal envelopes across all distance tiers.
Image © Vijeron Intelligence. Reuse requires attribution under CC BY 4.0. By Application:Data Centers Lead, Telecommunications FollowsData centers held a 55.82% share in 2025 and are on course for a 14.43% CAGR through 2031, fueled by AI training clusters that demand full-bisection bandwidth. Telecommunications ranks second as carriers densify 5G sites and upgrade metro cores with coherent DWDM. Enterprise and campus networks are progressing steadily, migrating from 10 Gbps to 100 Gbps as videoconferencing and SaaS workloads grow. Industrial and other uses grow modestly but require ruggedized modules certified for shock, vibration, and extreme temperatures.
Data-center spending patterns now hinge on accelerator attach rates: every GPU added to a pod multiplies optical port counts. Telecom investment is driven by spectrum scarcity, with 800ZR enabling fiber reuse. Campus buyers' time refreshes around multiyear depreciation cycles, offering vendors a steady counter-cyclical revenue stream.
Section 5
Geography AnalysisNorth America Optical Transceiver MarketNorth America accounted for 33.91% of 2025 revenue, anchored by hyperscale capital outlays exceeding USD 200 billion across 2025-2026. Meta alone plans to deploy over 1 million GPUs, each tied to multiple 400G or 800G links. Amazon Web Services is qualifying co-packaged optics to trim power by roughly 30%, pushing component vendors toward tighter integration. Tier-1 carriers such as AT&T and Verizon have deployed 400ZR in metro rings, eliminating the need for external transponders and reducing provisioning costs. Canada and Mexico contribute incremental volume through rural broadband mandates and early 5G standalone builds.
APAC Optical Transceiver MarketAsia-Pacific is the fastest-growing region, with a 14.66% CAGR projection through 2031. Innolight shipped more than 500,000 400G modules in the first half of 2024, underscoring domestic hyperscale demand. Chinese OEMs ramp 800G QSFP-DD ahead of global peers, while Indian operators deploy tens of thousands of 25G fronthaul modules during nationwide 5G rollouts. Japan, South Korea, and Australia press forward with coherent upgrades in core networks, often leapfrogging 100 Gbps stages entirely.
EMEA and South America Optical Transceiver MarketEurope grows at a moderate pace, constrained by wholesale access price caps but bolstered by submarine cable projects that specify 800 Gbps coherent optics. Deutsche Telekom connected 10 million premises to FTTH by year-end 2024, driving demand for XGS-PON transceivers. The Middle East pursues sovereign cloud builds, with UAE and Saudi operators lighting 400G metro rings. South America faces currency pressure yet relies on FTTH deployments in São Paulo and Buenos Aires to sustain PON volumes. Africa remains nascent, with South African and Nigerian carriers prioritizing open-RAN fronthaul optics.
Vijeron Intelligence provides coverage of the optical transceiver market across other key regional markets. Detailed country-level analysis extends to Brazil incorporating local coverage and market participation, as required.
Section 6
Regulatory LandscapeOptical transceiver commercialization is shaped more by equipment-authorization rules and interoperability standards than by product-specific licensing. In the United States, the Federal Communications Commission (FCC) adopted a final rule in May 2026, effective June 15, 2026, to strengthen the integrity of its Equipment Authorization Program, including a fast-track priority review pathway for devices tested in Trusted Test Labs. This increases the importance of qualified measurement facilities and documentation discipline for vendors shipping optics embedded in telecom equipment.
Standards activity continues to set de facto compliance baselines for module capability and network acceptance. China’s Ministry of Industry and Information Technology (MIIT) issued YD/T 7041.2-2026, which standardizes how optical transceiver modules describe software and hardware material information, supporting traceability expectations in procurement. On the technical side, ITU-T actions in 2025 such as Amendment 4 to G.709/Y.1331 (OTN interface signals) and guidance for very high-speed PON systems above 50 Gbit/s per wavelength, along with OIF interoperability work (including 800ZR plugfest outputs) and the OCI Consortium’s 200G Optical Compute Interconnect Line Interface Specification v1.0 (March 2026), collectively influence qualification checklists used by hyperscalers and carriers for 400ZR/800ZR and emerging 200G/lane platforms.
Section 7
Value Chain AnalysisThe optical transceiver value chain covers raw and epitaxial materials (InP, GaAs), photonic die (lasers such as EMLs/DFBs, modulators, photodiodes), electronics (drivers, TIAs, microcontrollers, and especially high-speed DSPs), module manufacturing (optical sub-assemblies, advanced packaging, and final test), and channel delivery into systems sold to hyperscale data centers, telecom carriers, and enterprise and campus buyers. At the module layer, vendors differentiate through integration approaches (InP, silicon photonics, VCSEL-based links) and form-factor execution (QSFP-DD, OSFP, coherent pluggables), while large buyers typically enforce multi-sourcing and uniform diagnostics and firmware requirements.
Chokepoints in the chain concentrate in a few high-leverage inputs and capabilities: supply of high-speed lasers (notably EML classes used in many datacom links), access to merchant coherent and PAM-4 DSP roadmaps, and advanced packaging and test capacity for higher-lane-count optics and emerging co-packaged and near-package architectures. 2026 announcements reflect a shift toward localized capacity and tighter vertical coordination. NVIDIA disclosed a multi-year partnership with Coherent that includes a USD 2 billion investment for R&D and US-based manufacturing capacity, and Coherent broke ground on an expanded Sherman, Texas manufacturing facility supported by a USD 50 million CHIPS Act grant plus USD 17 million in Texas incentives. Lumentum also announced plans for a 240,000-square-foot manufacturing facility in Greensboro, North Carolina to produce InP-based lasers, underscoring that component supply security is becoming as important as module assembly scale.
Section 8
Competitive Landscape
The five largest suppliers, Coherent Corp., Lumentum, Broadcom, Accelink, and Innolight, captured roughly 50% of 2025 revenue, signaling a moderately concentrated field. Silicon-photonics leaders exploit captive fabs to compress cycle times for 800G and 1.6 Tbps modules, while vertically integrated Chinese peers leverage scale to price 20-25% below Western incumbents. Hyperscalers mitigate vendor risk by certifying at least three sources per speed grade, forcing challengers to meet identical power, thermal, and reliability targets.
Co-packaged optics threatens the pluggable status quo. Broadcom and Nvidia intend to embed photonics directly on switch and GPU substrates, potentially bypassing transceiver vendors inside racks. Patent cross-licensing shapes competitive entry: royalties can reach 8% of the average selling price for firms outside standards consortia, discouraging smaller contenders. Yet white-space areas such as temperature-hardened LEO satellite links, 50G-PON, and linear pluggable optics remain open to agile innovators like POET Technologies and Credo Technology.
Mergers and partnerships reflect a pivot toward vertical integration. Lumentum’s 2025 bookings show 800G coherent modules eclipsing 100G for the first time, validating its early move into indium-phosphide DSP hybrids. Innolight scales 800G QSFP-DD on the back of domestic wafer capacity, shortening lead times for North American cloud imports. Overall, the optical transceiver market balances cost leadership from Chinese entrants with innovation velocity from silicon photonics pioneers.
Optical Transceiver Industry Leaders* Coherent Corp.
- Lumentum Holdings
- Broadcom Inc.
- Accelink Technologies
- Sumitomo Electric Industries
- *Disclaimer: Major Players sorted in no particular order
Image © Vijeron Intelligence. Reuse requires attribution under CC BY 4.0.Optical Transceiver Market Companies Covered in this Report* Coherent Corp.
- Lumentum Holdings
- Broadcom Inc.
- Accelink Technologies
- Sumitomo Electric Industries
- Fujitsu Optical Components
- Source Photonics
- Huawei Technologies
- Cisco Systems (Acacia)
- Innolight Technology
- Hisense Broadband
- Eoptolink Technology
- Applied Optoelectronics
- Marvell Technology
- Credo Technology
- Ciena Corp.
- HUBER+SUHNER Cube Optics
- POET Technologies
- Molex LLC
- Lumentum Holdings Inc.
Section 9
Market Opportunities and Future Outlook
Near-term whitespace is forming around power- and density-driven optical upgrades inside AI-scale data centers, where buyers are pushing beyond 800G toward 1.6T pluggables and, alongside that, evaluating co-packaged and near-package optics to manage thermal envelopes. Standards and interoperability work is translating these needs into purchasing requirements. The OCI Consortium released the 200G Optical Compute Interconnect Line Interface Specification v1.0 (March 2026), and the Optical Internetworking Forum (OIF) launched new projects at its Q2 2026 meeting in Malta, including CMIS-Autonomous Path Start Up (APSU), 1.6T MACsec support guidelines, and a 12.8 Tbps Near-Package Optics (NPO) Implementation Agreement. These efforts widen the addressable design space for suppliers that can provide management and diagnostics consistency (CMIS), security features (MACsec guidance), and interoperability artifacts suitable for hyperscale qualification.
Another clear opportunity centers on supply-chain localization and capacity additions tied to government and operator preferences for resilient sourcing. In 2026, Nokia disclosed a USD 30 million investment to increase optical manufacturing capacity at its Pennsylvania facility by 10x, supported by a USD 10 million CHIPS Act tax credit and a USD 4 million state grant, indicating willingness to fund domestic optical production. Applied Optoelectronics announced a Houston-area footprint expansion to 900,000 square feet (April 2026) and began physical construction in Pearland, Texas in July 2026, adding nearly 400,000 square feet to scale 800G and 1.6T output. Vendors can win share by aligning high-speed product readiness (800G, 1.6T) with verifiable manufacturing scale and traceability that match hyperscaler dual-sourcing and qualification processes.
Section 10
Recent Industry Developments in Optical Transceiver Market* July 2026: Applied Optoelectronics commenced physical construction on two adjacent properties in Pearland, Texas, adding nearly 400,000 square feet of manufacturing space to support 800G and 1.6T transceiver output. The build-out strengthens domestic capacity for high-speed pluggables and supports hyperscaler efforts to diversify sourcing and shorten lead times.
- April 2025: Lumentum announced limited sampling of new 400/800G ZR+ L-band pluggable transceivers and general availability of 800G ZR+ C-band modules. By widening coherent pluggable options across bands, the release supports carrier metro and regional upgrades aimed at increasing fiber capacity without adding external transponders.
- September 2024: Broadcom announced general availability of Sian 2, a 200 Gbps per lane PAM-4 DSP PHY that enables 1.6T optical transceivers. Moving to 200G/lane electronics raises the ceiling for next-generation pluggables and shapes module vendors' roadmaps for OSFP and other high-thermal form factors.
Section 11
Table of Contents for Optical Transceiver Industry Report1. INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
- RESEARCH METHODOLOGY
- EXECUTIVE SUMMARY
- MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers* 4.2.1 Hyperscale Data-Center Expansion
- 4.2.2 5G Fronthaul and Backhaul Fiber Build-Out
- 4.2.3 Migration to 400G and 800G Ethernet
- 4.2.4 Growing Cloud AI / ML Clusters Adopting CPO
- 4.2.5 Temperature-Hardened Modules for LEO Satellites
- 4.2.6 Rise of Linear Pluggable Optics Reducing Power and Cost
- 4.3 Market Restraints* 4.3.1 CAPEX Burden to Upgrade Legacy Fiber Plants
- 4.3.2 Laser-Diode and DSP Supply Constraints
- 4.3.3 High Power Consumption of greater than 800 G Modules
- 4.3.4 IP Licensing Barriers for Second-Source Vendors
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter’s Five Forces Analysis* 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors on the Market
- 4.9 Investment Analysis
- MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Protocol* 5.1.1 Ethernet
- 5.1.2 InfiniBand
- 5.1.3 Fibre Channel
- 5.1.4 CWDM / DWDM
- 5.1.5 FTTx / PON
- 5.1.6 Other Protocols
- 5.2 By Data Rate* 5.2.1 Less than 10 Gbps
- 5.2.2 10 – 40 Gbps
- 5.2.3 40 – 100 Gbps
- 5.2.4 100 – 400 Gbps
- 5.2.5 Greater than 400 Gbps
- 5.3 By Form Factor* 5.3.1 SFP / SFP+
- 5.3.2 QSFP / QSFP+
- 5.3.3 QSFP28 / QSFP-DD
- 5.3.4 CFP / CFP2 / CFP4
- 5.3.5 OSFP
- 5.3.6 Other Form Factors
- 5.4 By Fiber Type* 5.4.1 Single-Mode
- 5.4.2 Multi-Mode
- 5.5 By Reach Distance* 5.5.1 Short-Reach (Less than 10 km)
- 5.5.2 Medium-Reach (10 – 40 km)
- 5.5.3 Long-Reach (Greater than 40 km)
- 5.6 By Application* 5.6.1 Data Centers
- 5.6.2 Telecommunications
- 5.6.3 Enterprise / Campus
- 5.6.4 Industrial and Other Applications
- 5.7 By Geography* 5.7.1 North America
- 5.7.1.1 United States
- 5.7.1.2 Canada
- 5.7.1.3 Mexico
- 5.7.2 Europe
- 5.7.2.1 Germany
- 5.7.2.2 United Kingdom
- 5.7.2.3 France
- 5.7.2.4 Russia
- 5.7.2.5 Rest of Europe
- 5.7.3 Asia-Pacific
- 5.7.3.1 China
- 5.7.3.2 Japan
- 5.7.3.3 India
- 5.7.3.4 South Korea
- 5.7.3.5 Australia
- 5.7.3.6 Rest of Asia-Pacific
- 5.7.4 Middle East and Africa
- 5.7.4.1 Middle East
- 5.7.4.1.1 Saudi Arabia
- 5.7.4.1.2 United Arab Emirates
- 5.7.4.1.3 Rest of Middle East
- 5.7.4.2 Africa
- 5.7.4.2.1 South Africa
- 5.7.4.2.2 Egypt
- 5.7.4.2.3 Rest of Africa
- 5.7.5 South America
- 5.7.5.1 Brazil
- 5.7.5.2 Argentina
- 5.7.5.3 Rest of South America
- COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials as available, Strategic Information, Market Rank / Share for key companies, Products and Services, Recent Developments)* 6.4.1 Coherent Corp.
- 6.4.2 Lumentum Holdings
- 6.4.3 Broadcom Inc.
- 6.4.4 Accelink Technologies
- 6.4.5 Sumitomo Electric Industries
- 6.4.6 Fujitsu Optical Components
- 6.4.7 Source Photonics
- 6.4.8 Huawei Technologies
- 6.4.9 Cisco Systems (Acacia)
- 6.4.10 Innolight Technology
- 6.4.11 Hisense Broadband
- 6.4.12 Eoptolink Technology
- 6.4.13 Applied Optoelectronics
- 6.4.14 Marvell Technology
- 6.4.15 Credo Technology
- 6.4.16 Ciena Corp.
- 6.4.17 HUBER+SUHNER Cube Optics
- 6.4.18 POET Technologies
- 6.4.19 Molex LLC
- 6.4.20 Lumentum Holdings Inc.
- MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment
Section 12
Optical Transceiver Market Report Scope and Research MethodologyMarket Definition and CoverageFor this methodology, the optical transceiver market covers revenue from completed optical transceiver modules that convert electrical signals to optical signals and back, and that are used for fiber-based data links in telecom networks, data centers, and enterprise connectivity.
Scope exclusions: We exclude passive copper direct-attach cables, permanently integrated optics on line cards, and discrete optical sub-assemblies (for example, standalone lasers or drivers) that are sold outside a finished module.
Segments Covered in This Report By Protocol Ethernet
- InfiniBand
- Fibre Channel
- CWDM / DWDM
- FTTx / PON
- Other Protocols
- By Data Rate* Less than 10 Gbps
- 10 – 40 Gbps
- 40 – 100 Gbps
- 100 – 400 Gbps
- Greater than 400 Gbps
- By Form Factor* SFP / SFP+
- QSFP / QSFP+
- QSFP28 / QSFP-DD
- CFP / CFP2 / CFP4
- OSFP
- Other Form Factors
- By Fiber Type* Single-Mode
- Multi-Mode
- By Reach Distance* Short-Reach (Less than 10 km)
- Medium-Reach (10 – 40 km)
- Long-Reach (Greater than 40 km)
- By Application* Data Centers
- Telecommunications
- Enterprise / Campus
- Industrial and Other Applications
- By Geography North America United States
- Canada
- Mexico
- Europe* Germany
- United Kingdom
- France
- Russia
- Rest of Europe
- Asia-Pacific* China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa Middle East Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa* South Africa
- Egypt
- Rest of Africa
- South America* Brazil
- Argentina
- Rest of South America
Data Sources, Market Sizing, and ValidationDesk Research
Desk research starts with mapping where demand is created and where supply is shipped, then we align those signals to avoid counting adjacent products. Public sources are used to anchor the environment, such as ITU and OECD connectivity statistics, FCC filings where relevant for broadband and telecom trends, USITC and UN Comtrade trade data for optics-related flows, and standards bodies such as IEEE and the Optical Internetworking Forum for form-factor and speed roadmaps.
Next, we build a fact base around suppliers and customers using sources like company annual reports, investor presentations, product datasheets, and reputable industry press, which helps check how fast each form factor and data rate is being adopted. Where available, we also use paid subscriptions for company financials and intelligence, patent databases, and shipment-level trade databases to cross-check the direction of shipments and pricing ranges. These examples are not exhaustive, and many other public and paid sources are also used to collect data, validate inputs, and clarify open questions during the study.
Primary Interviews and Surveys
Primary work is used to pressure-test the desk model, especially where published data does not spell out mix shifts between form factors and the timing of new speed ramps. We speak with a mix of module suppliers, component ecosystem participants, distributors, and buyers across data center, telecom, and enterprise connectivity, so assumptions on adoption, pricing movement, and replacement cycles are confirmed in plain terms. Because this is global, our outreach is balanced across APAC, EMEA, and the Americas to capture differences in hyperscale buildouts, 5G transport upgrades, and procurement patterns.
Distribution of primary research fieldwork respondents
Company type | Respondent position | Region |
Top tier: 33% | CXOs: 16% | APAC: 38% |
Mid tier: 50% | Functional/Unit leaders: 39% | EMEA: 37% |
Smaller Players: 17% | Managers: 45% | Americas: 25% |
Market-Sizing & ForecastingThe sizing model uses a top-down demand pool build where fiber access and transport upgrades, data center switching capacity, and network build intensity are translated into transceiver module demand by speed and reach class, then priced using an average selling price path that matches the expected mix. To keep the totals realistic, we corroborate the output with selective bottom-up checks, such as sampled vendor revenue splits, channel discussions on units, and ASP times volume spot checks by major form factors.
Inputs that matter in this market include the rate of 100G, 400G, and 800G port additions, the shift from legacy CFP-family modules to QSFP and OSFP-style modules, the single-mode versus multi-mode mix, and the replacement cadence tied to data center refresh cycles and telecom transport upgrades. Forecasting relies on scenario analysis supported by expert consensus on rollout timing, followed by regression-style sensitivity checks on leading indicators such as data traffic growth and optical port shipment momentum. Where bottom-up views have gaps for private players or unreported channels, we fill them using conservative share ranges and then revisit the assumption during validation calls.
Data Validation & Update CycleValidation is done through cross-checks between the modeled market value and independent signals such as optical port shipment direction, trade flow changes for relevant optics categories, and the pace of speed transitions described by industry participants. Large variances are reviewed, and if a mismatch cannot be explained by mix or pricing, we re-contact sources to confirm whether a step change (for example, a hyperscale ramp or a supply constraint) is being missed.
Before sign-off, the model and assumptions go through multi-step analyst reviews so math, logic, and scope treatment stay consistent across regions and years. Reports are refreshed annually, and interim updates are made when material shifts affect demand, supply, or pricing expectations. Right before delivery, an analyst runs a fresh data pass so clients receive the latest updated view.
Vijeron Intelligence's Optical Transceiver Market Size Measured Against Other Published EstimatesPublished market values for optical transceivers often do not align because each publisher draws the line in a different place and then applies different pricing and adoption assumptions to convert units into revenue. In practice, the biggest differences show up when adjacent products are mixed in, when speed transitions are timed differently, or when currency and inflation timing are handled in a non-uniform way.
The largest gap usually comes from inclusion choices for passive copper interconnects and optics sub-assemblies. In Vijeron Intelligence's estimate, only finished optical transceiver modules are counted, and the mix and ASP movement is adjusted to the pace of 100G to 400G to 800G adoption.
Benchmark comparison
Source | Market Size | Gaps in Research Methodology |
Vijeron Intelligence | USD 15.42 B (2026) | |
Global Consultancy A | USD 11.80 B (2025) | Uses an earlier base year and often blends discrete optics content and adjacent interconnect revenue into one total, which pulls down module-only comparability and shifts the ASP curve. |
Trade Journal B | USD 12.67 B (2024) | Anchors sizing on a 2024 module snapshot and extends forward with a smoother CAGR, which can understate the step-up from rapid 400G and 800G ramps and the related mix-driven pricing changes. |
The spread in published values is mainly explained by what is counted as a transceiver module and by how quickly the model moves from legacy form factors to higher-speed modules. Our approach keeps the scope tied to finished modules and then ties revenue to practical drivers like port adds, fiber mix, and realistic ASP progression, which makes the steps easier to repeat and review.
Section 13
Key Questions Answered in the ReportWhat is the current value of the optical transceiver market and its expected growth by 2031? The market is valued at USD 15.42 billion in 2026 and is forecast to reach USD 29.26 billion by 2031, registering a 13.67% CAGR.
Which protocol segment leads revenue today? Ethernet leads with 45.79% optical transceiver market share in 2025, supported by widespread use across data-center and campus fabrics.
Why are 800 Gbps modules gaining traction in data centers? 800 Gbps optics align with AI cluster bandwidth needs and, when combined with OSFP form factors, provide the thermal headroom hyperscalers require.
Which region is the fastest-growing consumer of optical transceivers? Asia-Pacific is projected to expand at a 14.66% CAGR through 2031, driven by hyperscale buildouts in China and 5G fiber rolls in India.
How are power constraints influencing module design? High draw from 800 Gbps pluggables is spurring adoption of linear pluggable optics and co-packaged approaches that cut watts per bit and ease cooling loads.
What opportunities exist for new entrants? White-space areas include temperature-hardened LEO satellite optics, 50G-PON for dense FTTH, and linear pluggable modules for short-reach AI fabrics.
Section 14
Related Reports Explore More ReportsFiber Optic Cable Market TrendsOptical Interconnect Market SizeOptical Transport Network Market TrendsOptical Wavelength Services Market GrowthPassive Optical Network (PON) Equipment Market ShareMarket Analysis of Physical InternetIndustry Outlook of Submarine Optical Fiber CableSurface Mountable Laser Direct Structuring Antenna (LDS) Market