Stents Market Size & Share Analysis - Growth Trends and Forecast (2026 - 2031)
Stents Market Size & Share Analysis - Growth Trends and Forecast (2026 - 2031)
Industry: Medical Devices & Equipment (Healthcare (Pharma, Medical Devices, Biotech))
Source: https://www.mordorintelligence.com/industry-reports/stents-market
Scraped Date: 2026-09-17
Key Market Estimates
| Variable | Value | Unit |
|---|
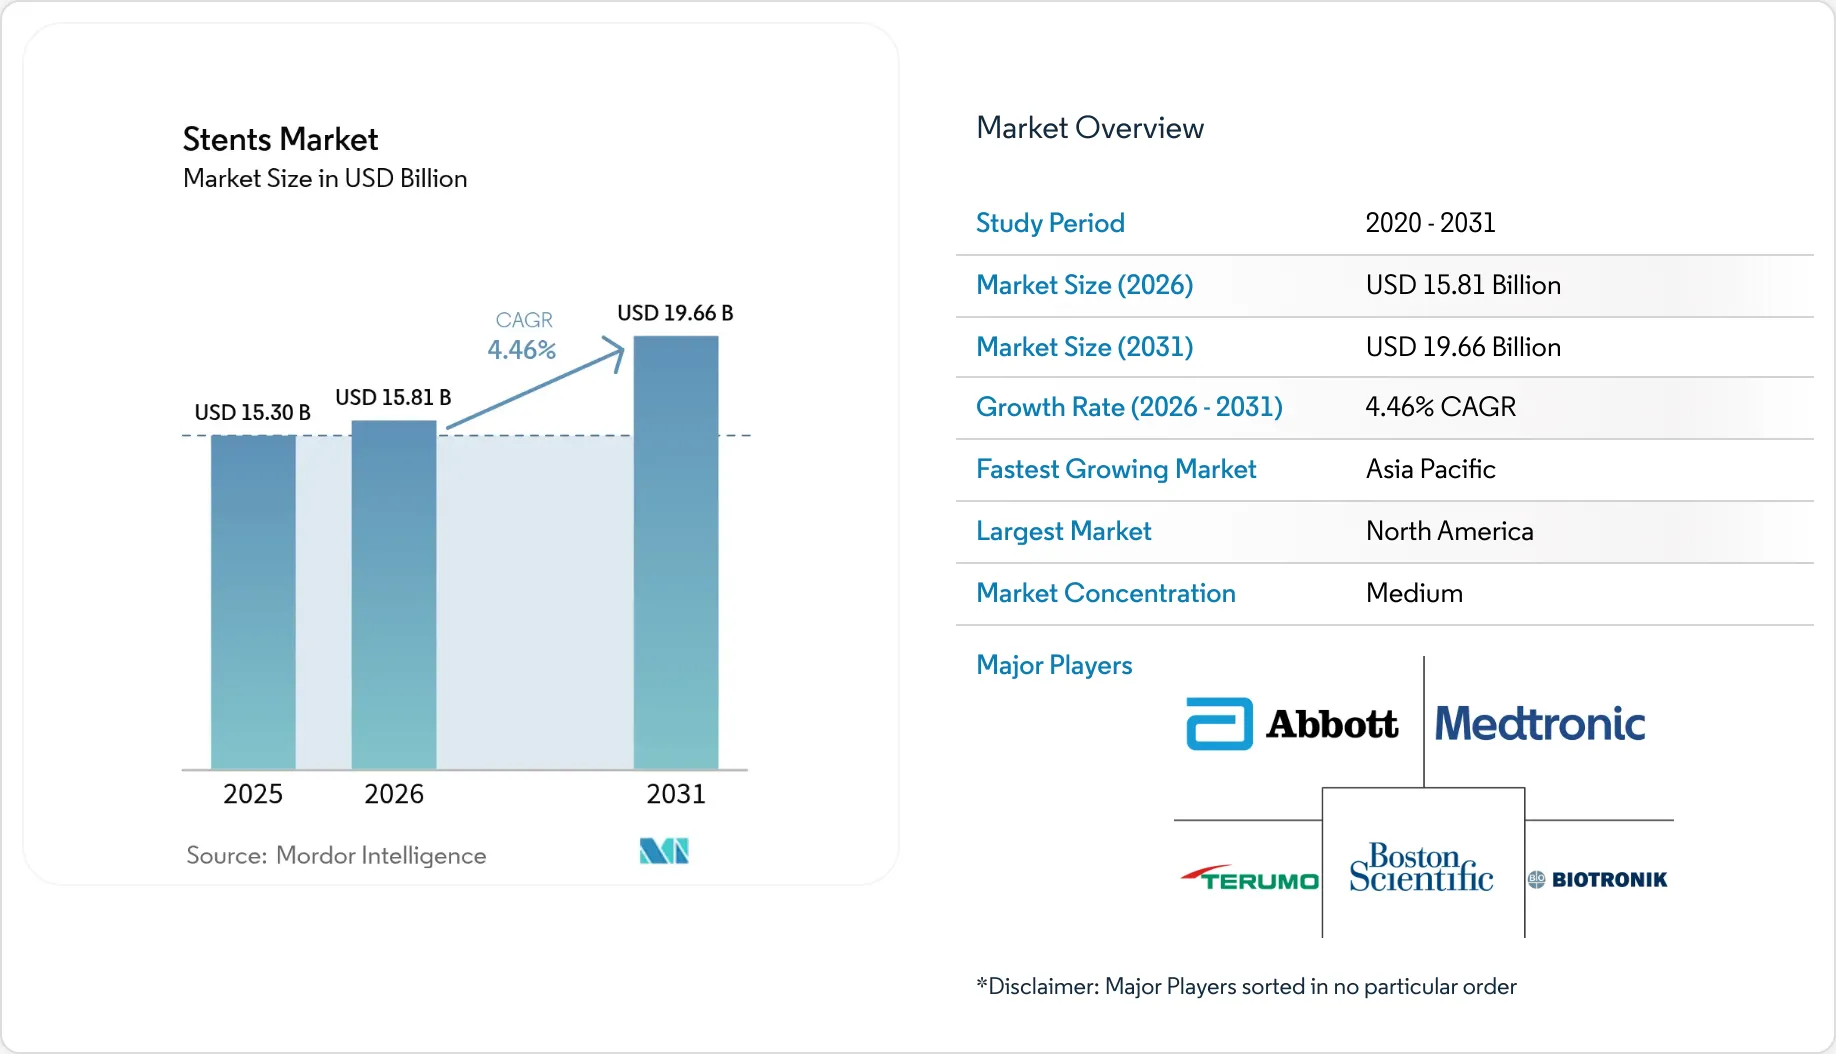
| Market Size (2026) | 15.81 | USD Billion |
|---|
| Market Size (2031) | 19.66 | USD Billion |
|---|
| Growth Rate (2026 - 2031) | 4.46 | PERCENT |
|---|
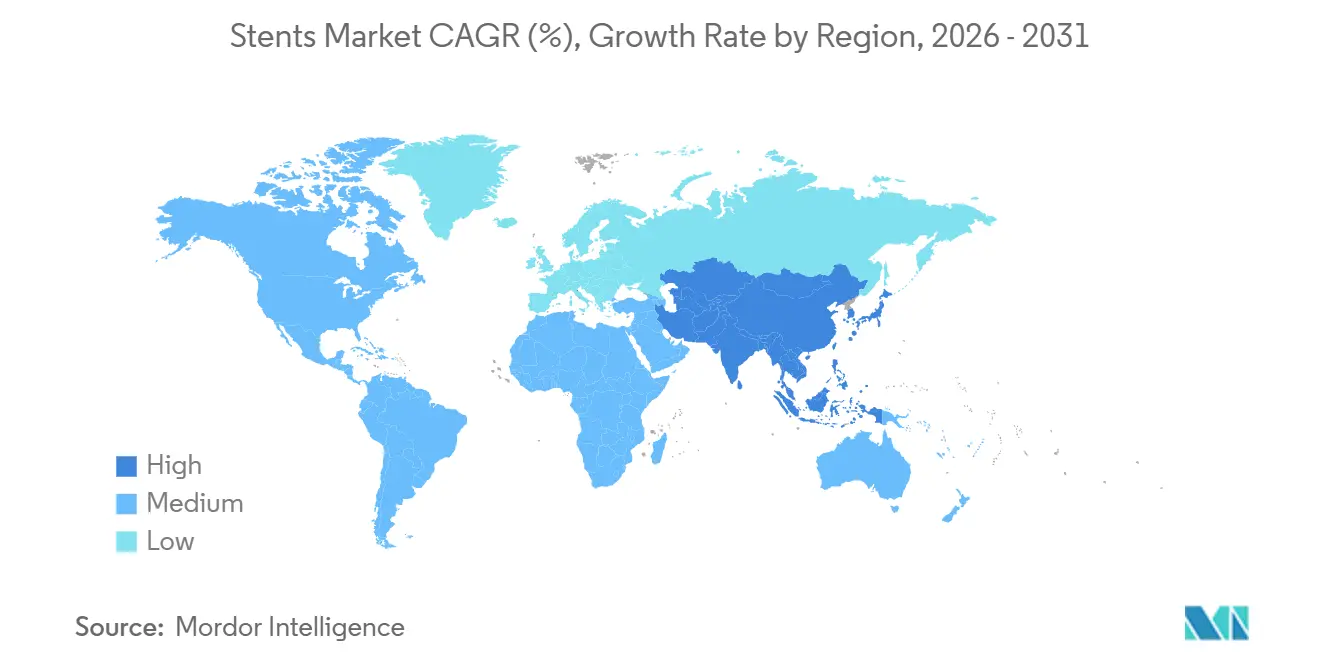
| Fastest Growing Market | Asia Pacific |
|---|
| Largest Market | North America |
|---|
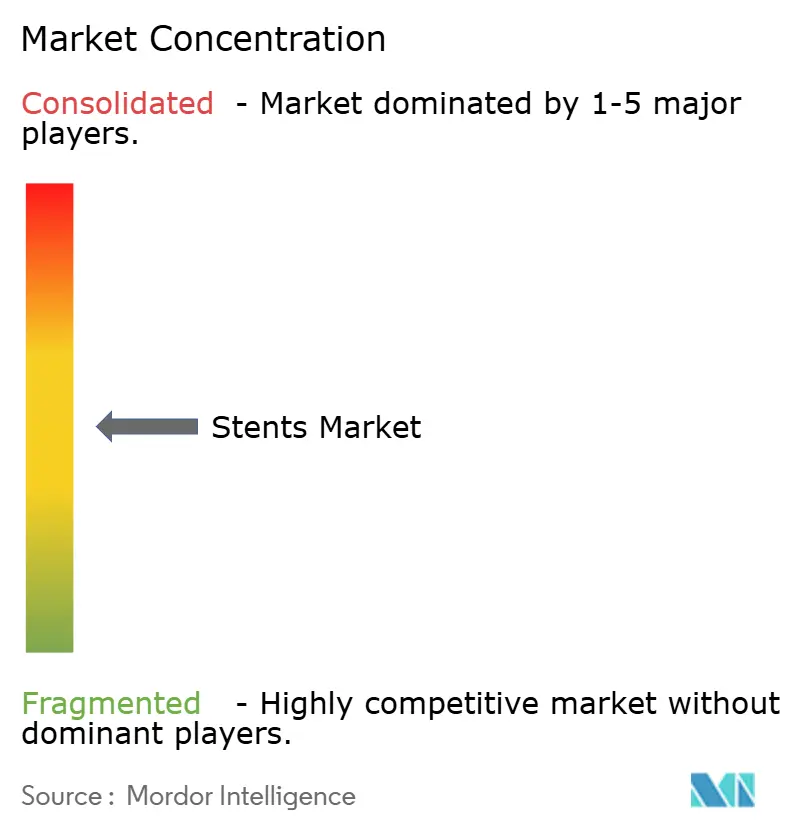
| Market Concentration | Medium |
|---|
Section 1
Stents Market Size and ShareMarket OverviewStudy Period | 2020 - 2031 |
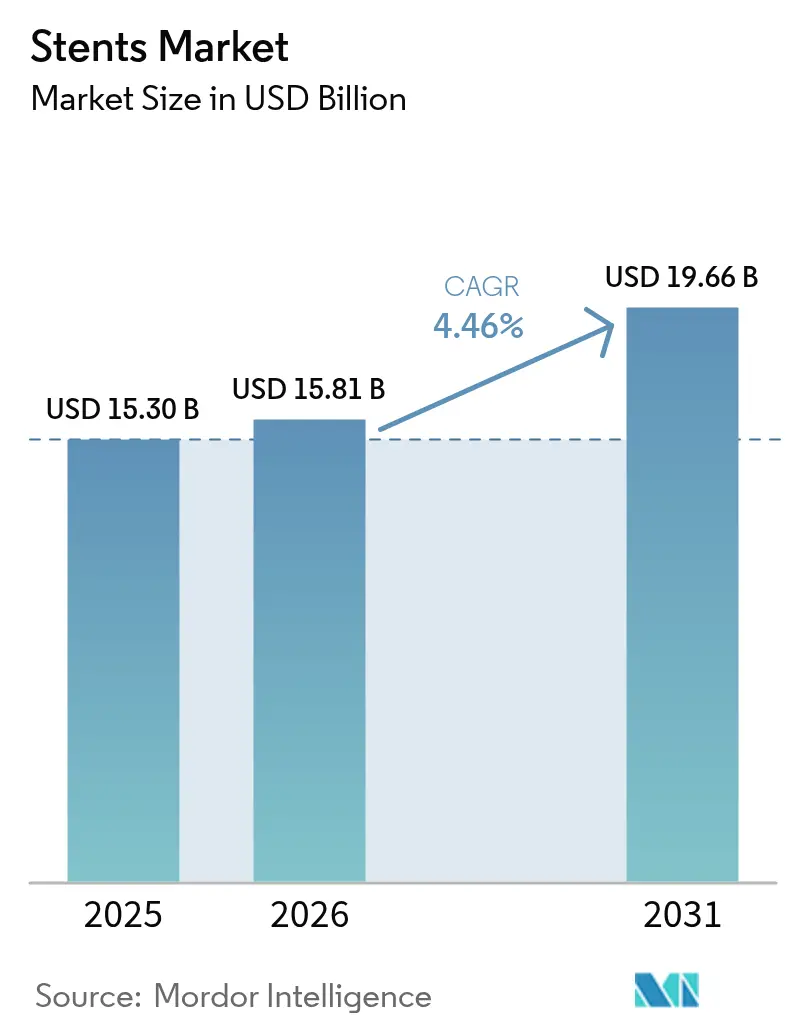
Market Size (2026) | USD 15.81 Billion |
Market Size (2031) | USD 19.66 Billion |
Growth Rate (2026 - 2031) | 4.46 % |
Fastest Growing Market | Asia Pacific |
Largest Market | North America |
Market Concentration | Medium |
Major Players*Disclaimer: Major Players sorted in no particular order
Image © Vijeron Intelligence. Reuse requires attribution under CC BY 4.0.
Image © Vijeron Intelligence. Reuse requires attribution under CC BY 4.0.
Section 2
Stents Market Analysis by Vijeron IntelligenceThe Stents Market size is expected to grow from USD 15.30 billion in 2025 to USD 15.81 billion in 2026 and is forecast to reach USD 19.66 billion by 2031 at 4.46% CAGR over 2026-2031.
Growing procedure volumes in Asia-Pacific, rapid uptake of AI-guided robotic navigation, and renewed confidence in bioresorbable scaffolds are sustaining steady expansion even as global price ceilings pressure margins. Coronary devices dominate today, yet neurovascular flow-diverter and peripheral self-expandable platforms are emerging as the next wave of growth. Materials innovation is accelerating, with thinner cobalt-chromium struts and polymeric resorbable backbones reducing late adverse events. Simultaneously, reimbursement reforms that reward outpatient percutaneous coronary intervention (PCI) are moving a share of implantations from hospitals to ambulatory surgical centers, realigning revenue across the value chain.
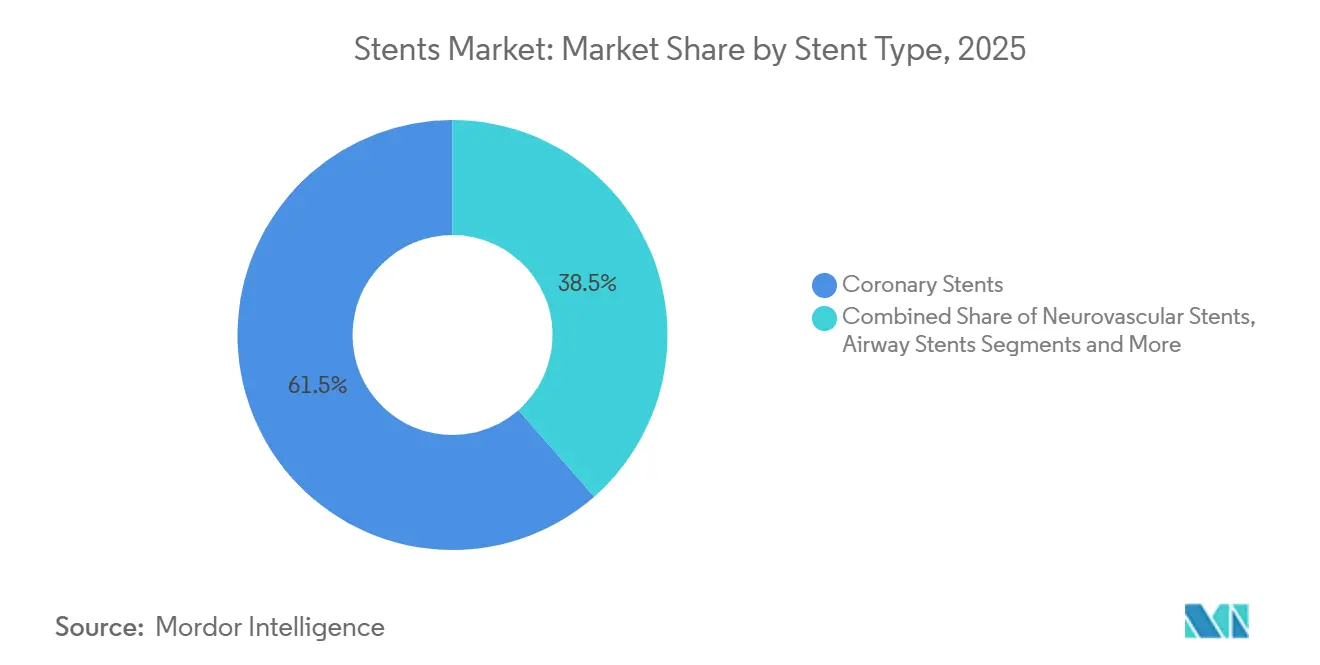
Key Report Takeaways* Coronary stents accounted for 61.46% of the 2025 stents market share, while neurovascular devices are forecast to post the fastest 8.46% CAGR through 2031.
- Metallic biomaterials held 63.68% of the 2025 mix; polymeric scaffolds are projected to rise at a 7.56% CAGR as bioresorbable platforms gain traction.
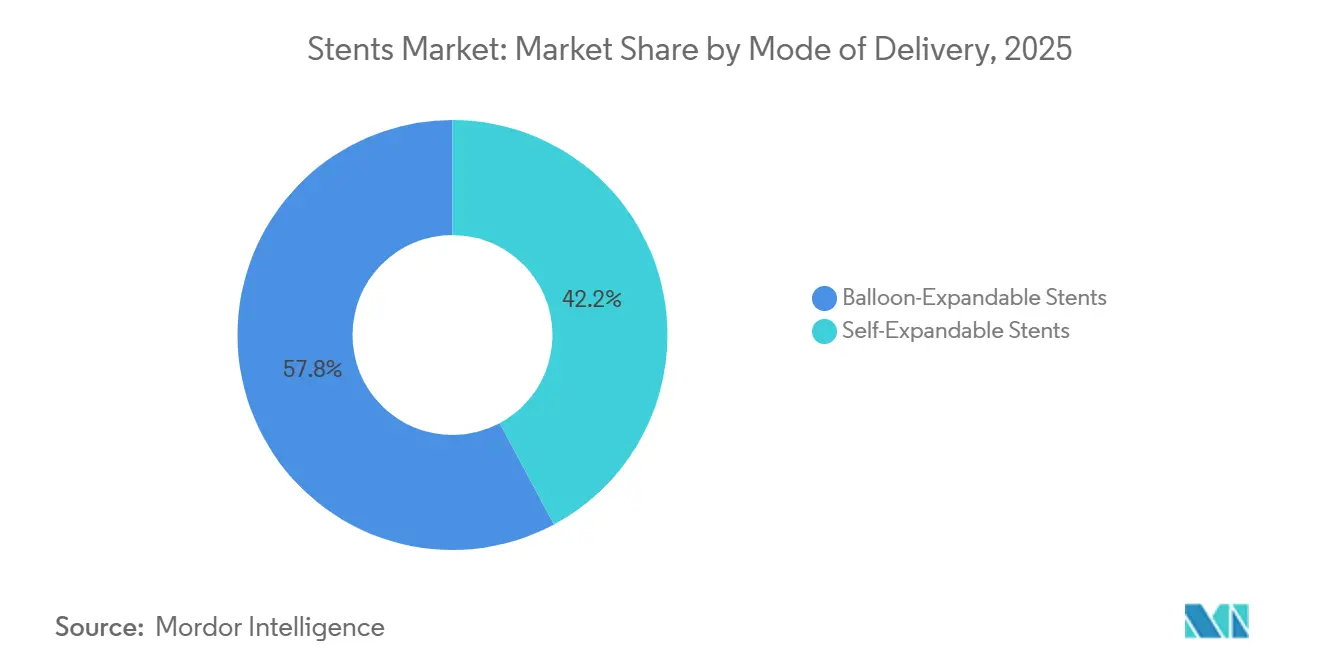
- Balloon-expandable delivery captured 57.82% revenue in 2025, but self-expandable formats are expected to advance at an 8.31% CAGR as peripheral disease interventions climb.
- Hospitals retained 69.22% end-user revenue in 2025, yet ambulatory surgical centers lead growth with a projected 7.24% CAGR to 2031 on the back of same-day-discharge PCI.
- North America generated 32.58% of 2025 sales; Asia-Pacific is anticipated to expand at a 6.36% CAGR, driven by high-volume, low-price procurement in China and India.
Note: Market size and forecast figures in this report are generated using Vijeron Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Section 3
Market Trends and InsightsDrivers Impact Analysis of Stents Market*Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
Rising Prevalence of Cardiovascular & Peripheral Arterial Diseases | +0.9% | Global, highest in North America, Europe, urban Asia-Pacific | Long term (≥4 years) |
Growing Demand for Minimally Invasive Percutaneous Interventions | +0.7% | Global, led by North America and Western Europe | Medium term (2-4 years) |
Technological Advancements in Drug-Eluting & Bioresorbable Stents | +0.6% | North America, Europe, Japan, South Korea | Medium term (2-4 years) |
Outpatient PCI Expansion Via ASC-Friendly Reimbursement Reforms | +0.5% | United States, select European markets | Short term (≤2 years) |
AI-Enabled Imaging & Robotic Navigation Accelerating Adoption | +0.4% | North America, Western Europe, Japan | Medium term (2-4 years) |
Rapid Roll-Out of Budget-Priced, Government-Capped Stents in India & China | +0.8% | India, China, Southeast Asia | Short term (≤2 years) |
Source: Vijeron Intelligence |
Rising Prevalence of Cardiovascular & Peripheral Arterial DiseasesCardiovascular disorders caused 17.9 million deaths in 2024, equal to 32% of all global mortality, elevating demand for revascularization tools such as stents.[1]World Health Organization, “Cardiovascular Diseases (CVDs),” WHO, who.int Diabetes affected 537 million adults in 2025, accelerating atherosclerotic plaque progression and necessitating repeat interventions. In the United States, coronary artery disease affected 20.5 million adults in 2024, with annual PCI procedures surpassing 1 million.[2]American Heart Association, “Heart Disease and Stroke Statistics — 2024 Update,” AHA, heart.orgPeripheral arterial disease touches 200 million people worldwide, but treatment rates remain below 15% in low-income nations, suggesting untapped pent-up need. Aging populations in Japan and Western Europe are presenting more complex multivessel disease, prompting thinner-strut device design. Emerging data also link prolonged exposure to PM2.5 above 100 µg/m³ in parts of India and China to a 30% surge in acute coronary syndrome admissions.
Growing Demand for Minimally Invasive Percutaneous InterventionsPatients favor catheter-based therapy over surgical bypass owing to shorter stays and quicker recovery. Same-day discharge reached 22% of U.S. elective PCI cases in 2025, up from 8% in 2020, aided by radial access and refined anticoagulation.[3]Society for Cardiovascular Angiography and Interventions, “Same-Day Discharge After Elective PCI,” SCAI, scai.org Drug-eluting stents now secure 18-month patency above 80% in diabetic superficial femoral artery cohorts, broadening peripheral indications. Neurovascular thrombectomy with adjunct flow-diverter implantation is reducing stroke disability when performed within a six-hour window. Outpatient migration is trimming per-case reimbursement, compelling manufacturers to negotiate volume-based contracts. The European Medicines Agency has fast-tracked devices incorporating novel polymers to cut required dual-antiplatelet therapy durations.
Technological Advancements in Drug-Eluting & Bioresorbable StentsNext-generation coronary devices employ biodegradable coatings that release sirolimus-class agents over 3-6 months and then dissolve, easing long-term inflammation. Abbott re-launched Absorb trials in 2024 with optimized poly-L-lactic acid that fully hydrolyzes in 24 months. Boston Scientific’s polymer-free Eluvia won FDA clearance in 2025, recording late-lumen-loss of just 0.09 mm at one year. Ultra-thin (<70 µm) cobalt-chromium struts improve deliverability without sacrificing radial force. Optical coherence tomography reveals angiography-guided implants are malapposed in 18% of cases, so vendors now bundle imaging consoles with stent sales.
Outpatient PCI Expansion Via ASC-Friendly Reimbursement ReformsCMS added elective PCI to the ASC list in January 2024 with a national payment of USD 8,200, catalyzing a wave of 47 new cardiovascular centers in 2025. Facilities apply CathPCI risk scores to triage candidates, excluding those with left-ventricular ejection fraction below 30%. Radial access plus bivalirudin drives vascular complication rates below 1%, enabling walk-out discharge. Major private insurers rapidly mirrored CMS policy. Profit-sharing has encouraged physician-owned centers, redistributing facility fees away from hospitals.
Restraints Impact Analysis of Stents Market*Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
Stringent Regulatory Approval & Post-Market Surveillance Demands | -0.5% | Global, most stringent in United States, EU, Japan | Long term (≥4 years) |
In-Stent Thrombosis / Restenosis Risks & Related Litigation | -0.3% | North America, Europe | Medium term (2-4 years) |
Supply-Chain Fragility for Cobalt-Chromium & Nitinol Alloys | -0.4% | Global, acute in Asia-Pacific manufacturing hubs | Short term (≤2 years) |
Rising Uptake of Drug-Coated Balloons & Intravascular Lithotripsy | -0.6% | Europe, United States, Japan | Medium term (2-4 years) |
Source: Vijeron Intelligence |
Stringent Regulatory Approval & Post-Market Surveillance DemandsThe FDA now requires five-year data on 1,500 patients for drug-eluting stent approvals, doubling timelines to 36 months and elevating per-device trial costs to USD 40 million. EU MDR enforcement since May 2024 mandates annual factory audits, producing a 14-month CE-renewal backlog. Japan’s PMDA permits conditional entry for bioresorbable scaffolds after two-year data but insists on manufacturer-funded registries. Administrative load favors incumbents with deep regulatory teams and deters venture-backed entrants.
In-Stent Thrombosis / Restenosis Risks & Related LitigationMeta-analyses published in 2024 cited a 0.6% annual late-thrombosis rate for second-generation drug-eluting stents, equating to 6,000 U.S. events yearly. Dual-antiplatelet adherence drops to 62% at 18 months, amplifying risk. Class-action suits filed in 2025 over first-generation paclitaxel devices seek USD 200 million in damages. Neointimal hyperplasia drives 8-12% restenosis rates within two years, prompting costly repeat interventions. Regulators now direct manufacturers to embed thrombosis risk calculators in labeling.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Section 4
Stents Market Segment AnalysisBy Stent Type:Neurovascular Expansion Outpaces Coronary MaturityCoronary devices retained 61.46% of the 2025 stents market share on the strength of entrenched use in ischemic heart disease. Growth, however, is leveling as drug-eluting penetration tops 90% and bare-metal applications shrink to graft lesions. Neurovascular stents are forecast to post an 8.46% CAGR through 2031, propelled by the widespread rollout of flow-diverter technology that safely treats wide-neck aneurysms without open surgery. Peripheral vascular implants benefit from an endovascular-first approach to limb salvage, with patency above 75% at three years when combined with drug-coated balloons.
Neurovascular momentum underscores a broader shift in the stents market toward complex, high-acuity indications, where reimbursement per case remains robust despite pricing pressure elsewhere. Gastrointestinal, urological, and airway segments together account for a small slice of the overall stents market size but are advancing rapidly as biodegradable polymers eliminate retrieval needs in palliative oncology settings. Bioresorbable coronary scaffolds, although still trial-restricted, are expected to re-enter commercialization on refined polymer chemistry backed by the ABSORB IV data set due in 2026.
Image © Vijeron Intelligence. Reuse requires attribution under CC BY 4.0. By Material:Polymeric Platforms Tackle Long-Term ComplicationsMetallic alloys such as cobalt-chromium and platinum-chromium commanded 63.68% of 2025 revenue because they offer thin struts without sacrificing radial strength. Polymeric constructs are projected to climb at a 7.56% CAGR on rising surgeon confidence that resorbable devices reduce late thrombosis. Within that niche, poly-L-lactic acid dominates but newer blends featuring polycaprolactone are tuning degradation to 18-24 months, restoring vasomotion once support is no longer needed.
Interest in natural biomaterials such as collagen coatings remains modest, yet they serve patients with metal hypersensitivity and pediatric congenital defects requiring temporary scaffolds. Polymer-free drug-eluting stents provide a tactical intermediate, keeping metallic reliability while dropping the inflammatory load of carrier polymers. This transition illustrates how the stents market size growth intertwines with material science breakthroughs.
By Mode of Delivery:Self-Expandable Designs Climb in Tortuous AnatomyBalloon-expandable platforms led with 57.82% revenue in 2025 thanks to precise inflation control in rigid, calcified coronary lesions. Self-expandable nitinol models are forecast to outpace at an 8.31% CAGR as peripheral and neurovascular work shifts volume their way. These devices can recover a pre-programmed diameter after compression and ride out vessel flexion, a critical trait in femoral arteries experiencing 40% cyclical diameter change during walking.
Carotid and renal segments are transitioning toward self-expandable architectures that maintain wall apposition as vessels remodel. Flow-diverter constructs, essentially tightly braided self-expandable mesh, redirect blood away from aneurysm sacs while keeping side branches patent. Hybrid balloon-plus-self designs for aortic bifurcations are being prototyped, though regulatory guidance is still emerging.
Image © Vijeron Intelligence. Reuse requires attribution under CC BY 4.0. By End User:Ambulatory Centers Capture Same-Day Discharge MomentumHospitals continued to hold 69.22% of procedure revenue in 2025 because they treat multivessel and high-risk patients requiring surgical backup. Ambulatory surgical centers are predicted to rise at a 7.24% CAGR, energized by CMS policy and patient preference for shorter stays. Radial access provides sub-1% vascular complication rates, allowing six-hour observation windows.
Cardiac clinics—office-based labs with limited anesthesia—are eyeing single-vessel, stable lesions but remain constrained by state regulations that reserve complex interventions for hospitals. In dense metropolitan areas, the margin differential motivates clinicians to form physician-owned ASCs, recapturing facility fees previously ceded to hospitals. Overseas, Germany and the United Kingdom have begun pilot ASC PCI programs, though hospital-centric rules slow uptake.
Section 5
Geography AnalysisNorth America Stents MarketNorth America led with 32.58% of 2025 revenue as sophisticated imaging suites, AI-enabling software, and premium bioresorbable launches kept average selling prices elevated. U.S. procedure counts are steady, but downward price renegotiations with group purchasing organizations are tempering top-line growth. Canada’s single-payer system is slower to adopt bioresorbables, yet provincial health authorities are funding robotics pilots to offset rural cardiologist shortages.
APAC and Europe Stents MarketAsia-Pacific is projected to deliver a 6.36% CAGR to 2031 and will likely overtake Europe in absolute revenue by late forecast. China’s procurement program dropped unit prices to USD 97, propelling a 140% spike in volumes as rural cath-lab build-outs captured previously untreated cases. India performed 1.2 million coronary interventions in 2025 after sustained price caps lowered out-of-pocket costs below catastrophic thresholds. Southeast Asian ministries are drafting copycat tenders, signaling sustained double-digit unit growth even if revenue per case compresses.
EMEA, APAC and South America Stents MarketEurope faces budget ceilings and growing preference for drug-coated balloons that cost 40% less than metallic drug-eluting stents. Germany, France, and the United Kingdom together make up 60% of regional consumption, yet price erosion dominates as national health services pursue bundled cardiology payments. Japan’s ultra-aged demographic is fueling peripheral and neurovascular demand, but biannual fee schedule reductions limit monetization. The Middle East and Africa leverage oil-funded investment in catheterization labs, but a dearth of trained interventionists keeps procedure density low. South America’s public-sector expansion lifts basic coronary volumes, although currency swings and tariff burdens complicate supply chains in Brazil and Argentina.
Image © Vijeron Intelligence. Reuse requires attribution under CC BY 4.0.
Section 6
Regulatory LandscapeDrug-eluting coronary stents are regulated as combination products in the United States, typically requiring FDA Premarket Approval (PMA) alongside expanded clinical and post-market evidence. Within the study period, the FDA tightened expectations for long-term follow-up for drug-eluting stents, and in February 2026 the agency implemented the Quality Management System Regulation (QMSR). The change aligns medical-device quality requirements with ISO 13485:2016 and affects design controls, supplier qualification, and manufacturing traceability for stent manufacturers and their contract partners.
In Europe, stents fall under the Medical Device Regulation (EU) 2017/745 (MDR), with additional requirements for drug-device combinations, including Notified Body opinion workflows under MDR Article 117 for integral products, and active vigilance guidance applied to coronary stents. MDR enforcement has increased certification and audit intensity, and May 2026 brought additional operational milestones tied to EUDAMED module use and MDR transition requirements for certain Class III implantable pathways. Compliance demands also interact with trade policy: China adjusted 2026 import tariffs on certain medical components relevant to stent manufacturing materials, while European industry bodies publicly opposed proposed US Section 301 tariff actions in mid-2026 due to potential supply-chain disruption for globally sourced medical technologies.
Section 7
Value Chain AnalysisThe stents value chain starts with upstream specialty materials and chemicals, including cobalt-chromium and platinum-chromium tubes for balloon-expandable platforms, nitinol tubing for self-expandable designs, and drug-polymer inputs for drug-eluting systems. Core manufacturing includes precision laser cutting, electropolishing, surface modification, drug coating (or polymer-free drug reservoirs), crimping onto delivery systems, and sterilization (commonly ethylene oxide), followed by packaging, labeling, and lot release under device-grade quality systems. Regulatory architecture shapes how these steps are documented and controlled: in the United States, the FDA Office of Combination Products coordinates oversight for drug-eluting cardiovascular stents, while in the European Union, MDR requirements, including Article 117 considerations for integral drug-device combinations, drive additional technical documentation and Notified Body interactions.
Midstream constraints have increasingly focused on capacity and lead-time volatility for specialty alloys and finishing steps, particularly for nitinol bars and tubing, where extended lead times during 2024-2025 have been reported due to post-processing dependencies and competing industrial demand. This has reinforced dual-sourcing, safety-stock strategies, and selective vertical integration across large OEMs and key suppliers, especially for materials and critical finishing operations. Downstream, manufacturers sell through direct hospital and ambulatory accounts and via distributors in tender-heavy markets. Buyer power is amplified by group purchasing organizations, national procurement programs, and government price ceilings in markets such as China and India, pushing vendors toward volume-based contracting, bundled imaging or workflow offerings, and localized assembly or registration strategies to maintain access and continuity of supply.
Section 8
Competitive Landscape
The top five players include Abbott, Medtronic, Boston Scientific, Terumo, and B. Braun, signifying a moderately concentrated field. Multinationals defend margin by bundling robotic navigation, AI imaging, and ultra-thin strut technology into premium offerings, while regional challengers pursue a value-tier strategy anchored on government tenders at prices 40–50% below legacy levels. Vertical integration is expanding as Boston Scientific secured a 30% stake in a Chinese nitinol supplier in 2024 to hedge material volatility.
Patent filings remain vigorous; 1,247 stent-related applications reached the USPTO in 2025, focusing on polymer degradation kinetics, anti-thrombotic coatings, and OCT integration. Smaller entrants such as Elixir Medical and Translumina chase niche lesions like chronic total occlusions. The ascent of drug-coated balloons and lithotripsy compels portfolio diversification, with firms submitting combo-device approvals pairing calcium modification with resorbable scaffolds. Industry consensus anticipates a bifurcated market: premium innovation for complex disease in developed settings and cost-optimized, ISO-compliant workhorses for emerging economies.
Stents Industry Leaders* Boston Scientific Corporation
- Medtronic PLC
- Abbott Laboratories
- Terumo Corporation
- BIOTRONIK SE & Co. KG
- *Disclaimer: Major Players sorted in no particular order
Image © Vijeron Intelligence. Reuse requires attribution under CC BY 4.0.Stents Market Companies Covered in this Report* Abbott Laboratories
- Andramed GmbH
- B. Braun
- Beckton Dickinson
- Blue Sail Medical Co., Ltd. (Biosensors)
- BIOTRONIK
- Boston Scientific
- Cardiovascular Systems Inc. (CSI)
- Cardinal Health
- Cook Group
- Elixir Medical
- Endologix
- Hexacath
- Lepu Medical
- Medtronic
- Meril Life Science
- MicroPort
- Sahajanand Medical Technologies (SMT)
- Shockwave Medical
- Terumo
- Translumina
- Vascular Concepts
- W. L. Gore & Associates
Read Analysis of Stents Companies
Section 9
Market Opportunities and Future Outlook
A key whitespace is the intersection of outpatient migration and complex-lesion enablement. Same-day discharge PCI adoption and the shift of selected cases into ambulatory surgical centers change purchasing patterns toward standardized, high-throughput stent platforms and compatible imaging or procedural workflows. In the United States, CMS policy that added elective PCI to the ASC list (January 2024) has already supported new cardiovascular center buildouts, creating a clearer commercial lane for vendors that can support ASC credentialing needs, inventory efficiency, and consistent clinical performance under tighter per-case economics.
Product and geographic opportunity also shows up in next-generation drug-eluting and bioresorbable or absorbable-polymer designs targeting late adverse events and potentially shorter antiplatelet therapy considerations, alongside expansion into peripheral, venous, and neurovascular adjacencies. In 2026, several regulatory and clinical signals supported this direction: Kossel Medtech reported NMPA approval for its MiStent sirolimus-eluting absorbable-polymer coronary stent in April 2026, Solaris Endovascular received FDA Breakthrough Device Designation in May 2026 for a drug-eluting covered stent for dialysis access, and Latin American access pathways were highlighted by Sino Medical Sciences receiving INVIMA approval in Colombia (June 2026) for its HT Supreme drug-eluting stent. On the compliance side, the FDA QMSR implementation in February 2026 and evolving EU MDR frameworks, including Well-Established Technologies list expansion activity during 2026, are raising the value of scalable quality systems and strong technical documentation. That favors manufacturers that can industrialize evidence generation while keeping cost and supply continuity aligned to tender-driven purchasing.
Section 10
Recent Industry Developments in Stents Market* July 2026: Terumo Corporation announced a voluntary recall covering specific models of the Relay Pro Thoracic Stent-Graft System. The action heightened attention on post-market surveillance readiness and field-action execution for implantable vascular platforms, influencing hospital confidence and inventory decisions for affected product lines.
- June 2026: Medtronic completed its USD 550 million acquisition of Scientia Vascular. The deal expanded Medtronic’s neurovascular access capabilities alongside its therapeutic portfolio, strengthening end-to-end procedure offerings that can affect vendor positioning in neurovascular stent and adjacent intervention workflows.
- May 2026: Boston Scientific reported positive results from the FRACTURE IDE trial of the SEISMIQ 4CE coronary intravascular lithotripsy catheter, including a 93.7% procedural success rate for stent delivery in severely calcified coronary disease. This reinforced the strategic importance of calcium-modification tools that improve deliverability and expand treatable lesion complexity, supporting broader stent utilization in challenging anatomies.
Section 11
Table of Contents for Stents Industry Report1. Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
- Research Methodology
- Executive Summary
- Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers* 4.2.1 Rising Prevalence of Cardiovascular & Peripheral Arterial Diseases (CAD/PAD)
- 4.2.2 Growing Demand for Minimally Invasive Percutaneous Interventions
- 4.2.3 Technological Advancements in Drug-Eluting & Bioresorbable Stents
- 4.2.4 Outpatient PCI Expansion Via ASC-Friendly Reimbursement Reforms
- 4.2.5 AI-Enabled Imaging & Robotic Navigation Accelerating Adoption
- 4.2.6 Rapid Roll-Out of Budget-Priced, Government-Price-Capped Stents in India & China
- 4.3 Market Restraints* 4.3.1 Stringent Regulatory Approval & Post-Market Surveillance Demands
- 4.3.2 In-Stent Thrombosis / Restenosis Risks & Related Litigation
- 4.3.3 Supply-Chain Fragility for Cobalt-Chromium & Nitinol Alloys
- 4.3.4 Rising Uptake of Drug-Coated Balloons (DCB) And Intravascular Lithotripsy as Stent-Less Treatment
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter’s Five Forces Analysis* 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- Market Size & Growth Forecasts (Value in USD)
- 5.1 By Stent Type* 5.1.1 Coronary Stents
- 5.1.1.1 Drug-Eluting Coronary Stents
- 5.1.1.2 Bare-Metal Coronary Stents
- 5.1.1.3 Bioresorbable Coronary Scaffolds
- 5.1.2 Peripheral Vascular Stents
- 5.1.2.1 Iliac Artery Stents
- 5.1.2.2 Femoral-Popliteal Stents
- 5.1.2.3 Carotid Artery Stents
- 5.1.2.4 Renal Artery Stents
- 5.1.3 Neurovascular Stents
- 5.1.3.1 Flow-Diverter Stents
- 5.1.3.2 Intracranial Atherosclerotic Stents
- 5.1.4 Gastrointestinal Stents
- 5.1.4.1 Biliary Stents
- 5.1.4.2 Esophageal Stents
- 5.1.4.3 Colonic / Enteral Stents
- 5.1.5 Urological Stents
- 5.1.5.1 Ureteral Stents
- 5.1.5.2 Prostatic Stents
- 5.1.6 Airway Stents
- 5.1.6.1 Tracheal Stents
- 5.1.6.2 Bronchial Stents
- 5.2 By Material* 5.2.1 Metallic Biomaterials
- 5.2.2 Polymeric Biomaterials
- 5.2.3 Natural Biomaterials
- 5.3 By Mode of Delivery* 5.3.1 Balloon-Expandable Stents
- 5.3.2 Self-Expandable Stents
- 5.4 By End User* 5.4.1 Hospitals
- 5.4.2 Ambulatory Surgical Centers
- 5.4.3 Cardiac & Specialty Clinics
- 5.5 By Geography* 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 France
- 5.5.2.3 United Kingdom
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 South Korea
- 5.5.3.5 Australia
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East & Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East & Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)* 6.3.1 Abbott Laboratories
- 6.3.2 Andramed GmbH
- 6.3.3 B. Braun Melsungen AG
- 6.3.4 BD
- 6.3.5 Blue Sail Medical Co., Ltd. (Biosensors)
- 6.3.6 BIOTRONIK SE & Co. KG
- 6.3.7 Boston Scientific Corporation
- 6.3.8 Cardiovascular Systems Inc. (CSI)
- 6.3.9 Cardinal Health
- 6.3.10 Cook Medical
- 6.3.11 Elixir Medical
- 6.3.12 Endologix
- 6.3.13 Hexacath
- 6.3.14 Lepu Medical Technology
- 6.3.15 Medtronic plc
- 6.3.16 Meril Life Sciences Pvt. Ltd
- 6.3.17 MicroPort Scientific Corporation
- 6.3.18 Sahajanand Medical Technologies (SMT)
- 6.3.19 Shockwave Medical
- 6.3.20 Terumo Corporation
- 6.3.21 Translumina
- 6.3.22 Vascular Concepts
- 6.3.23 W. L. Gore & Associates
- Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment
Section 12
Stents Market Report Scope and Research MethodologyMarket Definition and CoverageThis market is sized as the revenue generated from new stent devices sold globally for use in keeping blood vessels or other body passages open during medical procedures, counted at the manufacturer selling price in USD.
Scope exclusions: Custom stent graft systems used for aortic aneurysm repair, dental and orthopedic placeholder implants, and refurbished or re-processed stents are not counted.
Segments Covered in This Report By Stent Type Coronary Stents* Drug-Eluting Coronary Stents
- Bare-Metal Coronary Stents
- Bioresorbable Coronary Scaffolds
- Peripheral Vascular Stents* Iliac Artery Stents
- Femoral-Popliteal Stents
- Carotid Artery Stents
- Renal Artery Stents
- Neurovascular Stents* Flow-Diverter Stents
- Intracranial Atherosclerotic Stents
- Gastrointestinal Stents* Biliary Stents
- Esophageal Stents
- Colonic / Enteral Stents
- Urological Stents* Ureteral Stents
- Prostatic Stents
- Airway Stents* Tracheal Stents
- Bronchial Stents
- By Material* Metallic Biomaterials
- Polymeric Biomaterials
- Natural Biomaterials
- By Mode of Delivery* Balloon-Expandable Stents
- Self-Expandable Stents
- By End User* Hospitals
- Ambulatory Surgical Centers
- Cardiac & Specialty Clinics
- By Geography North America United States
- Canada
- Mexico
- Europe* Germany
- France
- United Kingdom
- Italy
- Spain
- Rest of Europe
- Asia-Pacific* China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East & Africa* GCC
- South Africa
- Rest of Middle East & Africa
- South America* Brazil
- Argentina
- Rest of South America
Data Sources, Market Sizing, and ValidationDesk Research
Desk research started by mapping the demand setting where stents are actually used, and then matching it to supply side signals that can be checked. Public sources such as the World Health Organization, the US FDA device and safety databases, the US Centers for Disease Control and Prevention, and OECD health statistics were used to understand procedure volumes, disease burden, and broad care access trends.
We also referred to sources such as national health ministries and reimbursement schedules, medical society publications and registries, and peer-reviewed cardiology and endoscopy journals to sanity check utilization patterns and adoption of newer stent types. For manufacturer context, we reviewed annual reports, investor presentations, and press releases, and we supplemented this with paid subscriptions for company financials and intelligence plus patent databases when clarifying product pipelines and technology shifts. These are illustrative sources, and many other public documents were also used for cross-checks and clarification during the work.
Primary Interviews and Surveys
Primary work focused on validating what gets counted as a stent sale in practice, and on aligning assumptions around pricing, mix, and regional uptake. We spoke with a balanced set of stakeholders such as device manufacturers and distributors, hospital procurement teams, clinicians, and catheter lab managers across APAC, EMEA, and the Americas, so gaps from desk findings could be closed and assumptions stress-tested.
Distribution of primary research fieldwork respondents
Company type | Respondent position | Region |
Top tier: 25% | CXOs: 14% | APAC: 45% |
Mid tier: 55% | Functional/Unit leaders: 41% | EMEA: 36% |
Smaller Players: 20% | Managers: 45% | Americas: 19% |
Market-Sizing & ForecastingSizing was built using a top-down approach where procedure volumes and treated patient pools are reconstructed by region, which are then translated into stent demand using utilization rates and typical units per procedure. The model was then corroborated with selective bottom-up approximations, including sampled average selling prices by stent category, distributor markup channel checks, and supplier revenue splits where public disclosure allowed, so totals could be adjusted when the two views did not align.
Key inputs used in the model include interventional cardiology and peripheral procedure volumes, endoscopy and urology case loads relevant to non-vascular stents, adoption mix between coronary and peripheral use, the shift between balloon-expandable and self-expanding formats, and price progression influenced by reimbursement pressure and product upgrades. When gaps existed for smaller countries, we used proxy indicators like hospital capacity and healthcare spend per capita to scale penetration rates, and then rechecked the outputs with interview feedback.
For forecasting, scenario analysis was applied around procedure growth and pricing, and the trend lines were supported using exponential smoothing for near-term demand where utilization changes are gradual. The final trajectory was reviewed against expected disease prevalence trends, care access expansion, and likely regulatory and reimbursement changes discussed during primary conversations.
Data Validation & Update CycleOutputs were validated through triangulation across independent signals, including procedure trends, disclosed device revenues, and region-level healthcare spend direction. Large variances were flagged, assumptions were rechecked, and follow-up calls were triggered when pricing, mix, or scope interpretation appeared to be driving the mismatch.
Before sign-off, the model goes through multi-step analyst review, where calculations, currency timing, and growth logic are checked and then reconciled with the narrative. Reports are refreshed annually, and interim updates are done when material events occur such as major approvals, safety actions, or sharp reimbursement changes. Right before delivery, a final pass is performed so clients receive the latest updated view.
Vijeron Intelligence's Stents Market Size Versus Other Published EstimatesPublished market sizes for stents can look different because each publisher draws the boundary in its own way, and then applies different pricing and utilization assumptions to convert demand into revenue. The year used as the starting point and the currency timing choices also influence the final number, especially when regional mix is changing.
By tracking procedure-linked demand and then refreshing the inclusion rules around stent graft systems, the Vijeron Intelligence estimate stays tied to finished stent device sales rather than adjacent implant categories that can inflate totals. Differences also come from how fast pricing is assumed to decline, whether non-vascular stents are fully included, and how often the model is updated when regulatory or reimbursement events shift volumes.
Benchmark comparison
Source | Market Size | Gaps in Research Methodology |
Vijeron Intelligence | USD 15.30 B (2025) | |
Global Research Publisher A | USD 14.80 B (2024) | Uses an earlier base year and a broader product taxonomy that can bundle neurovascular flow diverters and several non-vascular stents without the same manufacturer-price boundary, which can shift the measured revenue pool. |
Healthcare Publisher B | USD 14.50 B (2025) | Groups the market into broader product buckets and references stent-related implants, which may mix accessories and adjacent implant categories with core stent devices, and it also applies a longer forecast window with faster growth assumptions. |
The spread in the table is largely explained by what is counted as a stent sale, plus base-year alignment and how pricing and mix are carried forward. When scope is kept consistent and assumptions are tied back to procedure activity and observable pricing signals, the final market size becomes easier to trace and replicate for planning decisions.
Section 13
Key Questions Answered in the ReportWhat is the projected revenue of the stents market in 2031? The stents market is forecast to reach USD 19.66 billion by 2031, expanding at a 4.46% CAGR from 2026.
Which stent segment is expected to grow fastest through 2031? Neurovascular stents are projected to post the highest 8.46% CAGR as flow-diverter technology gains traction in stroke care.
How are government price caps shaping purchasing trends in Asia? India and China have enforced strict price ceilings and volume-based tenders, slashing unit prices to as low as USD 97 and driving triple-digit growth in procedure volumes.
Why are ambulatory surgical centers important to future implant volumes? CMS added elective PCI to the ASC list in 2024, enabling same-day discharge and sparking a 47-center construction boom that will lift ASC stent placements at a 7.24% CAGR.
What material innovations are influencing long-term outcomes? Polymeric bioresorbable scaffolds made from optimized poly-L-lactic acid blends dissolve after vessel healing, reducing inflammation and late thrombosis risk compared to permanent metal.
How is AI improving stent deployment accuracy? AI-driven imaging systems predict optimal stent sizing with 92% concordance to experts and guide robotic platforms that cut operator radiation by 95%.
Section 14
Related Reports Explore More ReportsReport on Peripheral Stent IndustryIndustry Outlook of Self-Expanding StentsReport on Ureteral Stent IndustryUnited States Cardiovascular Devices Market ResearchIndustry Trends in Venous StentsCoronary Cutting Balloon Industry