Luxury Eyewear Market Size & Share Analysis - Growth Trends and Forecast (2026 - 2031)
Luxury Eyewear Market Size & Share Analysis - Growth Trends and Forecast (2026 - 2031)
Source: https://www.mordorintelligence.com/industry-reports/luxury-eyewear-market | Extracted via Vijeron Intelligence Scraper
Section 1
Luxury Eyewear Market Size and Share
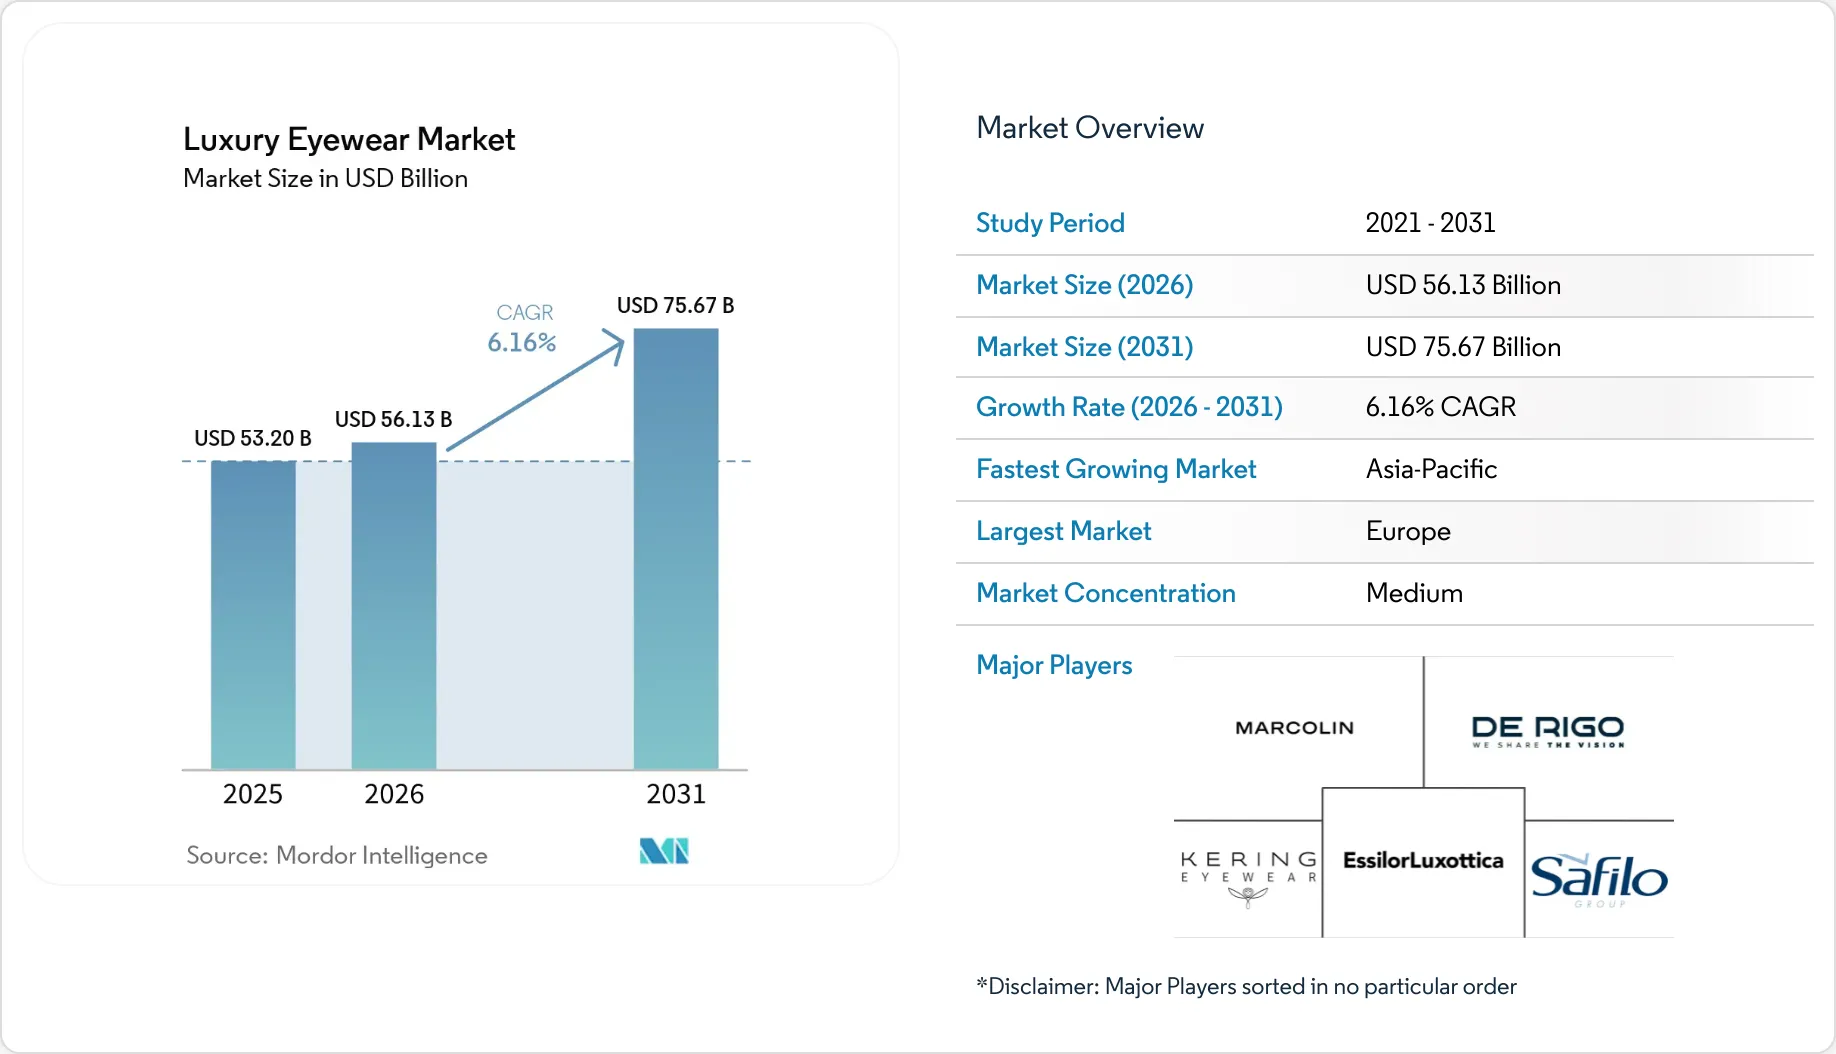
Market Overview
Study Period
2021 - 2031
Market Size (2026)
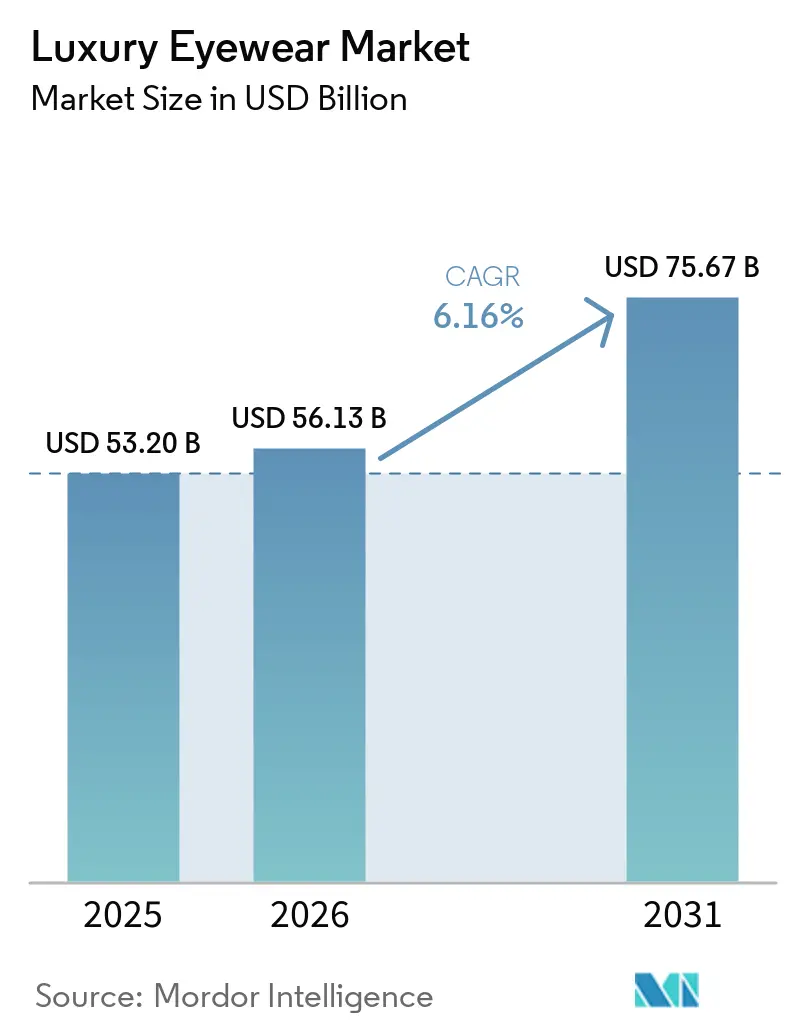
USD 56.13 Billion
Market Size (2031)
USD 75.67 Billion
Growth Rate (2026 - 2031)
6.16 %
Fastest Growing Market
Asia-Pacific
Largest Market
Europe
Market Concentration
Medium
Major Players
*Disclaimer: Major Players sorted in no particular order
Image © Vijeron Intelligence. Reuse requires attribution under CC BY 4.0.
Image © Vijeron Intelligence. Reuse requires attribution under CC BY 4.0.
Section 2
Luxury Eyewear Market Analysis by Vijeron Intelligence
The global luxury eyewear market size is expected to grow from USD 53.20 billion in 2025 to USD 56.13 billion in 2026 and is forecast to reach USD 75.67 billion by 2031 at a 6.16% CAGR over 2026-2031. The global luxury eyewear market is driven by increasing disposable incomes, a growing preference for premium fashion accessories, and the influence of luxury branding as a status symbol and expression of personal identity. Heightened awareness of eye health, combined with the rising demand for prescription eyewear, has led consumers to prioritize high-quality frames that blend functionality with elegant design. Factors such as rapid urbanization, shifting fashion trends, and the impact of celebrities, social media influencers, and digital marketing have further fueled the demand for luxury sunglasses and optical eyewear. Additionally, manufacturers are contributing to market growth through ongoing product innovation, including the use of lightweight materials, sustainable acetate, titanium frames, limited-edition collections, and advanced lens technologies designed to enhance comfort and performance. The expansion of omnichannel retail, encompassing branded boutiques, e-commerce platforms, and personalized shopping experiences, has improved product accessibility and strengthened consumer engagement. Moreover, the rising popularity of luxury eyewear in emerging economies, driven by a growing affluent population and increased spending on premium lifestyle products, continues to present significant growth opportunities for the global market.
Key Report Takeaways
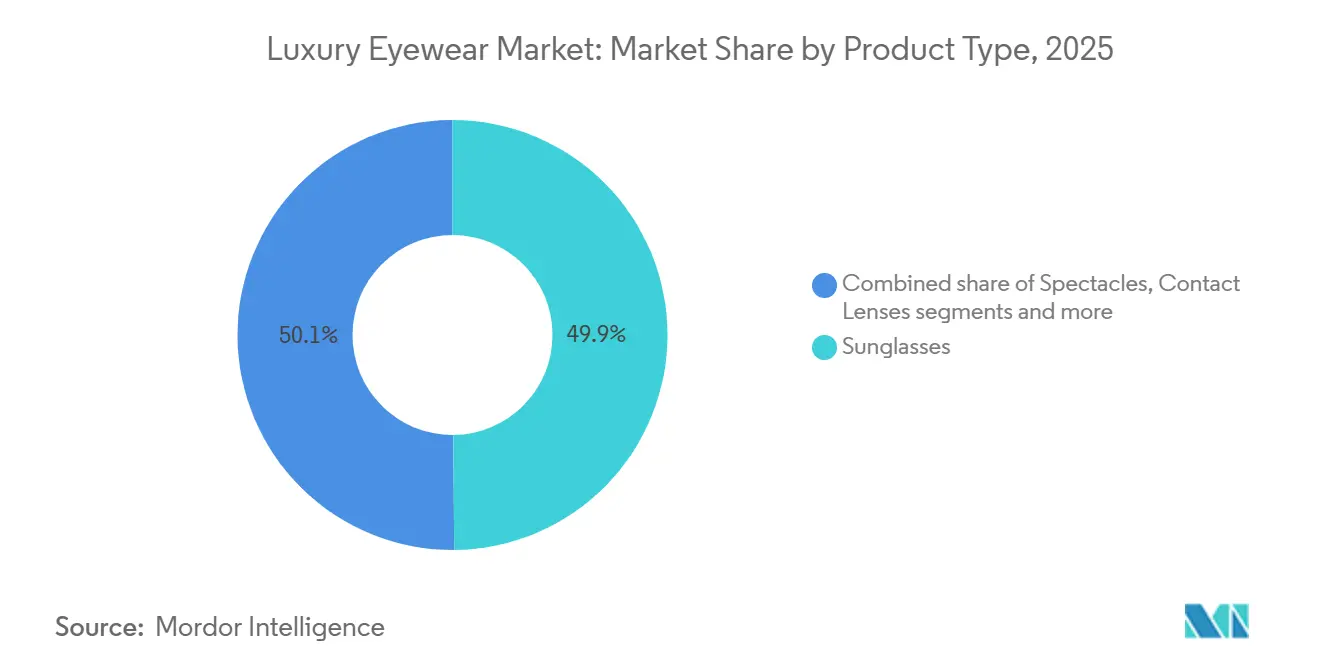
- By product type, sunglasses led the global luxury eyewear market with a 49.87% share in 2025, and sunglasses are also forecast to record the fastest growth at a 6.73% CAGR during 2026-2031.
- By end user, women held the largest share of the global luxury eyewear market at 52.35% in 2025, while unisex eyewear is projected to expand at the highest CAGR of 6.81% through 2031.
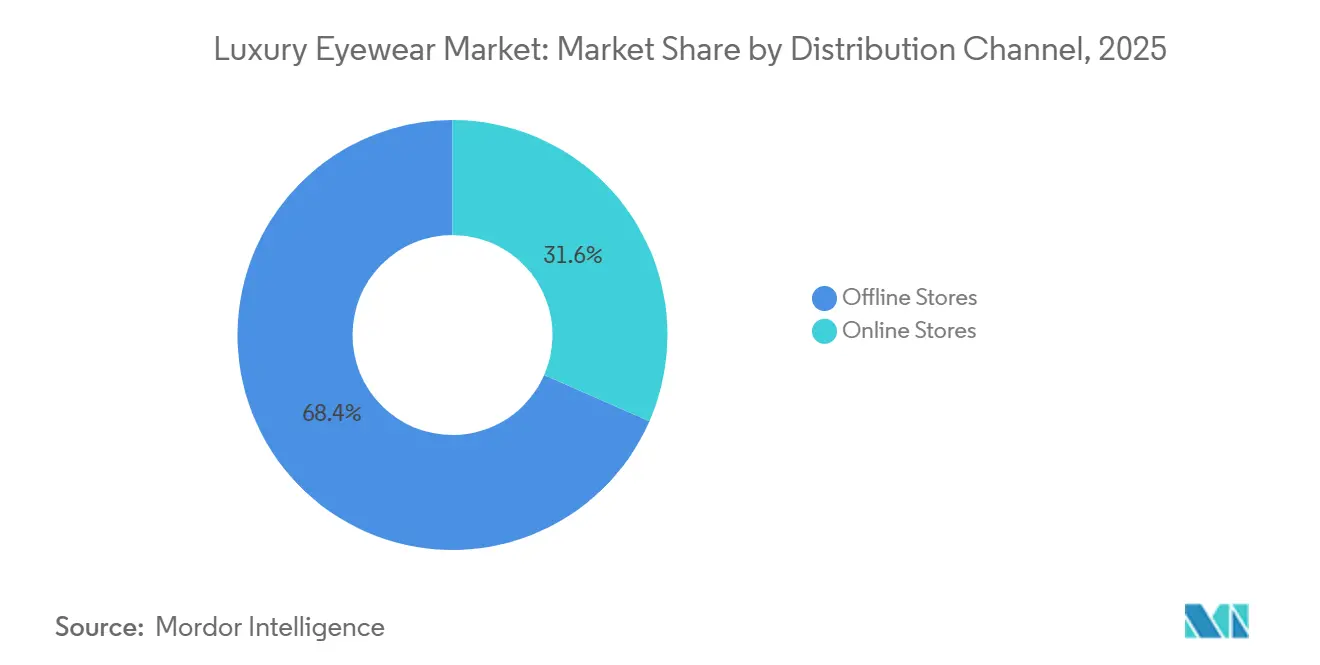
- By distribution channel, offline stores accounted for 68.44% of the global luxury eyewear market in 2025, while online stores are expected to grow the fastest at a 7.01% CAGR over 2026-2031.
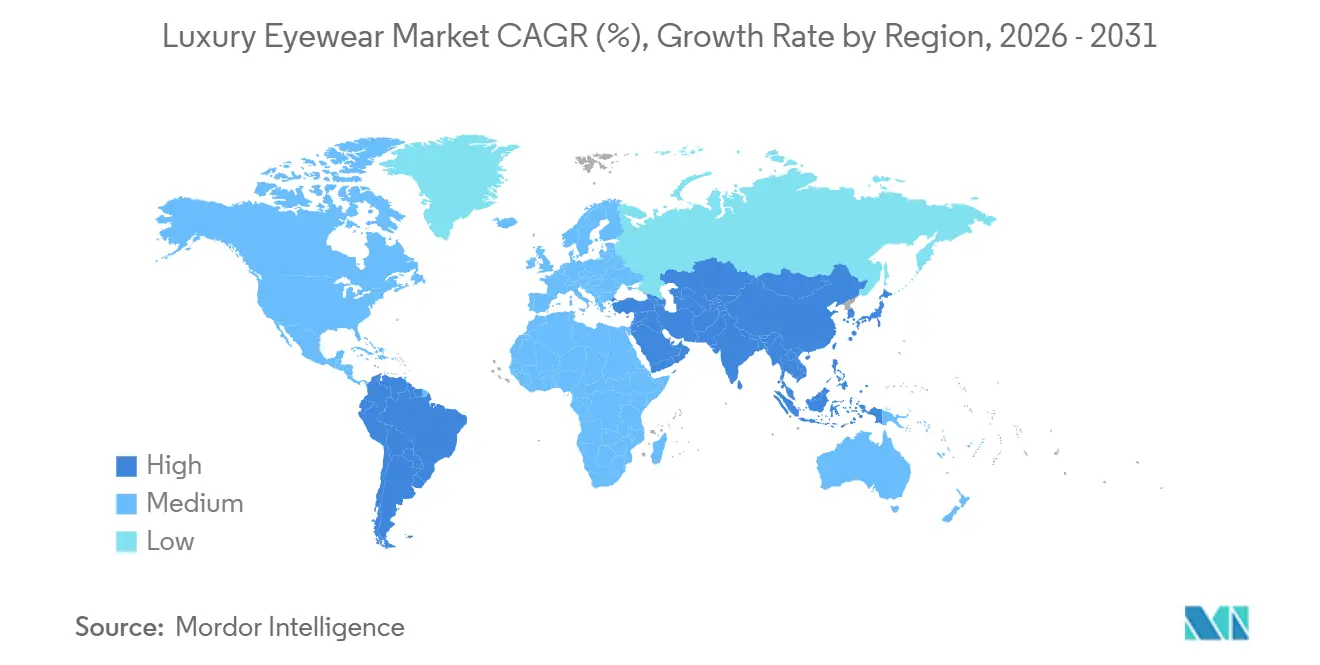
- By geography, Europe captured 31.93% of the global luxury eyewear market in 2025, while Asia-Pacific is set to post the fastest regional growth at a 7.13% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using Vijeron Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Section 3
Market Trends and Insights
Drivers Impact Analysis of Luxury Eyewear Market*
Driver
(~) % Impact on CAGR Forecast
Geographic Relevance
Impact Timeline
Growing consumer preference for premium fashion
accessories
+1.3%
Global, concentrated in North America, Europe, and Asia-Pacific
Medium term (2–4 years)
Growing popularity of celebrity, fashion house, and
influencer collaborations
+1.1%
Global, with outsized impact in Asia-Pacific and North
America
Short term (≤ 2 years)
Increasing consumer awareness of UV protection and eye
health
+0.9%
Global, accelerated in Asia-Pacific and South America
Long term (≥ 4 years)
Expansion of digital retail and omnichannel luxury
shopping
+1.0%
North America, Europe, Asia-Pacific core
Medium term (2–4 years)
Rising demand for limited-edition and exclusive
collections
+0.7%
North America, Europe
Short term (≤ 2 years)
Growing demand for sustainable and ethical luxury products
+0.6%
Europe, North America, spill-over to Asia-Pacific
Medium term (2–4 years)
Source: Vijeron Intelligence
Growing consumer preference for premium fashion accessories
Increasing consumer preference for premium fashion accessories is a significant driver of the global luxury eyewear market. Eyewear has transitioned from being solely a vision correction tool to becoming an essential component of personal style and self-expression. Consumers are increasingly opting for high-end frames and sunglasses that align with their lifestyle, social status, and fashion preferences, making luxury eyewear a staple in everyday wardrobes. This demand is particularly pronounced among younger, fashion-conscious consumers who frequently update their accessories to match evolving trends and seasonal collections. Luxury brands are leveraging this trend by launching exclusive designs, collaborations, and limited-edition collections, which enhance product appeal and reinforce brand prestige. Furthermore, rising disposable incomes, increased exposure to global fashion through digital platforms, and a growing focus on premium craftsmanship and unique aesthetics are driving consumers to invest in luxury eyewear, contributing to sustained market growth in both developed and emerging markets.
Growing popularity of celebrity, fashion house, and influencer collaborations
The increasing collaborations between luxury eyewear brands, celebrities, fashion houses, and social media influencers are driving growth in the global luxury eyewear market by enhancing product visibility and consumer appeal. Exclusive capsule collections and co-branded launches foster a sense of rarity and exclusivity, motivating consumers to purchase premium eyewear as both a fashion statement and a collectible. Influencers and celebrities boost brand recognition through digital platforms, influencing purchasing decisions and promoting the adoption of new styles, particularly among younger demographics. Additionally, partnerships with renowned fashion designers enable eyewear brands to align their collections with broader luxury fashion trends, reinforcing brand identity and attracting a wider customer base. These collaborations generate significant media coverage, improve customer engagement, and create anticipation around new product launches, contributing to higher sales, stronger brand loyalty, and sustained growth in the global luxury eyewear market.
Increasing consumer awareness of UV protection and eye health
Increasing consumer awareness of UV protection and eye health is a key driver of the global luxury eyewear market. Consumers are increasingly seeking eyewear that combines premium aesthetics with advanced vision protection. The growing understanding of the harmful effects of prolonged exposure to ultraviolet (UV) radiation, blue light from digital devices, and environmental pollutants has led to higher demand for high-quality sunglasses and prescription eyewear with UV-blocking lenses, polarized coatings, and advanced optical technologies. Luxury eyewear brands are addressing this demand by offering products that integrate superior lens performance with sophisticated craftsmanship, positioning premium eyewear as both a health investment and a fashion accessory. The rising prevalence of vision-related conditions further supports this trend. According to the World Health Organization (WHO), in February 2026, at least 2.2 billion people globally experience near or distance vision impairment, underscoring the increasing need for corrective eyewear and preventive eye care solutions[1]Source: World Health Organization, "Blindness and vision impairment," who.int. This growing focus on long-term eye health, combined with consumers' willingness to invest in premium-quality products that provide superior protection and comfort, continues to drive the growth of the global luxury eyewear market.
Expansion of digital retail and omnichannel luxury shopping
The growth of digital retail and omnichannel luxury shopping is a significant factor driving the global luxury eyewear market. These channels enable premium brands to reach a wider audience while providing seamless and personalized purchasing experiences. Consumers are increasingly opting to explore, compare, and buy luxury eyewear through integrated online and offline platforms that feature virtual try-on tools, personalized recommendations, click-and-collect options, and exclusive digital product launches. This transition has improved convenience, enhanced customer engagement, and boosted consumer confidence in purchasing high-value eyewear online. The rapid increase in internet penetration has further supported this trend by broadening access to luxury e-commerce platforms and digital brand experiences. For instance, the World Bank Group reported that 95% of the United States population used the internet in 2024, highlighting the robust digital infrastructure that facilitates the adoption of online luxury retail[2]Source: The World Bank Group, "Individuals using the Internet (% of population) - United States," data.worldbank.org. As luxury eyewear brands continue to invest in advanced e-commerce technologies, omnichannel strategies, and direct-to-consumer platforms, digital retail is playing an increasingly vital role in driving global market growth.
Restraints Impact Analysis of Luxury Eyewear Market*
Restraint
(~) % Impact on CAGR Forecast
Geographic Relevance
Impact Timeline
Proliferation of counterfeit luxury eyewear
-1.2%
Global, highest exposure in Asia-Pacific and Middle East
and Africa
Long term (≥ 4 years)
Stringent regulatory requirements for optical products
-0.6%
Europe, North America
Medium term (2–4 years)
Intense competition from non-luxury eyewear brands
-0.9%
Global, highest pressure in Asia-Pacific and South America
Medium term (2–4 years)
Supply chain challenges for premium materials
-0.7%
Global
Short term (≤ 2 years)
Source: Vijeron Intelligence
Proliferation of counterfeit luxury eyewear
The prevalence of counterfeit luxury eyewear poses a significant challenge to the global luxury eyewear market by undermining brand exclusivity, reducing legitimate sales, and diminishing consumer trust. Counterfeit sunglasses and optical frames often replicate the design of premium brands but lack the high-quality materials, precise craftsmanship, and certified UV protection of authentic products. Consequently, consumers may unknowingly purchase inferior eyewear that compromises eye safety and product performance, ultimately harming the reputation of established luxury brands. The growth of e-commerce platforms and unauthorized online sellers has further facilitated the availability and global distribution of counterfeit eyewear, complicating enforcement efforts. According to U.S. Customs and Border Protection, sunglasses accounted for USD 414 million in seized health, safety, and security commodities in FY 2024, with 772,000 units of sunglasses and eyewear ranking among the top products seized by quantity[3]Source: U.S. Customs and Border Protection, "The Truth Behind Counterfeits," cbp.gov. This widespread counterfeiting forces luxury eyewear manufacturers to allocate substantial resources to anti-counterfeiting technologies, supply chain monitoring, and intellectual property protection, thereby increasing operational costs and constraining market growth.
Stringent regulatory requirements for optical products
Stringent regulatory requirements for optical products act as a significant restraint on the global luxury eyewear market. Manufacturers must adhere to strict safety, quality, labeling, and performance standards that vary across countries and regions. Luxury eyewear products, including prescription frames and sunglasses, are regulated for lens optical accuracy, UV protection, impact resistance, material safety, and product certification before market entry. Compliance with regulations such as CE marking in Europe, FDA standards in the United States, and other country-specific frameworks involves extensive product testing, technical documentation, and quality assurance processes. These requirements increase development costs and extend product launch timelines. For globally operating luxury brands, differing regulatory standards across regions add complexity, requiring region-specific product modifications and certification procedures. Smaller and emerging premium eyewear companies face additional challenges, as the financial and administrative demands of compliance can hinder innovation, delay international expansion, and reduce competitiveness. These factors collectively constrain the overall growth of the global luxury eyewear market.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Section 4
Luxury Eyewear Market Segment Analysis
By Product Type:
Sunglasses Anchor Fashion and Functional Demand
Sunglasses accounted for a 49.87% share of the luxury eyewear market in 2025 and represent the fastest-growing product segment, with a projected CAGR of 6.73% through 2031. This growth is driven by the increasing convergence of fashion, eye protection, and premium lifestyle consumption. Consumers are progressively viewing luxury sunglasses as both functional necessities and statement accessories, fueling demand for designer collections that emphasize distinctive craftsmanship, exclusive branding, and premium materials such as titanium, acetate, and carbon fiber. Additionally, heightened awareness of the harmful effects of ultraviolet (UV) radiation has bolstered demand for high-performance lenses featuring advanced coatings, polarization, and blue-light filtering technologies. Celebrity endorsements, collaborations with fashion houses, and the influence of social media continue to shape consumer preferences, particularly among younger demographics seeking aspirational luxury products. Furthermore, the recovery of international tourism, increased participation in outdoor leisure activities, and rising disposable incomes in emerging economies are broadening the customer base for premium sunglasses. Luxury brands are also enhancing customer engagement and reinforcing brand exclusivity through omnichannel retail strategies, personalized shopping experiences, and limited-edition product launches, supporting sustained growth in the sunglasses segment.
The contact lenses segment within the global luxury eyewear market is experiencing growth due to increasing consumer demand for premium vision correction solutions that offer superior comfort, convenience, and advanced optical performance. Factors such as the rising prevalence of refractive errors, greater screen exposure, and active lifestyles are driving consumers to opt for high-quality contact lenses with features like extended wear, enhanced oxygen permeability, moisture retention, and UV protection. Affluent consumers are particularly interested in premium daily disposable, silicone hydrogel, multifocal, and specialty contact lenses that provide improved eye health and wearing comfort. Technological advancements in lens materials and personalized vision correction solutions have further enhanced the appeal of premium contact lenses. Additionally, growing awareness of eye care, expanded access to professional optometry services, and the integration of digital eye examinations with online purchasing platforms are supporting adoption in both developed and emerging markets. These factors, combined with consumers' willingness to invest in premium eye care products, continue to drive growth in the luxury contact lenses segment.
Image © Vijeron Intelligence. Reuse requires attribution under CC BY 4.0.
By End User:
Women Lead the Market, Unisex Redefines the Growth Equation
Women accounted for 52.35% of the luxury eyewear market in 2025, driven by the rising demand for premium fashion accessories that combine personal style with superior functionality. Female consumers increasingly view luxury eyewear as an integral part of their wardrobe, opting for designer frames and sunglasses that align with evolving fashion trends, craftsmanship, and brand prestige. Luxury brands regularly launch seasonal collections featuring diverse frame shapes, colors, embellishments, and lightweight materials to address shifting consumer preferences. The growing influence of fashion influencers, celebrities, and luxury advertising on digital platforms has further boosted product adoption, particularly among younger demographics. Additionally, factors such as rising disposable incomes, increased workforce participation among women, and higher spending on premium lifestyle products have bolstered demand for high-end eyewear. Innovations in frame ergonomics, lens technologies, and customizable designs are also enhancing comfort and aesthetics, encouraging repeat purchases and supporting sustained growth in the women's luxury eyewear segment.
The unisex segment is expected to grow at a CAGR of 6.81% through 2031, driven by increasing consumer preference for versatile, gender-neutral fashion that emphasizes individuality, simplicity, and timeless design over traditional gender-specific styles. Luxury eyewear brands are addressing this trend by introducing minimalist collections with universally appealing silhouettes, neutral color palettes, and premium materials, catering to a broader customer base. This strategy allows brands to expand their market reach while meeting the rising demand for inclusive and adaptable fashion products. The influence of contemporary fashion movements, evolving consumer attitudes toward self-expression, and the popularity of oversized, classic, and minimalist frame designs have further accelerated the adoption of unisex luxury eyewear. Additionally, the growth of online retail platforms and the availability of virtual try-on technologies enable consumers to explore a wider range of styles without gender-based shopping constraints. Combined with the increasing demand for multifunctional accessories suitable for various occasions, these factors continue to drive robust growth in the global luxury unisex eyewear segment.
By Distribution Channel:
Offline Retail Preserves Experience, Online Stores Drive Incremental Volume
Offline stores accounted for a significant 68.44% share of luxury eyewear distribution value in 2025. This dominance is attributed to consumers' preference for personalized service, product authenticity, and the ability to physically evaluate premium products before purchase. High-end boutiques, brand flagship stores, department stores, and luxury optical retailers offer professional services such as frame fitting, vision consultations, lens customization, and after-sales support, enhancing the overall customer experience. Customers value the opportunity to try on different frame styles to assess comfort, fit, craftsmanship, and aesthetics, especially when purchasing high-value prescription eyewear or designer sunglasses. Exclusive in-store product launches, limited-edition collections, and immersive luxury retail environments further enhance brand engagement and encourage premium purchases. Additionally, the assurance of purchasing genuine products from authorized retailers mitigates concerns about counterfeiting, bolstering customer confidence and driving the sustained growth of offline luxury eyewear sales.
Online stores represent the fastest-growing distribution channel, with a projected CAGR of 7.01% through 2031. This growth is driven by increasing digital adoption, enhanced convenience, and the expansion of premium e-commerce ecosystems. Online platforms provide consumers with access to a broader range of luxury brands, the ability to compare products, read customer reviews, and purchase exclusive collections from any location, making them an appealing option for affluent, digitally connected buyers. The integration of virtual try-on technologies using augmented reality, artificial intelligence-based style recommendations, and personalized product suggestions has significantly improved the online shopping experience, reducing uncertainties related to fit and appearance. Luxury brands are also strengthening direct-to-consumer channels through exclusive online launches, customized services, and seamless omnichannel experiences that integrate digital platforms with physical stores. Secure payment systems, faster delivery options, flexible return policies, and growing consumer trust in purchasing premium products online continue to drive the expansion of e-commerce, positioning it as one of the fastest-growing distribution channels in the global luxury eyewear market.
Image © Vijeron Intelligence. Reuse requires attribution under CC BY 4.0.
Section 5
Geography Analysis
Europe Luxury Eyewear Market
Europe is projected to hold a 31.93% share of the luxury eyewear market in 2025, driven by its strong heritage in luxury fashion, premium craftsmanship, and the presence of globally recognized eyewear manufacturers and designer brands. Consumers in the region highly value quality, timeless design, and brand prestige, sustaining demand for premium optical frames and sunglasses. The well-established network of luxury boutiques, optical retailers, and fashion houses further reinforces consumer confidence and brand loyalty. Additionally, rising awareness of eye health, increased adoption of prescription eyewear, and demand for technologically advanced lenses with UV and blue-light protection contribute to market growth. Europe's thriving tourism sector, frequent fashion events, sustainability-focused product innovations, and growing preference for environmentally responsible luxury goods also stimulate demand for high-end eyewear across both mature and emerging consumer segments.
APAC Luxury Eyewear Market
The Asia-Pacific region is the fastest-growing geography in the luxury eyewear market, with a projected CAGR of 7.13% through 2031. This growth is attributed to rising disposable incomes, a growing affluent middle class, and increasing consumer aspirations toward premium international brands. Rapid urbanization, expanding luxury retail infrastructure, and greater exposure to global fashion trends through social media have significantly boosted demand for designer eyewear in countries such as China, Japan, South Korea, India, and Southeast Asia. Younger consumers increasingly view luxury eyewear as a symbol of personal identity and social status. Additionally, growing awareness of eye health and rising incidences of vision correction needs support demand for premium optical products. The region's strong digital commerce ecosystem, widespread adoption of mobile shopping, and integration of virtual try-on technologies have further accelerated online luxury eyewear sales. Continuous product innovation, celebrity collaborations, and expanding brand presence through flagship stores and omnichannel strategies are also driving sustained market growth in the region.
The Americas and MEA Luxury Eyewear Market
The luxury eyewear market in North America, South America, and the Middle East and Africa is driven by rising premium consumer spending, increasing fashion consciousness, and growing awareness of eye protection and vision care. In North America, high disposable incomes, strong demand for designer brands, advanced retail infrastructure, and widespread adoption of premium prescription eyewear and sunglasses support market expansion. In South America, improving economic conditions, expanding urban populations, and increasing exposure to international luxury brands are encouraging greater spending on premium fashion accessories, particularly among younger consumers. Meanwhile, the Middle East and Africa benefit from a growing high-net-worth population, strong demand for luxury lifestyle products, expanding luxury retail developments, and climatic conditions that drive the use of premium sunglasses for UV protection. Across all three regions, digital retail expansion, omnichannel shopping experiences, celebrity influence, and continuous innovation in lightweight materials and advanced lens technologies further strengthen demand for luxury eyewear.
Image © Vijeron Intelligence. Reuse requires attribution under CC BY 4.0.
Section 6
Competitive Landscape
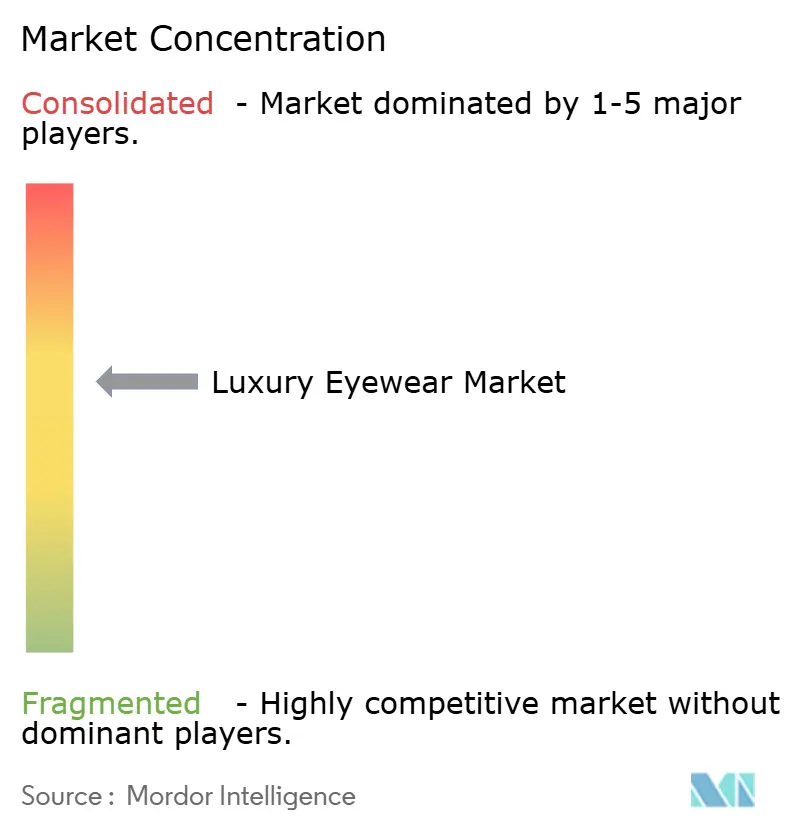
The global luxury eyewear market demonstrates a moderately concentrated competitive structure, with a small number of leading manufacturers holding a significant share of the premium designer eyewear segment. This dominance is largely attributed to long-term licensing agreements with globally recognized fashion brands. These exclusive partnerships create substantial barriers to entry by granting access to valuable brand portfolios for extended periods. This enables established players to maintain extensive international distribution networks and consistent product development pipelines. Additionally, manufacturers are increasingly adopting vertical integration strategies, investing in proprietary lens production, premium materials, and advanced manufacturing capabilities. These efforts aim to improve quality control, reduce reliance on suppliers, and enhance product differentiation within luxury collections.
Competition within the market is also being shaped by technological advancements, as premium eyewear companies expand beyond traditional fashion products into connected and intelligent eyewear. Strategic collaborations with technology platform providers are accelerating the development of AI-enabled smart glasses, advanced optical systems, and digital consumer experiences. These investments position technology integration as a key future competitive advantage, allowing manufacturers to merge luxury design with wearable technology, personalized functionality, and improved customer engagement. Companies that establish robust technology ecosystems and exclusive innovation partnerships are expected to strengthen their market positions as smart luxury eyewear gains broader adoption.
In addition to the dominant global players, a fragmented group of independent luxury eyewear brands competes by focusing on craftsmanship, limited production, innovative materials, and distinctive designs rather than relying on licensed fashion labels. These brands often target collectors and affluent consumers seeking exclusivity, authenticity, and artisanal manufacturing. By leveraging scarcity and unique product positioning, they command premium prices. Some brands further differentiate themselves through immersive retail concepts, transforming physical stores into experiential destinations to foster stronger emotional connections with consumers. Meanwhile, mid-sized manufacturers are diversifying their portfolios through acquisitions in premium outdoor and performance eyewear categories, aiming to broaden revenue streams.
Luxury Eyewear Industry Leaders
*
De Rigo Vision S.p.A.
*
Marcolin S.p.A.
*
Safilo Group S.p.A.
*
Kering Eyewear
*
EssilorLuxottica
*
*Disclaimer: Major Players sorted in no particular order
Image © Vijeron Intelligence. Reuse requires attribution under CC BY 4.0.
Luxury Eyewear Market Companies Covered in this Report
- EssilorLuxottica
- Kering Eyewear
- Safilo Group S.p.A.
- Marcolin S.p.A.
- De Rigo Vision S.p.A.
- Marchon Eyewear, Inc.
- LVMH Moët Hennessy Louis Vuitton
- Richemont
- Prada S.p.A.
- Chanel S.A.
- Burberry Group plc
- The Estée Lauder Companies Inc.
- Maui Jim, Inc.
- Barton Perreira, LLC
- Jacques Marie Mage, LLC
- MYKITA Holding GmbH
- Fielmann Group AG
- CHARMANT Group
- A. Kjaerbede ApS
- LINDBERG A/S
-->
-->
Section 7
Recent Industry Developments in Luxury Eyewear Market
- May 2026: Safilo Group signed a binding Share and Asset Purchase Agreement to acquire SPY+ and Serengeti brands from Bollé Brands for USD 26 million. The two brands generated combined sales of approximately USD 39 million in 2025. The acquisition advances Safilo's strategy of acquiring brands in high-growth performance and premium outdoor segments, diversifying its portfolio beyond licensed luxury fashion.
- March 2026: EssilorLuxottica and Meta have introduced an expanded Ray-Ban Meta AI glasses portfolio, featuring new prescription-compatible optical-first styles (Gen 2), such as Ray-Ban Meta Blayzer Optics and Scriber Optics, with prices starting at USD 499. The geographic availability now includes Japan, South Korea, Singapore, Chile, Peru, and Colombia, with plans for further expansion to Brazil, Mexico, and India by 2026.
- March 2026: EssilorLuxottica and Dolce & Gabbana extended their license agreement through 2050, covering the global development, production, and distribution of prescription frames and sunglasses under the Dolce & Gabbana brand.
Section 8
Table of Contents for Luxury Eyewear Industry Report
- INTRODUCTION
*
1.1 Study Assumptions and Market Definition
*
1.2 Scope of the Study
- RESEARCH METHODOLOGY
- EXECUTIVE SUMMARY
- MARKET LANDSCAPE
*
4.1 Market Overview
*
4.2 Market Drivers
*
4.2.1 Growing consumer preference for premium fashion accessories
*
4.2.2 Growing popularity of celebrity, fashion house, and influencer collaborations
*
4.2.3 Increasing consumer awareness of UV protection and eye health
*
4.2.4 Expansion of digital retail and omnichannel luxury shopping
*
4.2.5 Rising demand for limited-edition and exclusive collections
*
4.2.6 Growing demand for sustainable and ethical luxury products
*
4.3 Market Restraints
*
4.3.1 Proliferation of counterfeit luxury eyewear
*
4.3.2 Stringent regulatory requirements for optical products
*
4.3.3 Intense competition from non-luxury eyewear brands
*
4.3.4 Supply chain challenges for premium materials
*
4.4 Consumer Behavior Analysis
*
4.5 Regulatory Landscape
*
4.6 Porter's Five Forces
*
4.6.1 Threat of New Entrants
*
4.6.2 Bargaining Power of Suppliers
*
4.6.3 Bargaining Power of Buyers
*
4.6.4 Threat of Substitutes
*
4.6.5 Competitive Rivalry
- MARKET SIZE AND GROWTH FORECASTS (VALUE)
*
5.1 By Product Type
*
5.1.1 Spectacles
*
5.1.2 Sunglasses
*
5.1.3 Contact Lenses
*
5.1.4 Other Product Types
*
5.2 By End User
*
5.2.1 Men
*
5.2.2 Women
*
5.2.3 Unisex
*
5.3 By Distribution Channel
*
5.3.1 Offline Stores
*
5.3.2 Online Stores
*
5.4 By Geography
*
5.4.1 North America
*
5.4.1.1 United States
*
5.4.1.2 Canada
*
5.4.1.3 Mexico
*
5.4.1.4 Rest of North America
*
5.4.2 Europe
*
5.4.2.1 Germany
*
5.4.2.2 United Kingdom
*
5.4.2.3 Italy
*
5.4.2.4 France
*
5.4.2.5 Spain
*
5.4.2.6 Netherlands
*
5.4.2.7 Poland
*
5.4.2.8 Belgium
*
5.4.2.9 Sweden
*
5.4.2.10 Rest of Europe
*
5.4.3 Asia-Pacific
*
5.4.3.1 China
*
5.4.3.2 India
*
5.4.3.3 Japan
*
5.4.3.4 Australia
*
5.4.3.5 Indonesia
*
5.4.3.6 South Korea
*
5.4.3.7 Thailand
*
5.4.3.8 Singapore
*
5.4.3.9 Rest of Asia-Pacific
*
5.4.4 South America
*
5.4.4.1 Brazil
*
5.4.4.2 Argentina
*
5.4.4.3 Colombia
*
5.4.4.4 Chile
*
5.4.4.5 Peru
*
5.4.4.6 Rest of South America
*
5.4.5 Middle East and Africa
*
5.4.5.1 South Africa
*
5.4.5.2 United Arab Emirates
*
5.4.5.3 Saudi Arabia
*
5.4.5.4 Nigeria
*
5.4.5.5 Egypt
*
5.4.5.6 Morocco
*
5.4.5.7 Turkey
*
5.4.5.8 Rest of Middle East and Africa
- COMPETITIVE LANDSCAPE
*
6.1 Market Concentration
*
6.2 Strategic Moves
*
6.3 Market Share Analysis
*
6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials (if available), Strategic Information, Market Share for key companies, Products, and Recent Developments)
*
6.4.1 EssilorLuxottica
*
6.4.2 Kering Eyewear
*
6.4.3 Safilo Group S.p.A.
*
6.4.4 Marcolin S.p.A.
*
6.4.5 De Rigo Vision S.p.A.
*
6.4.6 Marchon Eyewear, Inc.
*
6.4.7 LVMH Moët Hennessy Louis Vuitton
*
6.4.8 Richemont
*
6.4.9 Prada S.p.A.
*
6.4.10 Chanel S.A.
*
6.4.11 Burberry Group plc
*
6.4.12 The Estée Lauder Companies Inc.
*
6.4.13 Maui Jim, Inc.
*
6.4.14 Barton Perreira, LLC
*
6.4.15 Jacques Marie Mage, LLC
*
6.4.16 MYKITA Holding GmbH
*
6.4.17 Fielmann Group AG
*
6.4.18 CHARMANT Group
*
6.4.19 A. Kjaerbede ApS
*
6.4.20 LINDBERG A/S
- MARKET OPPORTUNITIES AND FUTURE OUTLOOK
Section 9
Global Luxury Eyewear Market Report Scope
By Product Type
Spectacles
Sunglasses
Contact Lenses
Other Product Types
By End User
Men
Women
Unisex
By Distribution Channel
Offline Stores
Online Stores
By Geography
North America
United States
Canada
Mexico
Rest of North America
Europe
Germany
United Kingdom
Italy
France
Spain
Netherlands
Poland
Belgium
Sweden
Rest of Europe
Asia-Pacific
China
India
Japan
Australia
Indonesia
South Korea
Thailand
Singapore
Rest of Asia-Pacific
South America
Brazil
Argentina
Colombia
Chile
Peru
Rest of South America
Middle East and Africa
South Africa
United Arab Emirates
Saudi Arabia
Nigeria
Egypt
Morocco
Turkey
Rest of Middle East and Africa
By Product Type
Spectacles
Sunglasses
Contact Lenses
Other Product Types
By End User
Men
Women
Unisex
By Distribution Channel
Offline Stores
Online Stores
By Geography
North America
United States
Canada
Mexico
Rest of North America
Europe
Germany
United Kingdom
Italy
France
Spain
Netherlands
Poland
Belgium
Sweden
Rest of Europe
Asia-Pacific
China
India
Japan
Australia
Indonesia
South Korea
Thailand
Singapore
Rest of Asia-Pacific
South America
Brazil
Argentina
Colombia
Chile
Peru
Rest of South America
Middle East and Africa
South Africa
United Arab Emirates
Saudi Arabia
Nigeria
Egypt
Morocco
Turkey
Rest of Middle East and Africa
Section 10
Key Questions Answered in the Report
What is the 2026 value of the luxury eyewear market?
The luxury eyewear market stands at USD 56.13 billion in 2026 and is forecast to reach USD 75.67 billion by 2031 at a 6.16% CAGR.
Which product category leads revenue in luxury eyewear?
Sunglasses lead the category with a 49.87% share in 2025, and they also post the fastest product growth at a 6.73% CAGR through 2031.
Which buyer group is driving the strongest future demand?
Women remain the largest buyer group with a 52.35% share in 2025, while unisex eyewear is the fastest-growing end-user segment at a 6.81% CAGR.
Which region is expanding the fastest through 2031?
Asia-Pacific is the fastest-growing region with a 7.13% CAGR, supported by premiumization, younger buyers, and stron
Section 11
Related Reports
Explore More Reports
Find Latest Data on
Luxury Watch Market
Luxury Goods Market Analysis
United States Luxury Goods Market Report
UK Luxury Goods Market Report
North America Luxury Goods Market Growth
Luxury Jewelry Industry Overview
Germany Luxury Goods Market Share
Russia Luxury Goods Market Report
Brazil Luxury Goods Market Size
South Korea Luxury Goods Industry Overview
Activewear Market
Sleepwear and Loungewear Market Size